
What Is GAAP? Generally Accepted Accounting Principles Explained

GAAP (generally accepted accounting principles) is the set of accounting standards used in the United States to prepare financial statements. The Financial Accounting Standards Board (FASB) issues these standards through its Accounting Standards Codification, and the Securities and Exchange Commission (SEC) requires public companies to follow them. GAAP gives investors and lenders a common basis for comparing companies.
For intermediate accounting, begin with five questions: Why are standards needed? Who uses the information? Who develops the standards? Where is authoritative guidance found? Who requires a company to follow it? Answering these questions explains the financial reporting environment before you move into detailed accounting rules.
Key takeaways
- GAAP is the common language of U.S. financial reporting. It makes financial statements comparable across companies.
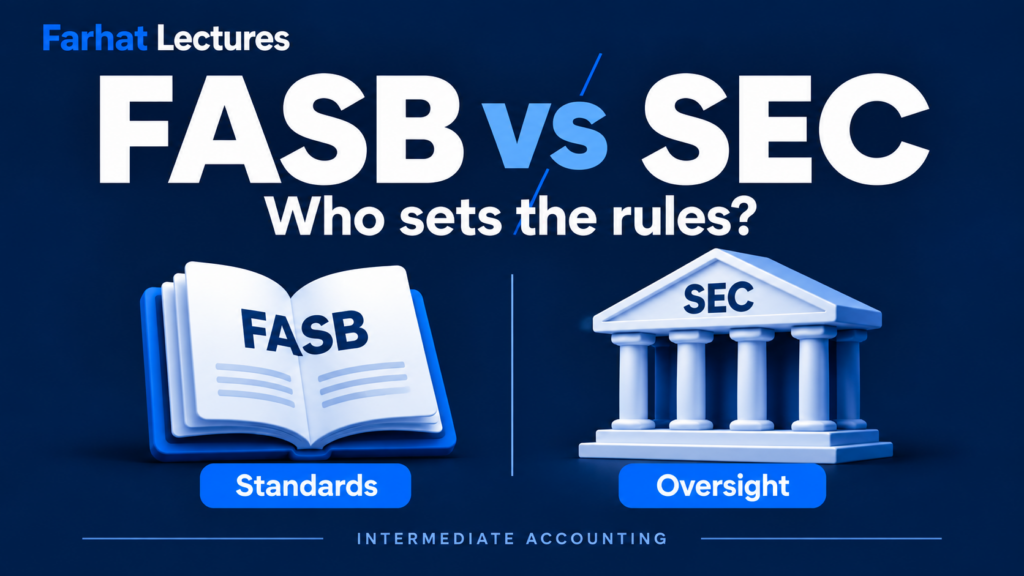
- FASB writes GAAP. The SEC has legal authority over public company reporting and recognizes FASB’s standards.
- The FASB Accounting Standards Codification (ASC) is the only authoritative source of nongovernmental U.S. GAAP. An ASU amends it, and a Concepts Statement explains the thinking behind it.
- Public companies must follow GAAP. Private companies often do because a lender or investor asks for it.
- GAAP is not IFRS (used outside the U.S.) and not GASB (used by state and local governments).
1. Why does GAAP matter? It gives reporting a common basis
Imagine comparing two manufacturers when each uses its own definition of sales, expenses, and assets. Even if both companies label a number “profit,” the numbers might not represent comparable accounting. Investors would have to learn each company’s personal reporting rules before making a useful comparison.
GAAP reduces that problem by providing shared standards. It helps readers interpret reported results within an established framework. It does not make two different businesses identical, remove every estimate, or guarantee that every company will succeed. Comparability improves when similar transactions are reported using the same rules. In the FASB conceptual framework, comparability is one of the qualities that makes financial information more useful. You can read about it in the FASB conceptual framework lesson.
A useful memory aid is common standards → more comparable information → better-informed decisions. This describes the purpose of standards.
Watch: What GAAP means and why it matters
In this short segment, Professor Farhat explains the meaning of GAAP and how common reporting standards support consistency, transparency, and comparability. The embedded segment runs from 2:21 to 4:41. The full video, What Is GAAP? Accounting Rules, FASB, SEC & IFRS Explained, also walks through the roles of FASB and the SEC and how U.S. GAAP compares with IFRS.
Watch the full GAAP lesson on the Farhat Lectures YouTube channel.
2. Who uses GAAP financial information?
| User | Typical question | Why financial information helps |
|---|---|---|
| Owner or manager | Is the business earning income and using resources effectively? | It provides information about operations, resources, and obligations. |
| Lender or other creditor | Can the business meet its payment obligations? | It helps assess future cash flows and repayment risk. |
| Current or potential investor | Should I invest in this company? | It helps compare expected returns, risks, and financial performance. |
These users do not all make the same decision. A lender focuses on repayment, while a shareholder considers the potential return and risk of an ownership investment. Both need useful information about the company. The role of accounting is to support those decisions with relevant financial reporting.
Consider a fictional company, Pine Manufacturing, seeking a bank loan. The bank reviews financial statements as part of its assessment of whether Pine can repay principal and interest. The statements provide a starting point for analysis; they do not guarantee repayment. This distinction explains why useful reporting matters even when the future remains uncertain.
3. Who sets GAAP? FASB develops nongovernmental U.S. GAAP
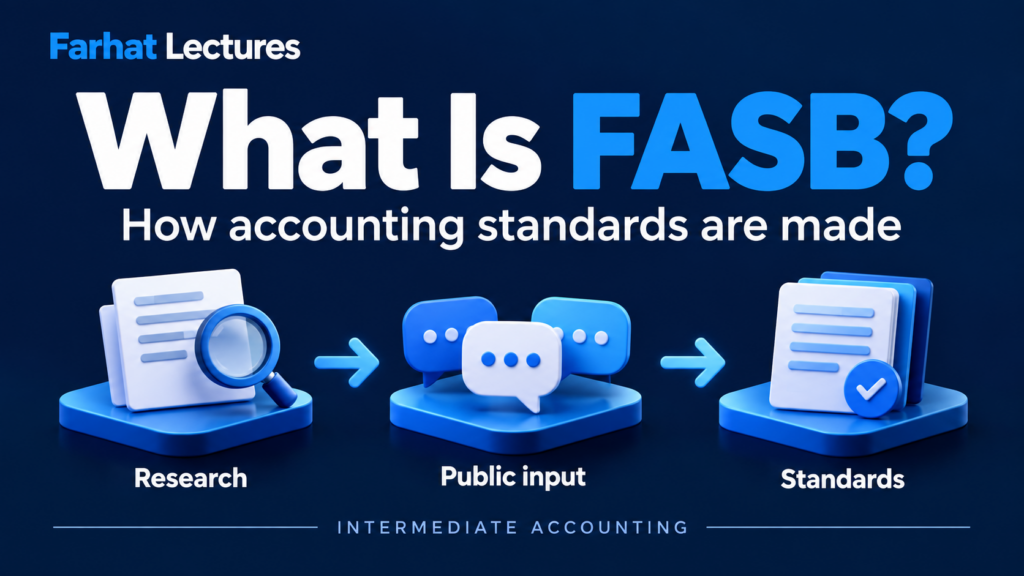
The Financial Accounting Standards Board (FASB) is the principal private-sector standard setter for nongovernmental financial reporting in the United States. Nongovernmental means businesses and not-for-profit organizations, not governments. FASB was created in 1973 and is based in Norwalk, Connecticut. It develops and improves accounting guidance through a process that includes research, public comment, and input from preparers, auditors, investors, and other users.
Governments use different standard setters. State and local governments follow the Governmental Accounting Standards Board (GASB), and the federal government follows the Federal Accounting Standards Advisory Board (FASAB). Both are outside the scope of this lesson, but the CPA exam does test GASB reporting in the FAR section. If you need that topic, start with the Governmental Accounting course.
The Securities and Exchange Commission has authority over financial reporting within its jurisdiction and recognizes the Board’s standard-setting role. Their relationship is a public/private partnership. For a comparison, read FASB vs SEC. For the development process, read what FASB does.
The American Institute of CPAs (AICPA) is the professional organization for CPAs. It set accounting standards before FASB existed, first through the Committee on Accounting Procedure (1939 to 1959) and then through the Accounting Principles Board (1959 to 1973). Today the AICPA develops the CPA exam and sets auditing standards for private companies, but it does not set U.S. GAAP. On the exam, do not pick the AICPA as today’s principal setter of nongovernmental U.S. GAAP.
Exam tip: FAR questions often test who does what. FASB writes the standards. The SEC has the legal authority over public company reporting and recognizes FASB’s standards. The AICPA writes the CPA exam and sets auditing standards for private companies, but it stopped setting GAAP in 1973. GASB sets standards for state and local governments. If a question asks who issues U.S. GAAP for businesses, the answer is FASB.
4. Where is GAAP written down? The FASB Codification
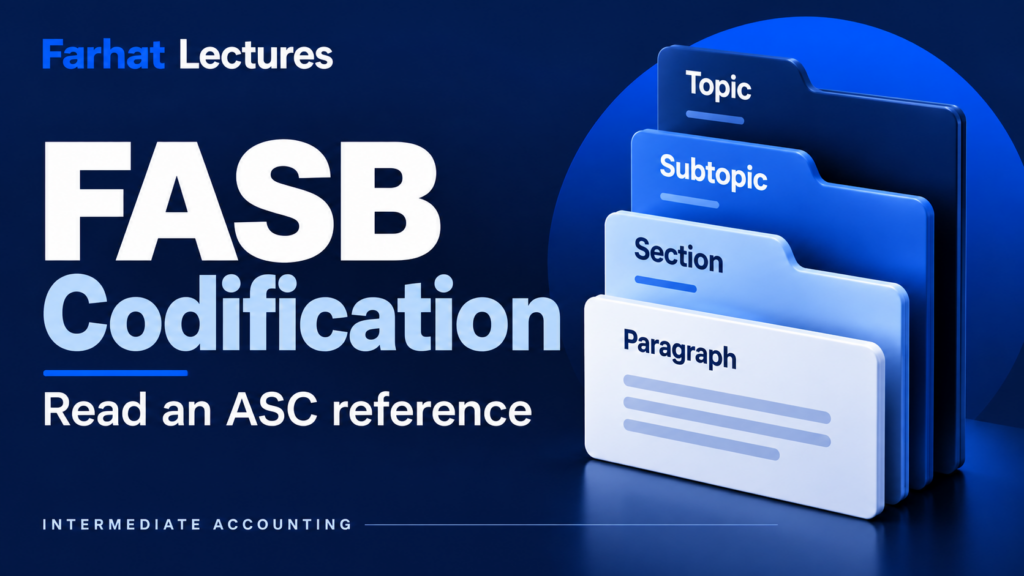
The FASB Accounting Standards Codification, or ASC, is the single source of authoritative U.S. GAAP for nongovernmental entities. It took effect for periods ending after September 15, 2009 and replaced the older system of separately numbered standards. The Codification states this in ASC 105-10-05-1. Rules and interpretive releases of the SEC (the SEC’s own reporting rules and its official explanations of them) are also authoritative for SEC registrants, meaning companies that file reports with the SEC. Educational explanations, including textbooks and this lesson, help you learn the rules, but they are not authoritative. You can access the Codification at asc.fasb.org and SEC reporting rules at sec.gov.
An Accounting Standards Update (ASU) is the document FASB issues to amend the Codification. The ASU itself is not authoritative; its amendments become authoritative once they are placed in the ASC. A Statement of Financial Accounting Concepts has a different purpose: it sets out the objectives and concepts FASB uses when developing standards. Concepts Statements are listed as nonauthoritative in ASC 105-10-05-3, along with textbooks, articles, and industry practice. The FASB standards overview identifies these distinctions.
Keep three ideas separate: the Board develops standards, the Codification organizes guidance, and an update communicates amendments. Learn how to locate guidance in the Codification tutorial, and compare the documents in the ASU vs ASC guide.
Want the full lecture? The Intermediate Accounting course covers the financial reporting environment, the conceptual framework, and the standards that follow, with worked examples and practice questions.
5. Who must follow GAAP? Public and private companies
Do not assume that only public companies prepare financial statements under this framework. A private company may need GAAP financial statements because of a loan agreement, an owner’s requirement, or another reporting obligation. The relevant requirement depends on the company’s circumstances.
Return to Pine Manufacturing. If its bank requires GAAP financial statements, that condition matters even though Pine is privately owned. However, the loan agreement does not by itself make Pine an SEC registrant. Using an accounting framework and filing reports with a regulator are related but separate issues.
So who must follow GAAP? Public companies that file with the SEC must use U.S. GAAP. (The SEC does allow foreign companies listed in the U.S. to file under IFRS as issued by the IASB.) Private companies are not required by law to use GAAP, but lenders, investors, and auditors often ask for GAAP financial statements. A small private company may instead use a special purpose framework, such as the cash basis, the income tax basis, or the AICPA’s Financial Reporting Framework for Small- and Medium-Sized Entities. FASB’s Private Company Council also offers simplified GAAP alternatives for private companies, such as amortizing goodwill instead of testing it only for impairment. The key point: private ownership alone does not make accounting standards irrelevant.
GAAP vs IFRS: the quick comparison
Students often mix up GAAP and IFRS. Here is the short version.
| Question | U.S. GAAP | IFRS Accounting Standards |
|---|---|---|
| Who sets it? | Financial Accounting Standards Board (FASB) | International Accounting Standards Board (IASB) |
| Where is it used? | United States | Most other major economies, including the European Union, the United Kingdom, Canada, and Australia |
| How is it often described? | More rules-based, with detailed industry guidance | More principles-based, with more room for judgment |
| One classic difference | LIFO inventory costing is allowed | LIFO inventory costing is prohibited |
For the organization-level comparison, read FASB vs IASB. For the standards themselves, the International Accounting course covers IFRS in depth.
Practice questions about GAAP
1. Does a common reporting framework make different companies economically identical? No. It supports more meaningful comparison of financial information. Differences in operations, risks, and performance still exist.
2. A private company’s lender requires statements prepared under U.S. GAAP. Can the company ignore that condition because it is private? No. Its reporting obligation can arise from its agreement with the lender. Public-company status is not the only reason to use the framework.
3. A textbook explains an accounting treatment. Is the textbook authoritative guidance? No. It is educational material. For an accounting conclusion, identify and apply the relevant authoritative requirements.
4. A city government prepares its annual financial report. Does it follow FASB standards? No. State and local governments follow standards set by the Governmental Accounting Standards Board (GASB). FASB sets standards for businesses and nongovernmental not-for-profit organizations. The federal government follows the Federal Accounting Standards Advisory Board (FASAB).
5. FASB issues an Accounting Standards Update. Is the ASU itself the authoritative guidance? No. An ASU is the document that amends the Codification. Once the amendments are placed in the Codification, the Codification is the authoritative source. Cite the ASC paragraph, not the ASU number, when you need the rule.
Frequently asked questions about GAAP
Is GAAP the name of an organization? No. GAAP stands for generally accepted accounting principles, meaning the standards themselves. FASB writes the standards and the SEC oversees public company reporting.
Who must follow GAAP? Public companies that file with the SEC must use U.S. GAAP. Private companies are not required by law to use it, but many do because a lender, investor, or auditor asks for GAAP financial statements.
Is GAAP a law? No. FASB is a private, not-for-profit organization. GAAP has legal force for public companies because the SEC, which has authority under federal securities laws, requires registrants to follow FASB standards.
Where is GAAP written down? In the FASB Accounting Standards Codification (ASC). Since 2009 it has been the single source of authoritative GAAP for nongovernmental entities (ASC 105).
Is U.S. GAAP the same as IFRS? No. They are distinct accounting frameworks. The IASB develops IFRS Accounting Standards. See FASB vs IASB for the organization-level comparison.
Does following standards eliminate uncertainty? No. Financial reporting can involve estimates and judgments. The standards provide a framework for useful reporting even when outcomes remain uncertain.
Does GAAP apply to governments? Not FASB GAAP. State and local governments follow GASB standards and the federal government follows FASAB standards. FASB sets GAAP for businesses and not-for-profit organizations.
Is GAAP on the CPA exam? Yes. The FAR section tests U.S. GAAP for businesses and not-for-profit organizations and also covers state and local government reporting. Practice with the FAR test bank.

Responses