
FASB vs SEC: 5 Key Differences Made Simple

Last updated:
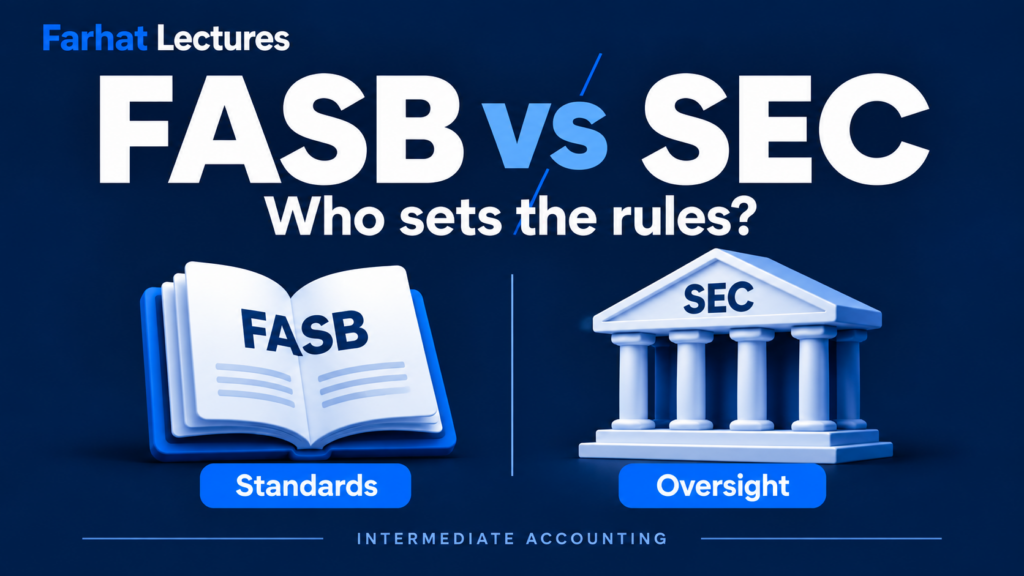
FASB vs SEC: the FASB writes U.S. accounting standards; the SEC regulates financial reporting by public companies. The Financial Accounting Standards Board (FASB) is an independent private-sector body that sets U.S. GAAP for businesses and not-for-profits. The Securities and Exchange Commission (SEC) is a federal agency with legal authority over public company reporting, and it recognizes FASB standards as authoritative.
For intermediate accounting, the goal is to identify each organization’s job. A few terms will come up often. GAAP stands for generally accepted accounting principles, the rulebook for U.S. financial statements. A registrant is a company that files reports with the SEC, such as a public company. Nongovernmental means businesses and not-for-profit organizations, not federal, state, or local governments. Understanding FASB vs SEC helps you explain who develops U.S. GAAP, who oversees public-company reporting, and why the two organizations work together.
What are the 5 key differences between FASB and SEC?
| Question | FASB | SEC |
|---|---|---|
| 1. What kind of organization is it? | An independent, not-for-profit organization in the private sector, overseen by the Financial Accounting Foundation (FAF). | A federal government agency. |
| 2. What is its central role here? | Develop and improve financial accounting and reporting standards. | Oversee financial reporting and enforce securities-law requirements within its jurisdiction. |
| 3. What does it produce? | Amendments to the Accounting Standards Codification, communicated through Accounting Standards Updates. | Rules such as Regulation S-X (the form and content of financial statements in SEC filings) and staff guidance such as Staff Accounting Bulletins (SABs). |
| 4. Who is affected? | Nongovernmental entities that prepare financial statements under U.S. GAAP. | Companies and other participants subject to SEC requirements. |
| 5. How do they relate? | Acts as the recognized private-sector standard setter. | Recognizes the FASB’s standards and retains oversight and legal authority. |
The fourth difference is easy to miss. FASB standards are relevant to both public companies and private companies using U.S. GAAP. SEC reporting requirements do not automatically apply to every business simply because it follows GAAP. A private company may prepare GAAP financial statements for a lender without becoming an SEC registrant.
Quick facts: how FASB and the SEC are set up
| FASB | SEC | |
|---|---|---|
| Created | 1973. It replaced the Accounting Principles Board (APB) of the American Institute of CPAs (AICPA). | 1934, by the Securities Exchange Act of 1934. |
| Who runs it | Seven full-time board members, appointed by the Financial Accounting Foundation (FAF) for five-year terms, with a limit of ten years. | Five commissioners appointed by the President and confirmed by the Senate for staggered five-year terms. |
| How it is funded | Mainly accounting support fees paid by public companies under Section 109 of the Sarbanes-Oxley Act of 2002, plus sales of publications and subscriptions. | Federal funding set through the congressional budget process. |
| Source of its authority | Recognition by the SEC: Accounting Series Release No. 150 (1973) and the 2003 policy statement issued after Section 108 of the Sarbanes-Oxley Act. | Federal securities laws, mainly the Securities Act of 1933 and the Securities Exchange Act of 1934. |
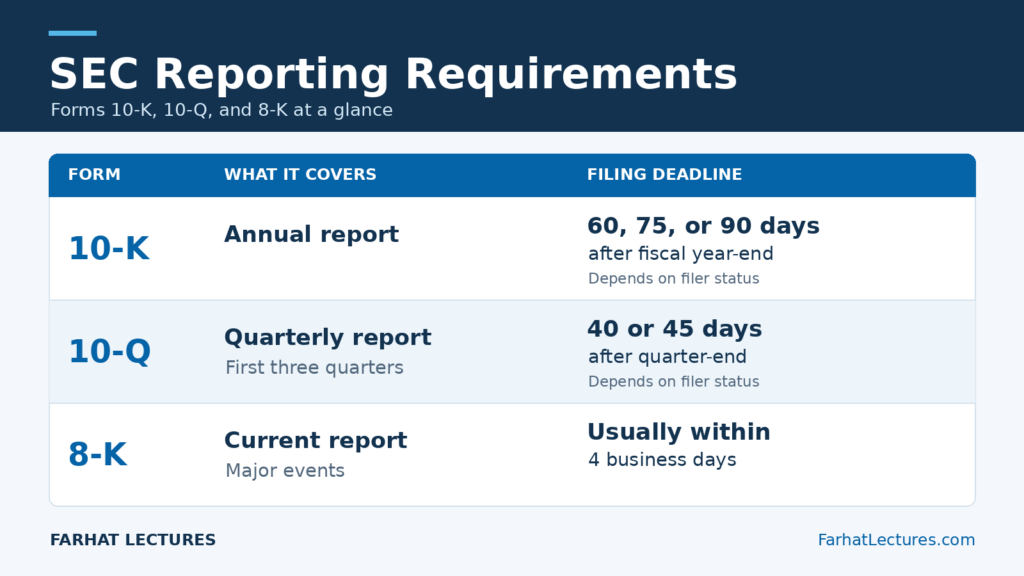
| Main output | Accounting Standards Updates (ASUs) that amend the Accounting Standards Codification (ASC). | Regulation S-X, Regulation S-K, Staff Accounting Bulletins, Financial Reporting Releases, and the rules for Forms 10-K, 10-Q, and 8-K. |
Sources: SEC Policy Statement, Release No. 33-8221 (April 25, 2003) and the FASB’s own About the FASB overview.
How do FASB and the SEC work together?
The SEC has authority over accounting standards for companies within its jurisdiction. It generally relies on the FASB’s expertise to develop those standards. This arrangement combines a private standard setter with public oversight. The SEC can raise reporting concerns, comment on proposals, and work with the FASB on implementation issues.
That relationship does not make the FASB a government agency. It also does not mean the SEC has surrendered its authority. The arrangement has a paper trail. In 1973 the SEC issued Accounting Series Release No. 150, which said FASB pronouncements would be treated as authoritative. In 2002, Section 108 of the Sarbanes-Oxley Act set criteria a private standard setter must meet. In 2003 the SEC confirmed that the FASB meets those criteria in its policy statement reaffirming the FASB as a designated private-sector standard setter (Release No. 33-8221). The same law, in Section 108(c), says nothing in it limits the SEC’s own authority to set accounting standards for enforcement of the securities laws.
A useful memory aid is FASB develops accounting guidance; SEC oversees reporting within its jurisdiction. Treat this as a starting point. The SEC can issue its own accounting and disclosure requirements, so “the SEC only enforces and never sets requirements” is too absolute.
Here is the rule that ties the two together for a public company. The Codification itself, in ASC 105-10-05-1, says that rules and interpretive releases of the SEC are also sources of authoritative GAAP for SEC registrants. So a public company’s accountant checks the Codification first and then checks SEC requirements such as Regulation S-X. A private company that is not an SEC registrant follows the Codification without the SEC layer.
To see how proposed guidance becomes an amendment, read what FASB does and how its due process works. To locate the accounting requirements themselves, use the FASB Codification guide.
Watch: FASB and SEC roles explained
In this focused segment, Professor Farhat explains FASB’s role in developing U.S. accounting standards, the SEC’s oversight responsibilities, and how the two organizations relate. Watch from 6:38 to 10:28, then apply the distinction in the example below.
Timestamps inside the segment: 6:38 FASB and U.S. accounting standards, 7:38 SEC oversight and investor protection, 9:28 how FASB and the SEC relate. The full lesson is a What Is GAAP? introduction, so the first six minutes cover GAAP basics before this segment.
Watch the full Farhat Lectures lesson on YouTube.
Keep the distinction clear: FASB is an independent private-sector standard setter. The SEC recognizes FASB’s standards and retains legal authority over financial reporting by SEC registrants.
How do FASB and SEC rules apply to one company? A simple example
Assume Harbor Manufacturing is a U.S. public company preparing financial statements. Its accountant must determine the accounting treatment for a transaction. The accountant researches the relevant U.S. GAAP requirements in the Codification. That is the accounting-standard side of the problem.
Harbor must also meet the reporting and disclosure requirements that apply to its SEC filings. If the SEC staff questions a disclosure, Harbor must address the issue through the applicable review process. That is the regulatory-oversight side. Both responsibilities can apply to the same financial statements.
Now assume Harbor is privately owned and a bank requires GAAP financial statements as a loan condition. The accountant still needs the applicable GAAP guidance. However, that loan condition alone does not turn Harbor into a public company or require SEC filings. The reporting framework and the regulatory filing obligation are separate questions.
What are the most common mistakes when comparing FASB vs SEC?
Mistake 1: “FASB and SEC are two names for the same organization.” They are separate organizations with different responsibilities. Their cooperation does not merge their roles.
Mistake 2: “Only public companies use FASB standards.” Private companies can also prepare GAAP financial statements, including when owners or creditors require them.
Mistake 3: “An Accounting Standards Update is the authoritative rulebook.” An update communicates amendments. The Codification is the authoritative source recognized by the FASB for nongovernmental U.S. GAAP; SEC requirements also matter for registrants. See the ASU vs ASC explanation.
Mistake 4: “FASB sets the standards for government accounting too.” It does not. State and local governments follow the Governmental Accounting Standards Board (GASB), which is also overseen by the FAF. The federal government follows the Federal Accounting Standards Advisory Board (FASAB). That is why FASB’s scope is described as nongovernmental.
Exam tip: how FASB vs SEC shows up on the CPA Exam
On the CPA Exam, the FAR section covers the financial reporting environment and the basics of public company reporting, and the BAR discipline section goes deeper into public company reporting topics. Questions on FASB vs SEC are usually recall questions, so watch for the key words private sector, standard setter, federal agency, and registrant. Try this one.
Which statement about the FASB and the SEC is correct?
A. The SEC is a private-sector body that develops U.S. GAAP.
B. The FASB has legal authority to enforce the federal securities laws.
C. The SEC recognizes FASB standards as authoritative but keeps its own legal authority over accounting by SEC registrants.
D. FASB standards apply only to public companies.
Answer: C. Choice A reverses the roles. Choice B gives the FASB a power it does not have; enforcement belongs to the SEC. Choice D is wrong because private companies and not-for-profits also follow FASB standards. Choice C states the relationship correctly: recognition plus retained authority.
Want more questions like this? Try the FAR Test Bank.
Key takeaways
- The FASB is an independent, private-sector body overseen by the Financial Accounting Foundation (FAF). It sets U.S. GAAP for businesses and not-for-profits.
- The SEC is a federal agency created in 1934 with legal authority over financial reporting by SEC registrants.
- The SEC recognized the FASB in 1973 (Accounting Series Release No. 150) and reaffirmed that recognition in 2003 under Section 108 of the Sarbanes-Oxley Act.
- The SEC still issues its own requirements, such as Regulation S-X and Staff Accounting Bulletins, and ASC 105 treats SEC rules as authoritative GAAP for registrants.
- Using GAAP does not make a company an SEC registrant. Private companies follow FASB standards without SEC filing obligations.
- Governments do not use FASB standards. State and local governments follow GASB, and the federal government follows FASAB.
Need a refresher? Review the five differences between FASB and SEC, then apply what you learned to the worked practice questions below.
Practice questions: identify the organization
1. An organization considers changing how a transaction is reported under U.S. GAAP. Which organization is the private-sector standard setter?
FASB. The key words are “private-sector” and “standard setter.” The question concerns developing accounting guidance.
2. A U.S. public company faces questions about disclosures in an SEC filing. Which organization has the regulatory role?
SEC. This question concerns oversight of a registrant’s reporting, rather than development of a new accounting standard. In practice, the SEC’s Division of Corporation Finance reviews filings and sends comment letters that the company must answer.
3. A private company follows GAAP because its lender requires it. Does that fact alone make the company an SEC registrant?
No. A lender’s reporting condition does not by itself create SEC registration or filing obligations.
Frequently asked questions about FASB vs SEC
Is FASB part of the SEC?
No. The FASB is an independent, private-sector organization overseen by the Financial Accounting Foundation (FAF). The SEC is a federal government agency. The SEC recognizes the FASB’s standards and keeps legal authority over reporting by SEC registrants.
Does the SEC set accounting standards or only enforce them?
Both, in practice. The SEC has legal authority to set accounting standards for registrants under the federal securities laws, and it relies on the FASB to write most of them. It still issues its own rules, such as Regulation S-X, and staff guidance, such as Staff Accounting Bulletins (SABs). ASC 105-10-05-1 treats SEC rules and interpretive releases as authoritative GAAP for SEC registrants.
Which has more authority, FASB or the SEC?
The SEC. Its authority comes from federal law. The FASB’s authority for public companies comes from the SEC’s recognition, first in Accounting Series Release No. 150 in 1973 and again in a 2003 policy statement issued under Section 108 of the Sarbanes-Oxley Act. The SEC can decline to accept a FASB standard, although it has rarely done so.
Does the SEC control all accounting in the United States?
No. Its authority relates to entities and activities within its jurisdiction, mainly companies that file with the SEC. Do not treat every organization that uses accounting information as an SEC registrant.
Do private companies have to follow FASB standards?
The SEC does not require private companies to file financial statements, but when a private company prepares financial statements under U.S. GAAP, those statements follow FASB standards. Lenders, investors, and owners often require GAAP statements. The FASB’s Private Company Council (PCC) advises the FASB on alternatives for private companies.
Who funds the FASB and the SEC?
The FASB is funded mainly by accounting support fees paid by public companies under Section 109 of the Sarbanes-Oxley Act of 2002, plus publication and subscription revenue. The SEC is a federal agency funded through the congressional budget process.
Which organization should I name when asked who sets U.S. GAAP?
For nongovernmental financial reporting, identify FASB as the principal private-sector standard setter. Add the SEC’s authority and requirements when the question concerns SEC registrants. For state and local governments, name GASB.
About the author
Mansour Farhat, CPA, CIA, DBA, is an accounting professor and the founder of Farhat Lectures. He teaches financial, intermediate, advanced, cost, and governmental accounting, auditing, and tax through video lessons, practice questions, and test banks for accounting students and CPA and CMA candidates. Read more about Professor Farhat or connect on LinkedIn.

Responses