
What Is Accounting? Definition, Types, and Examples

What is accounting? Accounting is an information system that identifies, records, and communicates an organization’s economic events so investors, lenders, managers, and other users can make better decisions. It shows what the organization owns (assets), what it owes (liabilities), and the owners’ share left after subtracting what it owes (equity), then reports the results in financial statements. Below, a simple business example walks you through every step, from the first transaction to the four financial statements.
Updated October 21, 2026.
Key Takeaways
- Accounting turns transaction data into information that investors, lenders, and managers can use.
- Its three core activities are identifying, recording, and communicating economic events.
- Financial accounting supports external reporting; managerial accounting supports internal decisions.
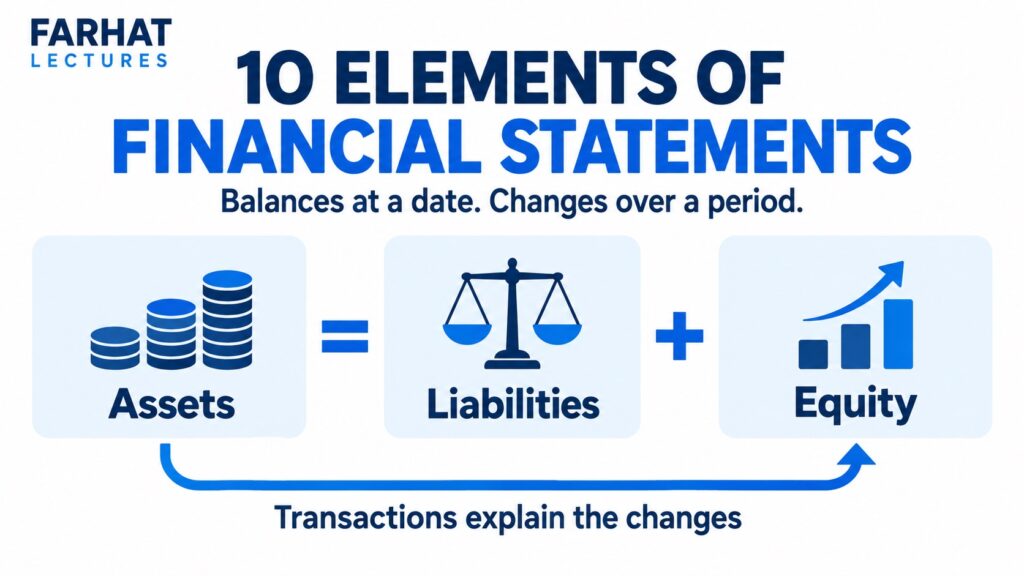
- The accounting equation is Assets = Liabilities + Equity.
- U.S. businesses follow GAAP (generally accepted accounting principles), set by the FASB. Many other countries use IFRS, issued by the IASB.
- Owner investments and loans increase cash, but neither is revenue. Profit and cash flow measure different things.
Definition of Accounting
Here’s the short version you can memorize: accounting identifies, records, and communicates the economic events of an organization to the people who use that information.
That user-focused wording echoes a 1966 definition from the American Accounting Association (AAA), which described accounting as identifying, measuring, and communicating economic information so users can make informed decisions. An older definition, written in 1941 by the American Institute of Certified Public Accountants (AICPA) Committee on Terminology, focused on recording, classifying, and summarizing transactions in money terms and interpreting the results. The newer view puts the user at the center, and it’s the framing this guide follows.
Accounting involves more than keeping a record of payments. Accountants analyze transactions, classify them into accounts, summarize the results, and explain what the information means. A business can use those results to evaluate profitability, manage resources, and meet reporting obligations.
For example, a bank considers accounting information when deciding whether to lend. A manager uses the same underlying transaction records to monitor spending and prepare a budget. Professor Farhat introduces these relationships in the Introduction to Accounting and Users of Accounting Information lesson.
Watch: What Is Accounting? Three Core Activities Explained
In this 18-minute lesson, Professor Farhat explains how accounting identifies, records, and communicates business transactions. Follow a bakery example, compare internal and external users, and see how financial accounting differs from managerial accounting.
Lesson: What Is Accounting? 3 Core Activities + Simple Examples by Farhat Lectures. Duration: 17:53. Published August 6, 2024.
What are the three core activities of accounting?
The three core activities are identifying, recording, and communicating economic events. A bakery identifies a sale as a business transaction, records the amount in its accounting records, and includes the results in reports that help users make decisions.
Explore key moments on YouTube: 2:44 — Three core activities; 4:47 — Bakery example; 11:37 — Financial vs. managerial accounting; 13:33 — External users; 16:20 — Practice question.
What Is Accounting Used For?
The overall objective is to provide useful information for decisions. The FASB (Financial Accounting Standards Board), which sets accounting standards in the United States, spells out this goal in Chapter 1 of its Conceptual Framework: financial reporting should give investors, lenders, and other creditors information that helps them decide whether to provide resources to a business. Day to day, accountants support that goal through five tasks:
- Identifying and recording: Decide which events are business transactions, then capture them using evidence such as invoices, receipts, and contracts.
- Classifying: Organize amounts into accounts such as cash, accounts payable, revenue, and rent expense.
- Summarizing: Combine transaction details into account balances and reports.
- Communicating: Present results clearly through financial statements and internal reports.
- Interpreting: Explain what the results say about performance, liquidity (the ability to pay bills as they come due), and resource use.
Wondering how five tasks fit the three core activities? Identifying comes first. Recording includes classifying and summarizing. Communicating includes interpreting, because numbers only help people once someone explains what they mean.
Users of Accounting Information
External users are outside the organization’s management. Investors assess profitability and risk; creditors assess repayment ability; regulators and tax authorities use information for oversight and compliance.
Internal users include executives, department managers, and employees who need information for their work. A production manager may compare actual material costs with a budget, while a sales manager evaluates performance by product.
Types of Accounting: Financial, Managerial, and Other Branches
Financial accounting and managerial accounting serve different reporting needs. Both rely on transaction data, but they organize and present it for different purposes.
| Feature | Financial accounting | Managerial accounting |
|---|---|---|
| Primary users | Investors, creditors, and other external users; managers also use these reports. | Managers and other internal decision-makers. |
| Purpose | Report financial position, performance, and cash flows. | Support planning, operating decisions, and performance evaluation. |
| Reporting approach | Follows a financial reporting framework, usually U.S. GAAP in the United States or IFRS (International Financial Reporting Standards) in many other countries. | Tailored to management needs; internal reports need not follow GAAP or IFRS. |
| Timing and focus | Periodic reports, mainly about completed periods, with estimates and disclosures where relevant. | Reports as needed, combining historical information, budgets, and forecasts. |
| Example | An annual income statement for investors. | A monthly budget comparison for a department manager. |
Explore the Financial Accounting course for external reporting foundations and the Managerial Accounting course for internal decision-making applications.
Other areas include:
- Cost accounting: Measures and analyzes the costs of products, services, and activities. It supports both financial reporting and management decisions. The Cost Accounting course develops these applications.
- Tax accounting: Applies tax rules to determine taxable income, prepare returns, and support tax planning and compliance. In the United States, federal tax rules come from the Internal Revenue Code and are administered by the IRS (Internal Revenue Service), so the tax treatment of a transaction can differ from its financial accounting treatment. Farhat’s Tax Courses cover these rules.
- Financial statement auditing: Involves obtaining sufficient appropriate evidence to provide reasonable assurance (a high, but not absolute, level of confidence) about whether financial statements are free of material misstatement. A misstatement is material if it could reasonably change the decisions of people who rely on the statements. That evidence supports an independent opinion on the statements. An audit does not guarantee that every amount is perfectly accurate.
Who Sets the Rules? GAAP, IFRS, and the Standard Setters
Financial accounting follows published standards, so a lender reading two companies’ reports can compare them fairly. These are the organizations you’ll hear about most:
- FASB (Financial Accounting Standards Board): Sets U.S. GAAP for public companies, private companies, and not-for-profit organizations. Its standards live in the FASB Accounting Standards Codification, which is why you’ll see references such as ASC 606, the revenue standard.
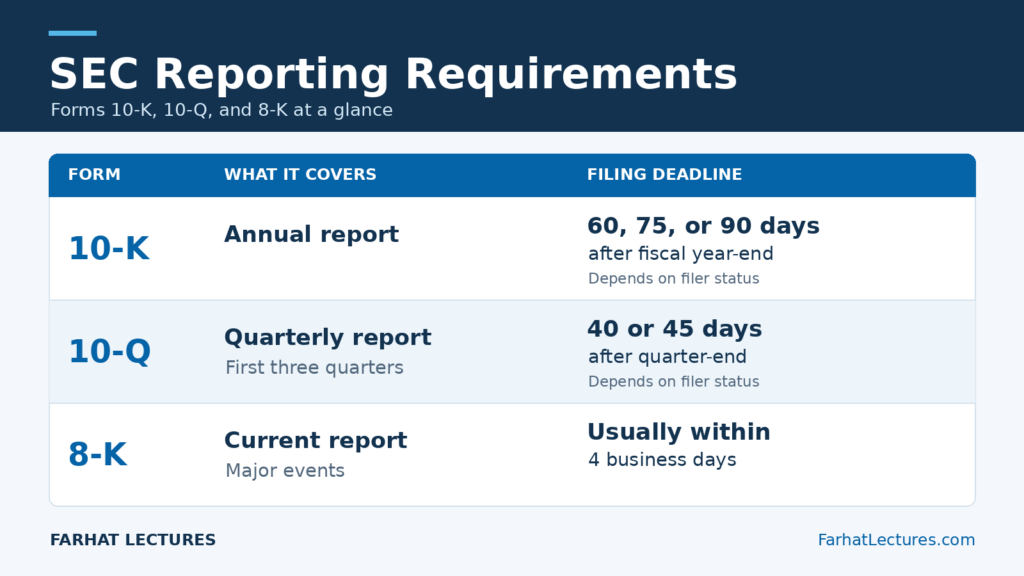
- SEC (Securities and Exchange Commission): Oversees financial reporting by public companies in the United States and recognizes the FASB as the standard setter for those companies.
- GASB (Governmental Accounting Standards Board): Sets accounting standards for state and local governments. Farhat’s Governmental and Not-for-Profit Accounting course covers this area.
- IASB (International Accounting Standards Board): Issues IFRS, which many countries outside the United States use. Farhat’s International Accounting course is a good next step if you plan to work with IFRS.
Behind U.S. GAAP sits the FASB’s Conceptual Framework, a set of concepts the board uses when it writes new standards. Read Farhat’s FASB Conceptual Framework guide for a plain-English tour, or watch the What Is GAAP and Conceptual Framework lesson.
Four Assumptions Behind the Numbers
Accountants also rely on a few basic assumptions. You’ll meet them again in your course and on exams:
- Economic entity: The business is kept separate from its owner. That’s why, in the Cedar Consulting example below, the owner’s $10,000 is recorded as owner’s capital, and the owner’s personal grocery bill never appears in the business records.
- Monetary unit: Only items that can be measured in money are recorded, using a currency such as the U.S. dollar, which accountants assume is stable in value.
- Time period: A business’s life is divided into periods, such as months, quarters, or years, so results can be reported regularly.
- Going concern: Unless there is evidence otherwise, accountants assume the business will keep operating for the foreseeable future.
Practice spotting these in the Accounting Principles lesson.
What Is the Accounting Equation?
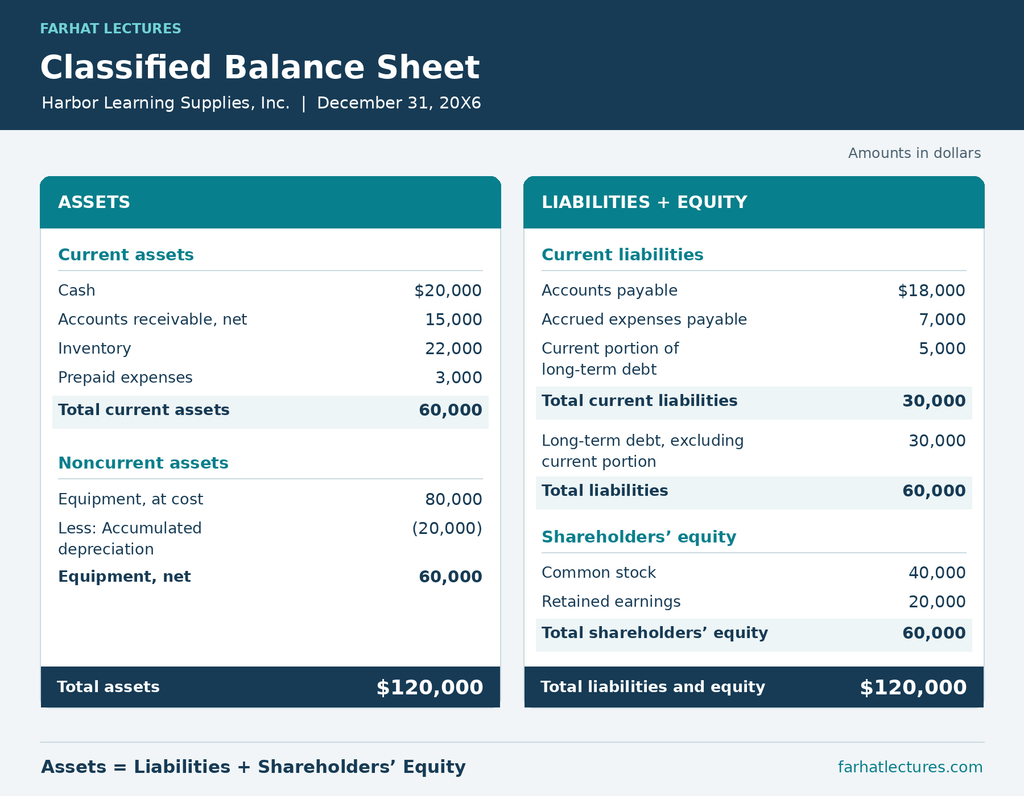
The accounting equation expresses the relationship between an entity’s resources and the claims against those resources:
- Assets: Resources the business controls that can bring it future economic benefits, such as cash, equipment, and amounts customers owe it (accounts receivable). If you’re preparing for the CPA exam, know the FASB’s current wording too: an asset is “a present right of an entity to an economic benefit.”
- Liabilities: Present obligations to transfer an economic benefit to someone else, such as bank loans and amounts owed to suppliers (accounts payable). “Present” means the obligation already exists on the balance sheet date, not one the business might take on later.
- Equity: The residual interest in assets after deducting liabilities. In plain terms, it’s the owners’ claim on what would be left, on paper, if the business used its assets to pay everything it owes. In a corporation, equity is called stockholders’ equity.
Each recorded transaction keeps the equation in balance. For example, borrowing $4,000 increases cash and the loan liability by $4,000; it does not create revenue. Continue with Farhat’s Accounting Equation lesson for further practice.
To learn all ten building blocks of financial statements, from revenue and gains to owner investments, read Farhat’s Elements of Financial Statements guide.
What Is Accounting in Practice? A Worked Example
Assume Cedar Consulting is a new sole proprietorship with no opening balances. During its first month, the owner invests $10,000 cash, the business earns and collects $2,000 for services, and it pays $500 rent for that month. Assume these are its only transactions and no adjusting entries are needed.
| Transaction | Effect on assets | Effect on liabilities | Effect on equity |
|---|---|---|---|
| Owner invests $10,000 | Cash increases $10,000. | No change. | Owner’s capital increases $10,000. |
| Business earns $2,000 cash service revenue | Cash increases $2,000. | No change. | Revenue increases equity $2,000. |
| Business pays $500 current-month rent | Cash decreases $500. | No change. | Rent expense decreases equity $500. |
| Ending balances | Cash: $11,500 | Liabilities: $0 | Owner’s equity: $11,500 |
Net income = $2,000 revenue − $500 rent expense = $1,500. The $10,000 investment is excluded because it is an owner contribution, not earnings from providing services.
Ending cash = $10,000 + $2,000 − $500 = $11,500. The equation remains balanced: $11,500 assets = $0 liabilities + $11,500 equity.
How the Transactions Are Recorded
The following journal entries show the recording step. A debit means the left side of an account; a credit means the right side. Their effects depend on the account type, and total debits must equal total credits in each entry.
| Transaction | Debit | Credit |
|---|---|---|
| Owner investment | Cash $10,000 | Owner’s Capital $10,000 |
| Services performed for cash | Cash $2,000 | Service Revenue $2,000 |
| Current-month rent paid | Rent Expense $500 | Cash $500 |
This example follows the transaction-analysis approach developed in Farhat’s Analyzing Business Transactions lesson. The business name and amounts above form an original illustration.
Financial Statements: Communicating the Results
The statements answer different questions about the same business. For Cedar Consulting, the three transactions flow into the reports as follows:
| Statement | What it explains | Cedar Consulting example |
|---|---|---|
| Income statement | Revenue, expenses, and net income or loss for a period. | $2,000 revenue − $500 expense = $1,500 net income. |
| Statement of changes in equity | Changes in owners’ interests during a period. For this sole proprietorship, it is a statement of owner’s equity. | $0 opening equity + $10,000 investment + $1,500 net income − $0 withdrawals = $11,500 ending equity. |
| Balance sheet | Assets, liabilities, and equity at a specific date. | $11,500 cash = $0 liabilities + $11,500 owner’s equity. |
| Statement of cash flows | Cash inflows and outflows from operating, investing, and financing activities during a period. | $1,500 net operating inflow + $0 investing cash flow + $10,000 financing inflow = $11,500 increase in cash. |
Financial statements also include explanatory notes. The example is deliberately simple: in practice, revenue may be earned before cash is collected, and expenses may be recognized before or after payment. Consequently, net income is not the same as cash flow. See Farhat’s Preparing Financial Statements lesson to practice connecting the reports.
Cash vs. Accrual Accounting: Why Timing Matters
As a separate illustration, suppose a tutor completes $600 of lessons in March and receives payment in April. Assume the revenue recognition requirements are met in March.
Under accrual accounting, March includes $600 of revenue and $600 of accounts receivable. When the customer pays in April, cash increases and the receivable decreases. The collection does not create revenue a second time.
Under cash basis accounting, the $600 is recorded as revenue in April, when payment arrives. This difference changes which month’s report includes the income, even though the tutor performed the same work.
A similar timing issue arises with a March electricity bill paid in April: accrual accounting recognizes the March expense and an unpaid liability, while cash basis accounting records the expense when paid. Farhat’s cash basis versus accrual discussion provides more examples. These timing differences help explain why a profitable business can still need cash to pay bills.
Watch Farhat explain cash and accrual timing (3 minutes, 41 seconds)
This segment from Professor Farhat’s special purpose frameworks lesson starts at 10:11 and ends before the modified cash basis examples at 13:52.
What Are the Steps in the Accounting Cycle?
The accounting cycle organizes the work from individual transactions through period-end reporting and closing:
- Identify and analyze transactions using supporting documents.
- Record transactions in the journal.
- Post journal entries to the general ledger.
- Prepare an unadjusted trial balance.
- Record and post adjusting entries for items such as accrued expenses, prepaid expenses, and depreciation.
- Prepare an adjusted trial balance.
- Prepare the financial statements.
- Record and post closing entries to reset temporary accounts (revenues, expenses, and owner withdrawals) to zero for the next period.
- Prepare a post-closing trial balance of the remaining permanent accounts (assets, liabilities, and owner’s capital).
A balanced trial balance confirms that total debit balances equal total credit balances. It does not establish that every transaction was recorded correctly; an omitted transaction or an entry to the wrong account can leave the totals equal.
Common Beginner Mistakes to Avoid
Watch for these five slip-ups as you start out. Catch them early and the rest of the course gets easier.
- Calling an owner investment or a bank loan revenue. Both bring in cash, but revenue comes only from providing goods or services. In the Cedar Consulting example, net income is $1,500, not $11,500.
- Treating profit and cash as the same number. A business can report a profit while customers still owe it money. That’s why the statement of cash flows exists.
- Mixing personal and business transactions. The economic entity assumption keeps the owner’s personal spending out of the business records.
- Trusting a balanced trial balance too much. A missed transaction or an entry to the wrong account can still leave debits equal to credits.
- Thinking accounting is just bookkeeping. Recording is the starting point. The real value comes from adjusting, reporting, and explaining the results.
Exam tip: When a question hands you a cash inflow, ask one thing first: did the business earn this by serving a customer? If not, it’s probably financing from an owner or a lender, not revenue.
Check Your Understanding
Answer each question before opening its explanation.
1. A business receives a $3,000 bank loan. What changes?
Cash and liabilities each increase by $3,000. Revenue and equity do not increase because the business has an obligation to repay the loan.
2. A manager requests a weekly report comparing actual spending with the budget. Which area of accounting best fits?
Managerial accounting. The report is designed for an internal planning and control decision, rather than general-purpose external reporting.
3. In the Cedar Consulting example, why is net income $1,500 instead of $11,500?
Net income includes $2,000 of service revenue less $500 of rent expense. The separate $10,000 owner investment increases capital, not revenue.
Where Accounting Leads: CPA, CMA, and EA Paths
If you’re studying accounting with a professional credential in mind, the basics on this page come back on each of the three big U.S. exams:
- CPA (Certified Public Accountant): CPAs are licensed by state boards of accountancy. Candidates pass the Uniform CPA Examination, developed by the AICPA, and meet their state’s education and experience requirements. The exam has three Core sections (AUD, FAR, and REG) plus one Discipline section you choose (BAR, ISC, or TCP). Financial statements, accrual accounting, and cash basis reporting are core FAR (Financial Accounting and Reporting) topics. Practice with the FAR Test Bank.
- CMA (Certified Management Accountant): The CMA is awarded by the IMA (Institute of Management Accountants). The exam has two parts, and Part 1 includes a section on External Financial Reporting Decisions that builds directly on the four financial statements. See the CMA Part 1 course.
- EA (Enrolled Agent): EAs are tax practitioners authorized by the IRS to represent taxpayers. Candidates pass the three-part Special Enrollment Examination (SEE), and Part 2 (Businesses) covers accounting periods and methods, including the cash and accrual methods for tax purposes.
Not sure whether your coursework qualifies you to sit for the CPA exam? Start with Farhat’s NASBA Evaluation page.
Frequently Asked Questions About Accounting
What is accounting in simple terms?
Accounting is the process of identifying, recording, and communicating a business’s economic activities. It helps users understand what the business owns and owes, how it performs, and how its cash changes.
What is the main purpose of accounting?
Its main purpose is to provide useful information for decisions. Investors and lenders evaluate financial performance and risk, while managers use accounting reports to plan and control operations.
Who uses accounting information and why?
External users include investors, creditors, regulators, and tax authorities. Internal users include managers and employees who use information to perform their responsibilities, monitor results, and make operating decisions.
What are the main types of accounting?
Financial accounting and managerial accounting are two main areas. Related areas include cost accounting, tax accounting, and auditing, each serving a different purpose.
How is accounting different from bookkeeping?
Bookkeeping focuses on maintaining organized transaction records. Accounting includes that recordkeeping and adds analysis, adjustments, financial reporting, interpretation, and the application of relevant standards.
Is accounting the same as tracking cash?
No. Accrual accounting recognizes revenue when the business earns it by delivering goods or services to a customer (U.S. GAAP calls this satisfying a performance obligation under ASC 606, the revenue standard) and recognizes expenses when they are incurred. Those dates can differ from the dates cash is received or paid. It also tracks noncash items, assets, liabilities, and equity.
What is the difference between GAAP and IFRS?
U.S. GAAP is the set of accounting standards used in the United States and issued by the FASB. IFRS (International Financial Reporting Standards) is issued by the IASB and used in many other countries. Both aim to produce useful financial statements, but some rules differ. For example, U.S. GAAP allows the LIFO (last-in, first-out) inventory method, while IFRS does not.
Who sets accounting standards?
In the United States, the FASB sets standards for businesses and not-for-profit organizations, and the GASB sets them for state and local governments. The SEC oversees financial reporting by public companies and recognizes the FASB as their standard setter. Outside the United States, many countries use IFRS from the IASB.
Why is accounting called the language of business?
Because it gives everyone the same vocabulary for describing a business in numbers. Terms like assets, revenue, and net income, and reports like the balance sheet, mean the same thing to an owner, a lender, and an investor, so they can compare results and make decisions.
What is the difference between a CPA, a CMA, and an EA?
A CPA is licensed by a state board of accountancy, and in the United States only licensed CPA firms can issue audit opinions on financial statements. CPAs also work in tax and advisory roles. A CMA, awarded by the IMA, focuses on management accounting and corporate finance inside organizations. An EA, authorized by the IRS, specializes in tax and can represent taxpayers before the IRS.
Continue Learning with Farhat Lectures
Build on this introduction in the following order:
- Accounting Equation: connect assets, liabilities, and equity.
- Analyzing Business Transactions: identify how each event changes the accounts.
- Preparing Financial Statements: turn account balances into connected reports.
- Elements of Financial Statements: learn the ten building blocks behind every statement.
- Intermediate Accounting: go deeper into GAAP once the basics feel solid.
About the Educator

Professor Mansour Farhat, CPA, CIA, DBA, MAcc, is the founder of Farhat Lectures and an accounting educator. He teaches accounting students and CPA and CMA candidates through video lessons, worked examples, and practice questions. He wrote this guide, including the original Cedar Consulting example and knowledge check, and the linked lessons go deeper on each concept introduced here.

Responses