
Margin of Safety: Formula, Calculation, and Examples

Margin of safety is the amount by which actual or budgeted sales exceed break-even sales. It tells you how far sales can fall before operating profit drops to zero. The formula is simple: margin of safety = actual or budgeted sales − break-even sales. Divide the result by actual or budgeted sales to express it as a percentage.
For example, if a business budgets $20,000 in sales and breaks even at $12,000, its margin of safety is $8,000, or 40% of budgeted sales. The calculation assumes selling prices, variable cost per unit, and total fixed costs stay the same. You can show it in dollars, units, or as a percentage.
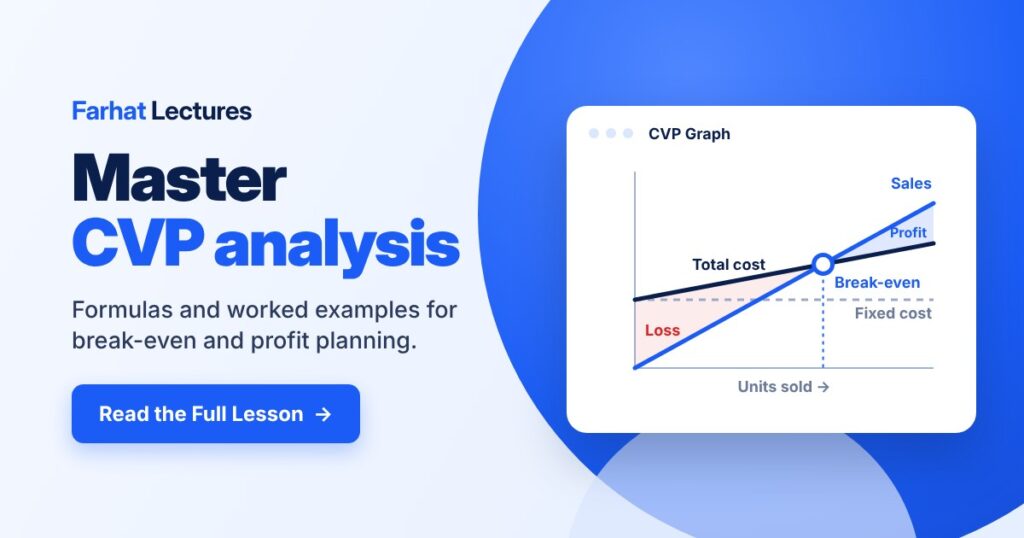
This lesson explains the formulas, works through two restaurant scenarios, and shows how to interpret the results. Margin of safety is part of cost-volume-profit (CVP) analysis, which connects sales volume, costs, and operating profit.
Quick note: investors use the same term differently. In value investing, margin of safety is the gap between a stock’s estimated intrinsic value and its market price, an idea associated with Benjamin Graham. This lesson covers the managerial accounting meaning, which is the one tested on the CPA and CMA exams.
Updated October 21, 2026.
What Is the Margin of Safety Formula?
Margin of safety in dollars = Actual or budgeted sales dollars − Break-even sales dollars
Margin of safety percentage = (Margin of safety in dollars ÷ Actual or budgeted sales dollars) × 100%
Margin of safety in units = Actual or budgeted units sold − Break-even units
Stick with one sales figure from start to finish. If you start with budgeted sales, divide by budgeted sales when you calculate the percentage. And make sure your sales and costs cover the same period, such as the same month.
For a single product sold at a constant price, you can also divide the margin of safety in dollars by the selling price per unit to find the margin in units.
Watch Professor Farhat Explain Margin of Safety
Prefer to watch first? In this 7.5-minute lesson, Professor Farhat explains margin of safety in dollars and as a percentage. Then come back and work through the examples below. You can also watch the margin of safety lesson on YouTube.
How Do You Calculate Break-Even Sales?
Break-even is the sales level at which total contribution margin exactly covers fixed operating costs. Operating profit is zero. Contribution margin is sales revenue minus variable operating costs; it is not the same as profit.
- Contribution margin per unit = Selling price per unit − Variable cost per unit.
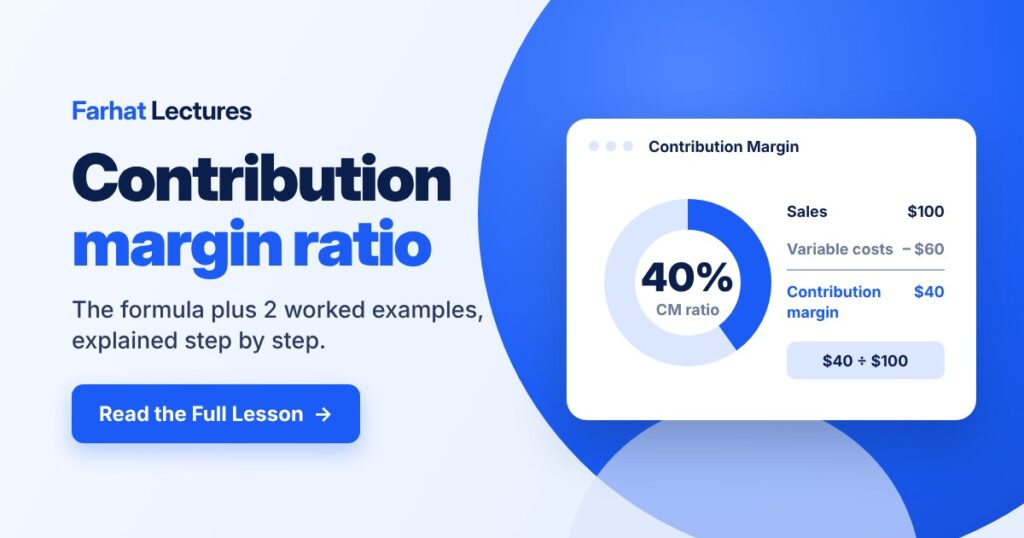
- Contribution margin ratio = Contribution margin per unit ÷ Selling price per unit.
- Break-even units = Fixed costs ÷ Contribution margin per unit.
- Break-even sales dollars = Fixed costs ÷ Contribution margin ratio.
When you divide by the ratio, enter it as a decimal: use 0.50 for 50%. Also, each unit must sell for more than its variable cost. If the contribution margin isn’t positive, the business can never cover its fixed costs, no matter how much it sells. Review the contribution margin ratio formula and examples if this step needs clarification.
Example 1: Tasty Bites at Break-Even
We’ll start with a budget that lands exactly on break-even, so you can see what zero cushion looks like. Example 2 then shows a positive margin of safety.
Assume Tasty Bites, a hypothetical restaurant, has the following monthly budget. Fixed costs include rent and fixed salaries. Any variable portions of utilities and labor are included in the variable cost per meal.
| Item | Amount |
|---|---|
| Fixed operating costs | $6,000 |
| Selling price per meal | $20 |
| Variable cost per meal | $10 |
| Budgeted sales revenue | $12,000 |
Step 1: Find Contribution Margin
Contribution margin per meal = $20 − $10 = $10.
Contribution margin ratio = $10 ÷ $20 = 0.50, or 50%.
Step 2: Calculate Break-Even Units and Dollars
Break-even units = $6,000 ÷ $10 = 600 meals.
Break-even sales dollars = $6,000 ÷ 0.50 = $12,000. Check: 600 meals × $20 = $12,000.
Step 3: Calculate the Margin of Safety
Margin of safety in dollars = $12,000 − $12,000 = $0.
Margin of safety percentage = ($0 ÷ $12,000) × 100% = 0%.
Tasty Bites expects to sell exactly 600 meals, so its margin of safety in units is also zero. The restaurant is at break-even and has no cushion for a sales decline. Notice that $6,000 is fixed cost, not break-even sales revenue. Subtracting fixed costs directly from sales would give the wrong margin of safety.
Example 2: A Positive Margin of Safety
Now assume Tasty Bites budgets $20,000 in monthly sales. Selling price, variable cost per meal, and fixed costs remain unchanged, so break-even sales are still $12,000.
- Budgeted units = $20,000 ÷ $20 = 1,000 meals.
- Margin of safety in dollars = $20,000 − $12,000 = $8,000.
- Margin of safety percentage = ($8,000 ÷ $20,000) × 100% = 40%.
- Margin of safety in units = 1,000 − 600 = 400 meals.
Sales can fall by $8,000, or 40% of the budgeted amount, before the restaurant reaches break-even. At exactly $12,000 in sales, operating profit is zero; below that amount, the restaurant incurs an operating loss under these assumptions.
How the $20,000 sales budget is divided
Example 3: Margin of Safety With Two Products
Most businesses sell more than one product. When that happens, you use a weighted-average contribution margin, which is the average contribution margin per unit, weighted by how many units of each product you expect to sell (the sales mix).
Assume Summit Gear, a hypothetical outdoor retailer, sells two backpacks. Monthly fixed costs are $48,000, and the company expects 60% of units sold to be premium backpacks and 40% to be basic backpacks.
| Item | Premium | Basic |
|---|---|---|
| Selling price per unit | $50 | $30 |
| Variable cost per unit | $30 | $20 |
| Contribution margin per unit | $20 | $10 |
| Sales mix (units) | 60% | 40% |
Step 1: Find the Weighted-Average Contribution Margin
Weighted-average contribution margin per unit = ($20 × 0.60) + ($10 × 0.40) = $12 + $4 = $16.
Step 2: Calculate Break-Even Units and Dollars
Break-even units = $48,000 ÷ $16 = 3,000 backpacks, which is 1,800 premium and 1,200 basic.
Break-even sales dollars = (1,800 × $50) + (1,200 × $30) = $90,000 + $36,000 = $126,000.
Step 3: Calculate the Margin of Safety
Summit Gear budgets 4,000 backpacks: 2,400 premium and 1,600 basic. Budgeted sales = (2,400 × $50) + (1,600 × $30) = $120,000 + $48,000 = $168,000.
- Margin of safety in dollars = $168,000 − $126,000 = $42,000.
- Margin of safety percentage = ($42,000 ÷ $168,000) × 100% = 25%.
- Margin of safety in units = 4,000 − 3,000 = 1,000 backpacks, in the same 60/40 mix.
One catch: these answers hold only if the 60/40 mix holds. If customers shift toward the lower-margin basic backpack, break-even sales rise and the margin of safety shrinks.
What Does a High or Low Margin of Safety Mean?
A larger positive percentage indicates a greater cushion against declining sales. A small positive percentage means that a relatively small sales decline could eliminate operating profit. There is no single percentage that is appropriate for every business; sales volatility, seasonality, cost structure, and the reliability of the budget all matter.
A negative margin means sales are below break-even. For example, $10,000 of sales against $12,000 of break-even sales gives a margin of −$2,000, or −20%. If those are actual sales, the business has an operating loss under the model. If they are budgeted sales, it projects an operating loss. A negative margin is a shortfall, not an available cushion.
Managers can improve the margin by increasing profitable sales or reducing the break-even level. Changes to prices, variable costs, or fixed costs require a fresh calculation. A positive margin alone does not establish adequate cash flow, solvency, or overall financial health.
To see how price, cost, and volume changes play out in practice, work through these five CVP analysis examples.
Margin of Safety Versus Profit Margin
Margin of safety measures the sales cushion above break-even. Operating profit margin measures operating profit as a percentage of sales.
In Example 2, operating profit = ($20,000 × 0.50) − $6,000 = $4,000. Operating profit margin = $4,000 ÷ $20,000 = 20%. This differs from the 40% margin of safety.
A useful cross-check is Operating profit = Margin of safety in dollars × Contribution margin ratio. Here, $8,000 × 0.50 = $4,000. This relationship uses the same CVP assumptions and cost definitions. To plan for a specific profit amount, see the target profit formula and worked examples.
The same idea works in percentages: operating profit margin = margin of safety percentage × contribution margin ratio. In Example 2, 40% × 0.50 = 20%, which matches the operating profit margin above.
How Margin of Safety Connects to Operating Leverage
Margin of safety has a handy partner: the degree of operating leverage (DOL). DOL measures how sensitive operating profit is to a change in sales. You calculate it as contribution margin ÷ operating profit.
Here’s a shortcut that saves time on exam questions: DOL = 1 ÷ margin of safety percentage, and margin of safety percentage = 1 ÷ DOL. The shortcut works when operating profit is positive.
Let’s check it with Example 2. Total contribution margin is $20,000 × 0.50 = $10,000, and operating profit is $4,000. DOL = $10,000 ÷ $4,000 = 2.5. Now use the shortcut: 1 ÷ 0.40 = 2.5. Same answer.
What does 2.5 mean? A 10% change in sales causes a 25% change in operating profit. If sales rise 10% to $22,000, contribution margin becomes $11,000 and operating profit becomes $5,000, which is 25% higher than $4,000.
The takeaway: a small margin of safety means high operating leverage, so profit swings hard when sales move. Learn more in our degree of operating leverage lesson.
Where Margin of Safety Shows Up on the CPA and CMA Exams
Margin of safety is part of break-even and cost-volume-profit (CVP) analysis, and it appears on both the CPA and CMA exams.
- CPA Exam, BAR section: The AICPA’s Business Analysis and Reporting (BAR) blueprint includes preparing and interpreting break-even analysis in Area I, Business Analysis, which makes up 40% to 50% of the BAR exam.
- CMA Exam, Part 2: The CMA content specification outlines from the ICMA, the certification arm of the Institute of Management Accountants (IMA), place cost/volume/profit analysis, including break-even analysis and multiple-product analysis, in Part 2, Section C, Business Decision Analysis. That section carries 25% of the Part 2 exam.
Watch for three common exam traps:
- Dividing by break-even sales instead of actual or budgeted sales.
- Treating fixed costs as if they were break-even sales.
- Confusing the margin of safety percentage with the profit margin.
Assumptions and Common Mistakes
- Keep prices and costs consistent. Selling price and variable cost per unit remain constant within each scenario; total fixed costs remain constant within the relevant range.
- Separate mixed costs. Identify their fixed and variable portions before calculating break-even.
- Keep the sales mix stable. For multiple products, use an appropriate weighted-average contribution margin. Recalculate if the mix changes.
- Match units with units and dollars with dollars. Dividing fixed costs by contribution margin per unit gives units, not sales dollars.
- Use the correct denominator. Divide by actual or budgeted sales, not break-even sales, when calculating the margin of safety percentage.
- Distinguish forecasts from results. Budgeted sales do not guarantee actual demand or profitability.
Practice: Calculate the Sales Cushion
A company has budgeted sales of $90,000 and break-even sales of $60,000 for the same month. Calculate its margin of safety in dollars and as a percentage. Assume prices and costs remain unchanged.
Show the worked solution
Margin of safety in dollars = $90,000 − $60,000 = $30,000.
Margin of safety percentage = ($30,000 ÷ $90,000) × 100% = 33.33%, rounded to two decimal places.
Sales can fall by $30,000, or approximately one-third of the budget, before operating profit reaches zero. Dividing $30,000 by $60,000 would incorrectly use break-even sales as the denominator.
Exam-style question: A company’s degree of operating leverage is 4. What is its margin of safety percentage?
A. 4%
B. 25%
C. 40%
D. 400%
Answer: B. Margin of safety percentage = 1 ÷ DOL = 1 ÷ 4 = 25%.
Key Takeaways
- Margin of safety = actual or budgeted sales − break-even sales.
- Margin of safety percentage = margin of safety ÷ actual or budgeted sales. Never divide by break-even sales.
- Find break-even first: fixed costs ÷ contribution margin ratio gives break-even dollars, and fixed costs ÷ contribution margin per unit gives break-even units.
- A negative margin means sales are below break-even, so the business has, or projects, an operating loss.
- Operating profit = margin of safety in dollars × contribution margin ratio.
- Degree of operating leverage = 1 ÷ margin of safety percentage, when operating profit is positive.
Frequently Asked Questions
Can the margin of safety be negative?
Yes. It turns negative when actual or budgeted sales fall below break-even sales. With actual sales, a negative margin means the business is running an operating loss. With budgeted sales, it means the plan projects an operating loss.
Is a 40% margin of safety the same as a 40% profit margin?
No. It means sales can decline by 40% before reaching break-even, assuming unchanged prices and costs. Profit margin depends on the profit amount relative to sales.
Can I calculate the percentage using units?
Yes, for a single product with a constant selling price: divide the margin of safety in units by actual or budgeted units sold and multiply by 100%. In Example 2, 400 ÷ 1,000 × 100% = 40%.
What is a good margin of safety?
There is no universal benchmark. Compare the cushion with the business’s likely sales fluctuations, cost commitments, and planning assumptions. A larger positive percentage provides more room for a sales decline under comparable conditions.
What is the difference between margin of safety in accounting and in investing?
In managerial accounting, margin of safety compares sales with break-even sales. In value investing, it compares a stock’s estimated intrinsic value with its market price, an idea associated with Benjamin Graham. The CPA and CMA exams test the accounting meaning.
How is margin of safety related to operating leverage?
They are reciprocals when operating profit is positive: degree of operating leverage = 1 ÷ margin of safety percentage. A 40% margin of safety means a DOL of 2.5, so a 10% change in sales changes operating profit by 25%.
How do you find the margin of safety for more than one product?
Use a weighted-average contribution margin based on the expected sales mix to find break-even, then subtract break-even sales from actual or budgeted sales. In Example 3, $168,000 − $126,000 = $42,000, or 25%. Recalculate if the mix changes.
Continue Learning with Farhat Lectures
Want more practice with break-even and margin of safety? Build your foundation in the Managerial Accounting course, or use the BAR and CMA Part 2 resources below if you’re preparing for an exam. Not sure yet? Start with the free sample course. No registration required.
About the author: Professor Mansour Farhat, DBA, CPA, CIA, MAcc, is an accounting educator and the founder of Farhat Lectures. His lessons support college accounting students and professional exam candidates. Learn more about Professor Farhat.
Responses