Target Profit Formula: 2 Examples & Interactive Practice
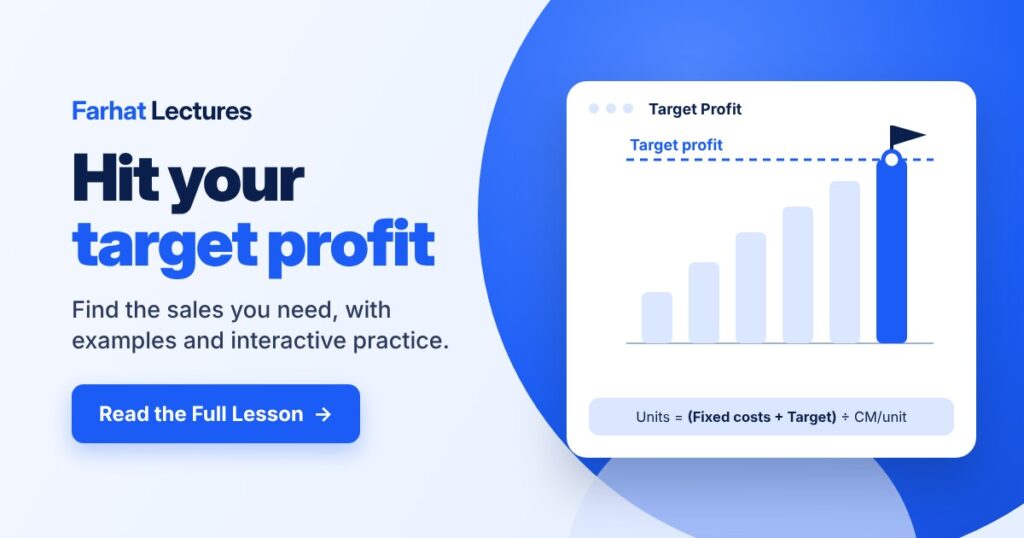
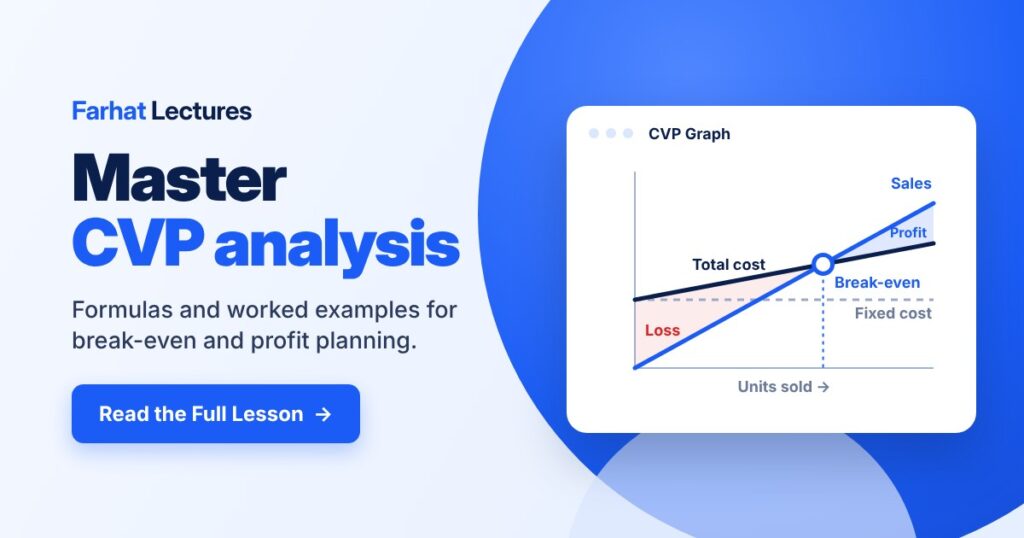
The target profit formula tells you how many units—or how much sales revenue—you need to earn a desired profit. Required unit sales = (Fixed costs + Target profit) ÷ Contribution margin per unit. This is an extension of cost-volume-profit (CVP) and break-even analysis.
For sales dollars: Required sales revenue = (Fixed costs + Target profit) ÷ Contribution margin ratio. Use a before-tax profit target in these formulas; convert an after-tax target first, as shown below.
Learn the target profit formula through two worked examples, then test your understanding with an interactive exercise covering contribution margin, break-even sales, and target profit.
Target Profit Formula: Quick Reference
| What to calculate | Formula |
|---|---|
| Units for a target operating profit | (Fixed costs + Target operating profit) ÷ Contribution margin per unit |
| Sales dollars for a target operating profit | (Fixed costs + Target operating profit) ÷ Contribution margin ratio |
| Break-even units | Fixed costs ÷ Contribution margin per unit |
| Break-even sales dollars | Fixed costs ÷ Contribution margin ratio |
| Pretax target from an after-tax goal | After-tax profit target ÷ (1 − Tax rate) |
Contribution margin per unit equals selling price minus variable cost per unit. Enter the contribution margin ratio and tax rate as decimals. For the simplified after-tax calculation, assume no interest or other nonoperating items.
Understanding the Components of Target Profit Analysis
- Sales: Units sold × selling price per unit. Adam’s selling price is $500 per tablet.
- Variable expenses: Costs that change in total with sales volume. Adam incurs $300 per tablet; at 900 tablets, total variable expenses are $270,000.
- Contribution margin: Sales minus variable expenses. Each tablet contributes $200 toward fixed expenses and then profit. Contribution margin is not the same as gross profit.
- Fixed expenses: Costs that remain constant in total within the relevant range and time period. Adam’s monthly fixed expenses are $80,000.
Target Profit Formula in Units and Sales Dollars
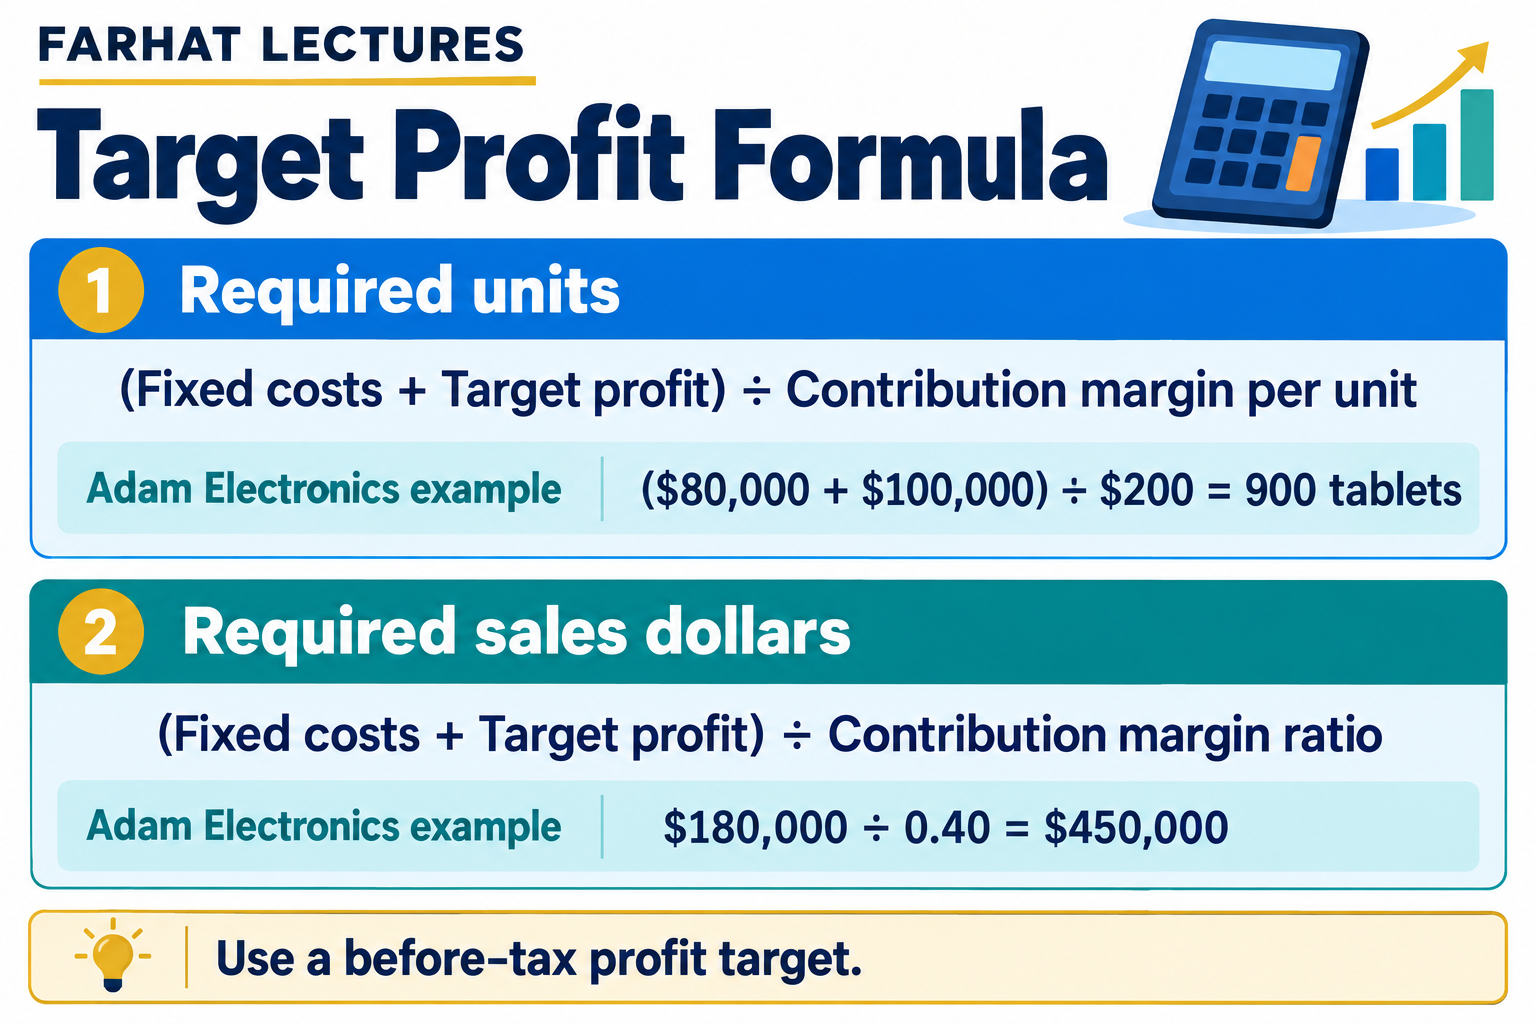
Start with the CVP equation: Operating profit = (Selling price per unit − Variable cost per unit) × Units sold − Fixed costs. Rearranging it gives the target profit analysis formula:
Required unit sales = (Fixed costs + Target operating profit) ÷ Contribution margin per unit.
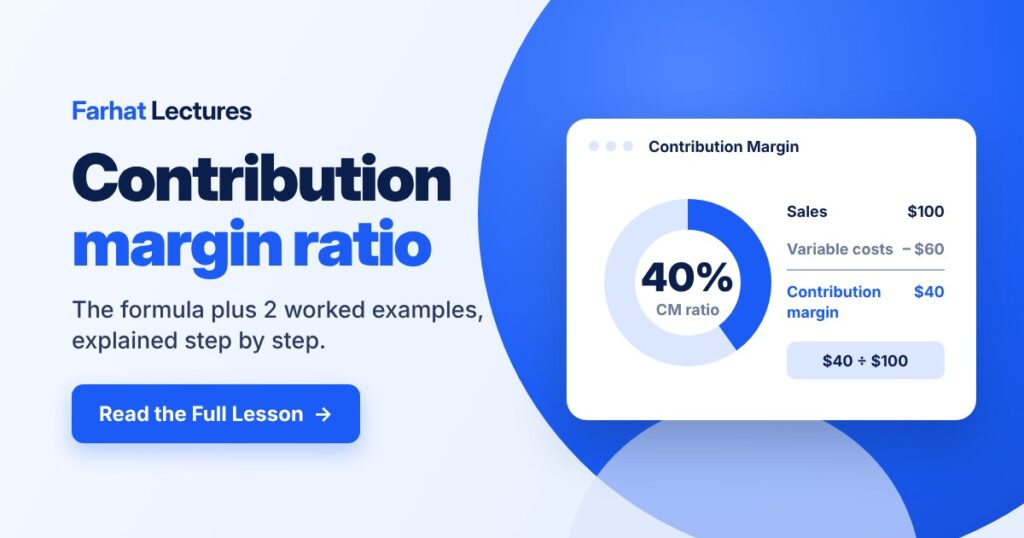
When the question asks for sales dollars, divide by the contribution margin ratio instead. Contribution margin ratio = Contribution margin per unit ÷ Selling price per unit. Use the ratio as a decimal: 40% = 0.40.
Required sales revenue = (Fixed costs + Target operating profit) ÷ Contribution margin ratio. For Adam: $180,000 ÷ 0.40 = $450,000.
Dividing only the $100,000 profit target by 40% gives $250,000 of sales, which is insufficient. At that sales level, contribution margin is $100,000 and operating profit is only $20,000 after the $80,000 fixed costs. Always include fixed costs in the numerator.
Worked Example: How Many Tablets Must Adam Sell?
Adam Electronics sells tablets for $500 each, incurs $300 of variable costs per tablet, and has $80,000 in monthly fixed costs. It wants to earn $100,000 in monthly operating profit before tax.
- Find contribution margin: $500 − $300 = $200 per tablet. The contribution margin ratio is $200 ÷ $500 = 40%.
- Calculate required units: ($80,000 + $100,000) ÷ $200 = 900 tablets.
- Calculate required sales: ($80,000 + $100,000) ÷ 0.40 = $450,000. This also equals 900 tablets × $500.
Check the answer: $450,000 sales − $270,000 variable costs − $80,000 fixed costs = $100,000 operating profit. The sales must cover both fixed costs and the desired profit after variable costs have been paid.
Break-Even vs. Target Profit
Break-even analysis uses the same formulas with a target profit of zero. Adam breaks even at $80,000 ÷ $200 = 400 tablets, or $80,000 ÷ 0.40 = $200,000 in sales.
At 400 tablets, sales of $200,000 minus variable expenses of $120,000 leave $80,000 of contribution margin—exactly enough to cover fixed expenses. To move from break-even to $100,000 of operating profit, Adam needs another 500 tablets: $100,000 ÷ $200 = 500.
After-Tax Target Profit Formula with Example
If the goal is profit after income taxes, first calculate the required pretax profit: Pretax profit target = After-tax profit target ÷ (1 − Tax rate). The tax rate here is hypothetical, and the simplified example assumes no interest or other nonoperating items.
Suppose Adam wants to keep $100,000 after tax and the assumed tax rate is 20%. The required pretax profit is $100,000 ÷ (1 − 0.20) = $125,000. This is pretax profit, not sales revenue and not gross profit.
- Required units: [$80,000 + ($100,000 ÷ 0.80)] ÷ $200 = 1,025 tablets.
- Required sales dollars: [$80,000 + ($100,000 ÷ 0.80)] ÷ 0.40 = $512,500.
| Income statement item | Amount |
|---|---|
| Sales: 1,025 × $500 | $512,500 |
| Less variable expenses: 1,025 × $300 | ($307,500) |
| Contribution margin | $205,000 |
| Less fixed expenses | ($80,000) |
| Pretax profit | $125,000 |
| Less income tax: $125,000 × 20% | ($25,000) |
| After-tax profit | $100,000 |
Adam therefore needs 125 more tablets to earn $100,000 after tax than it needs to earn $100,000 before tax. The extra contribution margin covers the $25,000 tax expense in this example.
Watch: Target Profit Analysis and CVP
In this Farhat lecture, follow the same Adam Electronics example, calculate target sales in units and dollars, and then adjust the profit target for income taxes.
Jump to a worked example: 3:21 — before-tax target profit · 7:40 — after-tax target profit · 11:37 — practice question.
Tips for Using the Target Profit Formula
- Round required units up. If the result is 900.2 whole products, sell at least 901 to meet the target.
- Match the denominator to the question. Use contribution margin per unit for units and the contribution margin ratio for sales dollars.
- Keep the time period consistent. Monthly fixed costs must be paired with a monthly profit target.
- Check the assumptions. Selling price and variable cost per unit are constant, fixed costs stay constant within the relevant range, and unit contribution margin is positive. For multiple products, use a consistent sales mix and an appropriate weighted-average contribution margin.
Target Profit Formula FAQs
Why do we add fixed costs to the profit target?
Contribution margin must first cover fixed costs. Only the amount remaining becomes operating profit. Adding fixed costs to the desired profit identifies the total contribution margin the required sales must generate.
Should I use contribution margin or gross profit?
Use contribution margin. It subtracts all variable operating costs from sales. Gross profit subtracts cost of goods sold and can include a different mix of fixed and variable costs, so it is not interchangeable with contribution margin.
When should I round required unit sales up?
Round up when products must be sold in whole units and the calculation produces a fraction. For example, a requirement of 900.2 units means at least 901 units. Rounding down would leave profit below the target.
How do income taxes affect the target profit formula?
Convert the after-tax goal to a pretax target by dividing by one minus the assumed tax rate. In the simplified Adam example, $100,000 ÷ 0.80 = $125,000. Add fixed costs to that pretax target before dividing by the appropriate contribution margin measure.
Can I use the formula for more than one product?
Yes, with a consistent sales mix and an appropriate weighted-average contribution margin. If the mix changes, recalculate the required sales because different products can contribute different amounts toward fixed costs and profit.
About the Author
Professor Mansour Farhat, DBA, CPA, CIA, MAcc, is the founder of Farhat Lectures. His accounting lessons combine explanations, worked examples, and practice to support college students and professional exam candidates.
Last updated: October 20, 2026.
For additional accounting instruction and practice, explore the Farhat Lectures Managerial Accounting course or try the free sample course.
Responses