
Treasury Stock Journal Entries: Purchase and Reissue Under the Cost Method

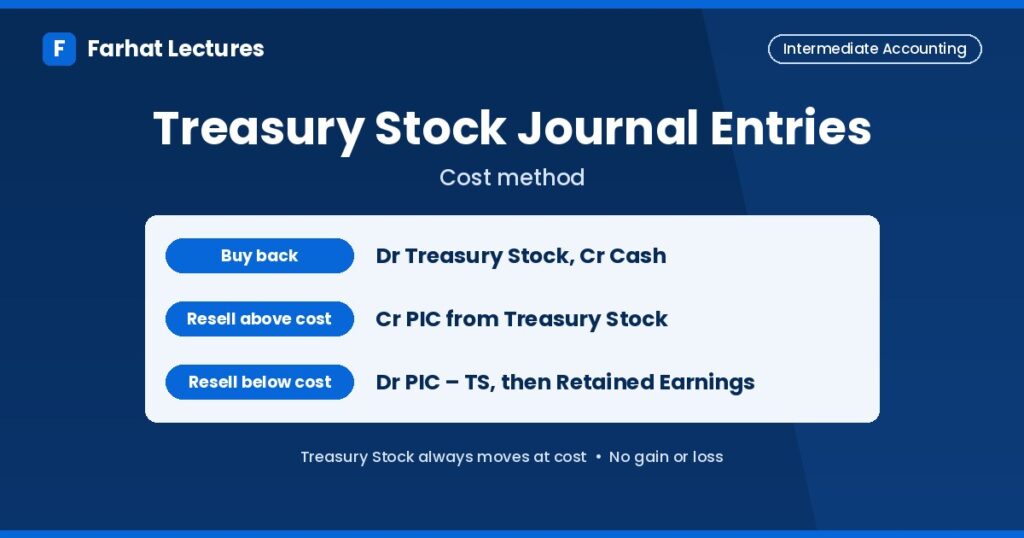
Under the cost method, treasury stock journal entries record shares at the price the company paid. To buy back shares, debit Treasury Stock and credit Cash. To resell them, credit Treasury Stock at cost. Any excess goes to Paid-in Capital from Treasury Stock. Any shortfall reduces that account first, then Retained Earnings. No gain or loss is ever recorded.
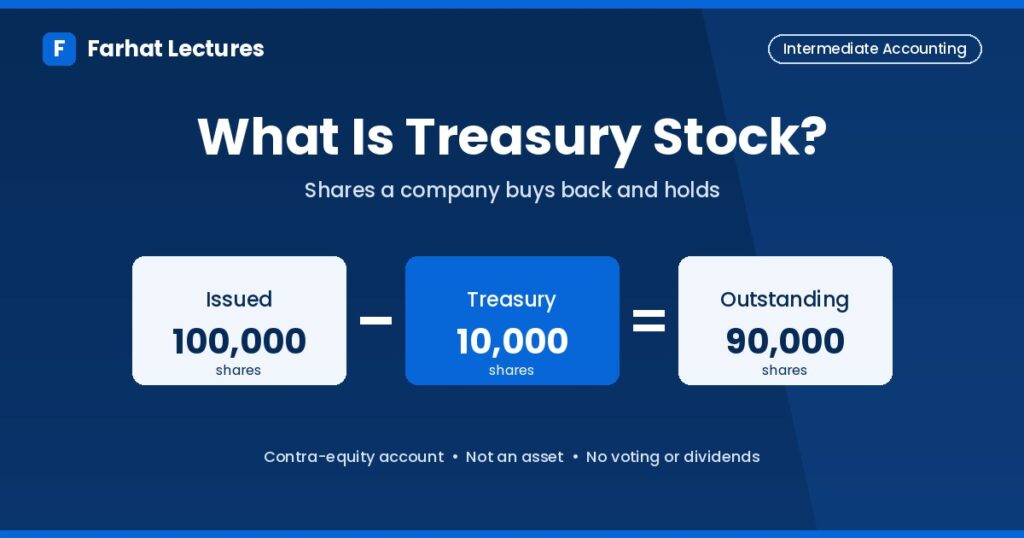
Treasury stock is a company’s own stock that it issued, bought back, and has not retired. It is a contra-equity account, which means it reduces total stockholders’ equity, and it is never reported as an asset. The rules come from FASB ASC 505-30, and you will see these entries in intermediate accounting and in the equity questions of the CPA exam’s FAR section. The tricky part is the resale below cost, because students often record a loss that should never appear on the income statement.
If you need the background first, start with What Is Treasury Stock? This lesson focuses on the entries, using one hypothetical company from start to finish.
Watch: Treasury Stock Example with Loss
In this 9-minute video, Professor Farhat works through a treasury stock example that includes a resale below cost. The video title says ‘loss,’ but as you will see in Entries 4 and 5 below, that shortfall never reaches the income statement. It reduces Paid-in Capital from Treasury Stock first, then Retained Earnings.
Treasury stock journal entries at a glance
| Transaction | Debit | Credit |
|---|---|---|
| Buy back shares | Treasury Stock (cost) | Cash |
| Reissue at cost | Cash | Treasury Stock (cost) |
| Reissue above cost | Cash | Treasury Stock (cost); Paid-in Capital from Treasury Stock (excess) |
| Reissue below cost | Cash; Paid-in Capital from Treasury Stock (up to its balance); Retained Earnings (any remainder) | Treasury Stock (cost) |
Under the cost method, Common Stock and Paid-in Capital in Excess of Par are never touched in these entries, because the number of issued shares does not change.
Entry 1: Buying back shares
Crestview Inc. (hypothetical) has 40,000 shares of $1 par common stock issued, originally sold at $8 per share. Its equity is Common Stock $40,000, Paid-in Capital in Excess of Par $280,000, and Retained Earnings $200,000.
On February 1, Crestview buys back 5,000 shares at $12 per share.
| Account | Debit | Credit |
|---|---|---|
| Treasury Stock (5,000 × $12) | 60,000 | |
| Cash | 60,000 |
The original $8 issue price plays no part. Every share in the treasury now carries a cost of $12, and that is the amount Crestview will credit each time one is resold.
Entry 2: Reissue at cost
On March 15, Crestview resells 1,000 treasury shares at $12, exactly what it paid.
| Account | Debit | Credit |
|---|---|---|
| Cash (1,000 × $12) | 12,000 | |
| Treasury Stock (1,000 × $12) | 12,000 |
Entry 3: Reissue above cost
On May 10, Crestview resells another 1,000 shares at $16. The $4 per share excess over cost is credited to Paid-in Capital from Treasury Stock, not to a gain account.
| Account | Debit | Credit |
|---|---|---|
| Cash (1,000 × $16) | 16,000 | |
| Treasury Stock (1,000 × $12) | 12,000 | |
| Paid-in Capital from Treasury Stock | 4,000 |
Two reasons explain why no gain is recorded. Gains arise from selling assets, and treasury stock is not an asset. And a company should not report income from transactions with its own stockholders.
Entry 4: Reissue below cost
On August 20, Crestview resells 1,000 shares at $9. The $3 per share shortfall is debited to Paid-in Capital from Treasury Stock, which has a $4,000 credit balance from May.
| Account | Debit | Credit |
|---|---|---|
| Cash (1,000 × $9) | 9,000 | |
| Paid-in Capital from Treasury Stock | 3,000 | |
| Treasury Stock (1,000 × $12) | 12,000 |
Paid-in Capital from Treasury Stock now has a $1,000 credit balance ($4,000 − $3,000).
Entry 5: When retained earnings absorbs the difference
On October 5, Crestview resells 1,000 more shares at $7. The shortfall is $5,000 ($12,000 cost − $7,000 cash), but only $1,000 remains in Paid-in Capital from Treasury Stock. That balance is used first, and the remaining $4,000 is debited to Retained Earnings.
| Account | Debit | Credit |
|---|---|---|
| Cash (1,000 × $7) | 7,000 | |
| Paid-in Capital from Treasury Stock | 1,000 | |
| Retained Earnings | 4,000 | |
| Treasury Stock (1,000 × $12) | 12,000 |
Where this rule comes from: FASB ASC 505-30-30-10 says gains on sales of treasury stock are credited to additional paid-in capital. Losses can be charged to additional paid-in capital only up to earlier net gains from sales or retirements of the same class of stock, and any remaining amount goes to retained earnings. In textbook problems, that paid-in capital balance is usually Paid-in Capital from Treasury Stock.
Here is how the Treasury Stock account moved through the year. Each resale removed exactly $12,000, the cost of 1,000 shares.
| Date | Transaction | Debit | Credit | Balance |
|---|---|---|---|---|
| Feb 1 | Buy 5,000 shares at $12 | 60,000 | 60,000 | |
| Mar 15 | Resell 1,000 at $12 | 12,000 | 48,000 | |
| May 10 | Resell 1,000 at $16 | 12,000 | 36,000 | |
| Aug 20 | Resell 1,000 at $9 | 12,000 | 24,000 | |
| Oct 5 | Resell 1,000 at $7 | 12,000 | 12,000 |
What if treasury shares were bought at different prices?
Crestview bought all its treasury shares in one purchase, so every share cost $12. Real companies often buy back shares several times at different prices. When that happens, the company picks a cost flow assumption, such as specific identification, first-in, first-out (FIFO), or average cost, and uses it consistently.
Example: a company buys 1,000 treasury shares at $10 and later buys 1,000 more at $14. It then resells 500 shares at $15, so Cash is debited $7,500.
- FIFO: the 500 shares come from the $10 lot. Credit Treasury Stock $5,000 (500 × $10) and Paid-in Capital from Treasury Stock $2,500 ($7,500 − $5,000).
- Average cost: the average cost is $12 ($24,000 ÷ 2,000 shares). Credit Treasury Stock $6,000 (500 × $12) and Paid-in Capital from Treasury Stock $1,500 ($7,500 − $6,000).
Either way, the excess goes to paid-in capital, never to a gain.
The equity section afterward
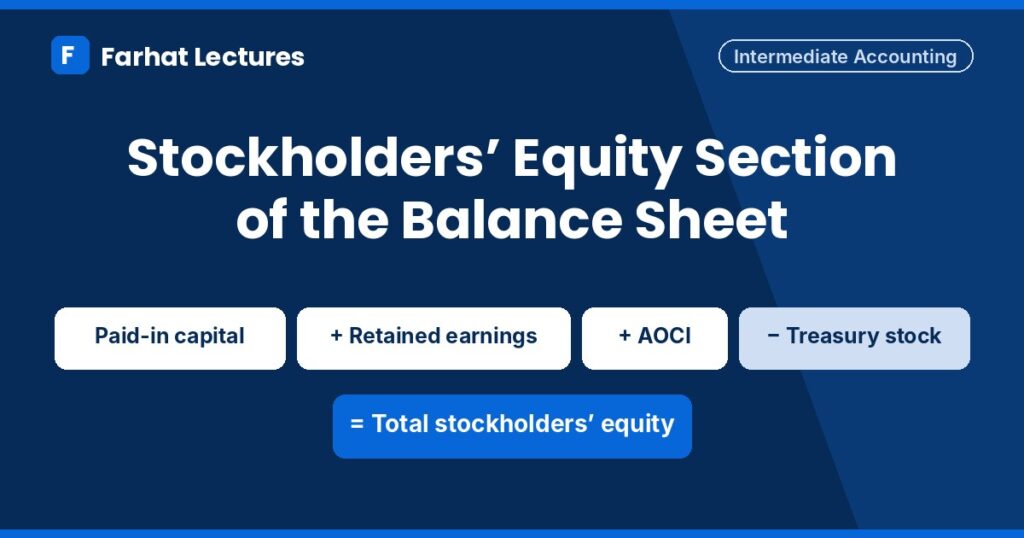
Ignoring net income for the year, here is Crestview’s stockholders’ equity section after these transactions:
| Stockholders’ equity | Amount |
|---|---|
| Common stock, $1 par, 40,000 shares issued, 39,000 outstanding | $40,000 |
| Paid-in capital in excess of par | 280,000 |
| Paid-in capital from treasury stock | 0 |
| Total paid-in capital | 320,000 |
| Retained earnings ($200,000 − $4,000) | 196,000 |
| Less: Treasury stock (1,000 shares at cost) | (12,000) |
| Total stockholders’ equity | $504,000 |
Check: equity started at $520,000. The buyback took out $60,000, and the four resales brought in $44,000 ($12,000 + $16,000 + $9,000 + $7,000), so equity is $520,000 − $60,000 + $44,000 = $504,000. If Crestview later cancels the last 1,000 shares instead of reselling them, see Retirement of Treasury Stock.
You would also see each of these transactions in the treasury stock column of Crestview’s statement of stockholders’ equity.
How is the par value method different?
Everything above uses the cost method. U.S. GAAP also allows the par value method, which treats a buyback much like retiring the shares on the spot.
Under the par value method, Crestview’s February 1 buyback of 5,000 shares at $12 would look like this:
| Account | Debit | Credit |
|---|---|---|
| Treasury Stock (5,000 × $1 par) | 5,000 | |
| Paid-in Capital in Excess of Par (5,000 × $7) | 35,000 | |
| Retained Earnings (5,000 × $4) | 20,000 | |
| Cash (5,000 × $12) | 60,000 |
The $35,000 removes the paid-in capital that came from the original $8 issue. The $20,000 is the amount Crestview paid above that original price. If Crestview already had a credit balance in Paid-in Capital from Treasury Stock, it would use that balance before Retained Earnings.
Either way, total stockholders’ equity falls by $60,000. Only the accounts inside equity are different.
Common mistakes
Most errors in treasury stock journal entries come from treating the shares like an investment the company owns. Watch for these:
- Recording a gain or loss. Differences go to Paid-in Capital from Treasury Stock or Retained Earnings, never to the income statement.
- Crediting Treasury Stock at the resale price. Treasury Stock is always credited at cost.
- Skipping Paid-in Capital from Treasury Stock on a below-cost sale. Use its balance first, then Retained Earnings.
- Crediting Retained Earnings on an above-cost sale. The excess is paid-in capital, not earnings.
- Using the wrong cost when shares were bought at different prices. Apply the company’s cost flow assumption, such as FIFO or average cost, and use it consistently.
- Confusing these entries with the treasury stock method for EPS. That method is a diluted EPS calculation for options and warrants, not a journal entry.
Practice questions with answers
1. A company buys back 2,500 of its shares at $20 per share. Record the entry.
| Account | Debit | Credit |
|---|---|---|
| Treasury Stock (2,500 × $20) | 50,000 | |
| Cash | 50,000 |
Treasury Stock is debited for the full cost paid. The par value and original issue price do not matter.
2. The company resells 1,000 of those shares at $26. Record the entry.
| Account | Debit | Credit |
|---|---|---|
| Cash (1,000 × $26) | 26,000 | |
| Treasury Stock (1,000 × $20) | 20,000 | |
| Paid-in Capital from Treasury Stock | 6,000 |
The $6 per share excess over cost is paid-in capital, not a gain.
3. With a $6,000 balance in Paid-in Capital from Treasury Stock, the company resells the other 1,500 shares at $14. Record the entry.
| Account | Debit | Credit |
|---|---|---|
| Cash (1,500 × $14) | 21,000 | |
| Paid-in Capital from Treasury Stock | 6,000 | |
| Retained Earnings | 3,000 | |
| Treasury Stock (1,500 × $20) | 30,000 |
The shortfall is $9,000 ($30,000 − $21,000). The $6,000 paid-in capital balance absorbs part of it, and Retained Earnings takes the remaining $3,000.
Interactive quiz: match each treasury stock journal entry
Now put all four entry types together. For each transaction, choose the accounts to debit and the accounts to credit. Use the hints if you get stuck, then open the solution to see how each answer is derived.
Frequently asked questions
Why is there no gain or loss when treasury stock is resold?
Gains and losses come from selling assets, and treasury stock is not an asset. A company also cannot earn income by trading its own shares with its owners, so the difference goes to equity accounts instead of net income.
Where is Paid-in Capital from Treasury Stock reported?
It is reported in stockholders’ equity as part of additional paid-in capital. Textbook and exam problems usually show it on its own line, while many companies combine it with their other additional paid-in capital on the balance sheet.
Can treasury stock transactions increase retained earnings?
Not under the cost method. Excess proceeds are credited to Paid-in Capital from Treasury Stock. Retained earnings can only be reduced, when a below-cost sale is larger than that paid-in capital balance.
Does the original issue price matter when the company buys back shares?
Not under the cost method. Treasury Stock is debited for the price paid to reacquire the shares, and the original issue price matters only if the shares are later retired. Under the par value method, it matters right away, because the buyback removes the paid-in capital from the original issue.
What happens to Treasury Stock when the shares are resold?
Treasury Stock is credited for the cost of the shares sold, never their resale price. If all the shares were bought at one price, use that cost per share. If they were bought at different prices, use the company’s cost flow assumption, such as FIFO or average cost.
Is treasury stock an asset?
No. Treasury stock is a contra-equity account. It is shown as a deduction in the stockholders’ equity section, not as an asset on the balance sheet.
Do treasury shares receive dividends or count in EPS?
No. Treasury shares are issued but not outstanding, so they get no dividends and no votes, and they are left out of the weighted-average shares used to compute earnings per share.
Is the treasury stock method for EPS the same thing?
No. The treasury stock method is a diluted EPS calculation for options and warrants. It assumes the exercise proceeds buy back shares, but it creates no journal entries. Treasury stock journal entries record actual share buybacks and resales.
Sources
- PwC Viewpoint: Treasury stock, including reissuance gains and losses (9.3)
- Deloitte DART: Repurchases, Reissuances, and Retirements of Common Stock (ASC 505-30)
About the author
Mansour Farhat, CPA, CIA, DBA, is the founder of Farhat Lectures and its YouTube channel. He holds a Doctor of Business Administration from Temple University and a Master of Accountancy from Bloomsburg University. He teaches accounting students and CPA, CMA, and EA candidates with clear, step-by-step explanations. Read more about Professor Farhat.
Continue learning with Farhat Lectures
Strengthen your accounting understanding with clear explanations and guided practice.
Explore the free sample course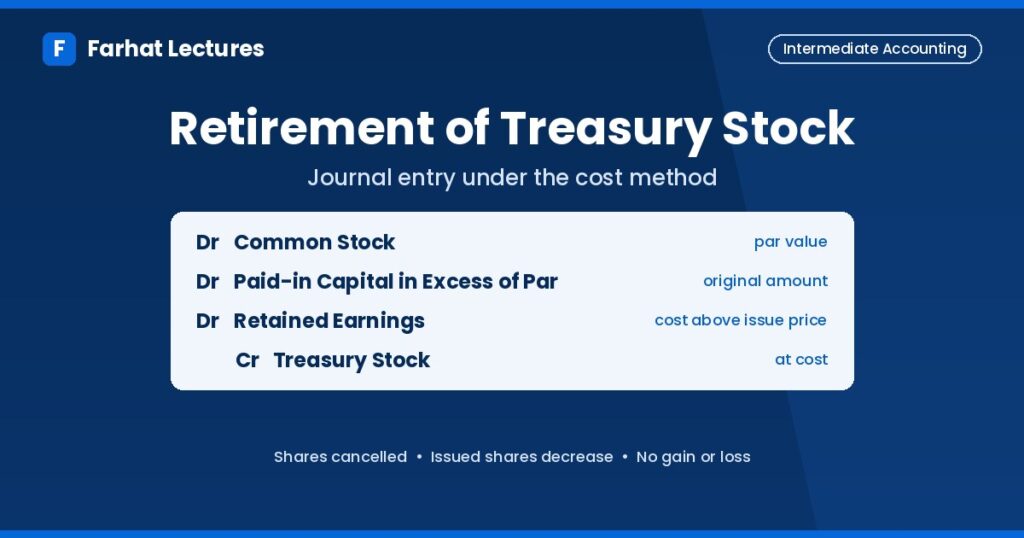

Responses