
Changes in Accumulated Other Comprehensive Income: Roll-Forward, Example, and Presentation

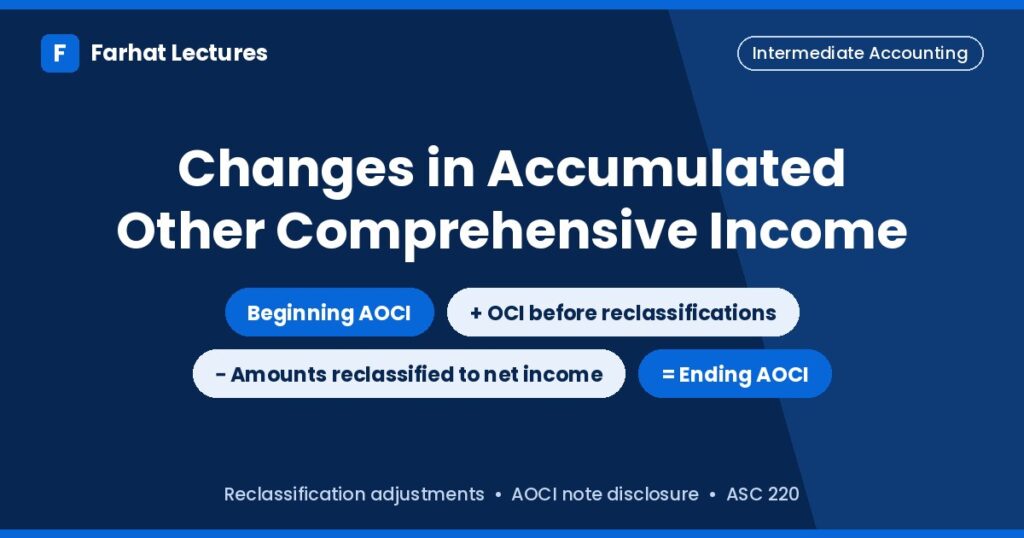
Changes in accumulated other comprehensive income (AOCI) are reported in a roll-forward for each AOCI component: beginning balance, plus other comprehensive income (OCI) before reclassifications, minus gains (or plus losses) reclassified to net income, equals the ending balance. US GAAP (ASC 220-10-45-14A) requires it, either on the face of the statements or in the notes.
This matters because the roll-forward connects three statements. The statement of comprehensive income reports this year’s OCI, the balance sheet reports the AOCI balance, and the note shows how the reclassification moved a gain from one to the other. This lesson uses the Harlow Co. numbers from what a reclassification adjustment is and reclassification adjustment journal entries.
Watch: OCI vs. AOCI and reclassification adjustments (starts at 5:56, equity and accumulated other comprehensive income)
OCI vs. AOCI: what is the difference?
| Feature | Other comprehensive income (OCI) | Accumulated other comprehensive income (AOCI) |
|---|---|---|
| What it measures | Gains and losses for one period | Cumulative balance of past OCI |
| Where it appears | Statement of comprehensive income | Stockholders’ equity on the balance sheet |
| Effect of a reclassification | Reduces OCI for a realized gain; increases it for a realized loss | Removes the realized item from the balance |
| Closes each year? | Yes, to AOCI | No, it carries forward |
Each year’s OCI closes into AOCI, so the changes in accumulated other comprehensive income for a year equal that year’s OCI. One exception: if a company owns less than 100% of a subsidiary, the outside owners’ share of OCI (the noncontrolling interest) goes to the noncontrolling interest, not to the parent’s AOCI. For more on how OCI fits into comprehensive income, see what is comprehensive income. To see where the AOCI balance sits in equity, read our guides to the stockholders’ equity section of the balance sheet and the statement of stockholders’ equity.
Where can a reclassification adjustment be presented?
A company has some choice. Under ASC 220-10-45-14A, as amended by ASU 2013-02, it must present the changes in accumulated other comprehensive income for each component, showing current-period reclassifications separately from other OCI. That presentation can be on the face of the financial statements or in a note. The reclassification can also be displayed as its own line in the statement of comprehensive income.
| Option | What it looks like |
|---|---|
| Gross on the face of the statement of comprehensive income | A separate line: “Less: reclassification adjustment for gains included in net income” |
| Net on the face, detail in the notes | One OCI line for the net change, with the reclassification shown in the changes in AOCI note |
| Changes in AOCI note (roll-forward) | Beginning balance, OCI before reclassifications, amounts reclassified, ending balance, by component |
The note presentation is worth knowing well, because you will see the same roll-forward format in many public companies’ annual reports (Form 10-K).
Worked example: Harlow Co.’s changes in accumulated other comprehensive income
Hypothetical example; income taxes ignored. Harlow Co. ended Year 1 with AOCI of $18,000 from two available-for-sale (AFS) bonds: a $12,000 unrealized gain on Bond A and a $6,000 unrealized gain on Bond B. In Year 2 it sold Bond A at its Year 1 fair value, realizing the $12,000 gain that was already in AOCI, and Bond B lost $5,000 of fair value.
| Changes in accumulated other comprehensive income: AFS debt securities | Amount |
|---|---|
| Beginning balance, January 1, Year 2 | $18,000 |
| Other comprehensive loss before reclassifications (Bond B) | ($5,000) |
| Amounts reclassified from AOCI (Bond A gain) | ($12,000) |
| Net current-period other comprehensive loss | ($17,000) |
| Ending balance, December 31, Year 2 | $1,000 |
The ending $1,000 equals Bond B’s unrealized gain ($91,000 fair value − $90,000 amortized cost). It also matches the $1,000 debit balance in Bond B’s Fair Value Adjustment account, the valuation account that brings the bond from amortized cost up to fair value on the balance sheet.
The same numbers on the statement of comprehensive income
Harlow’s net income for Year 2 is $450,000, including the $12,000 realized gain. Here are the two ways to show OCI.
| Gross presentation | Amount |
|---|---|
| Net income | $450,000 |
| Unrealized holding loss arising during the period | ($5,000) |
| Less: reclassification adjustment for gain included in net income | ($12,000) |
| Comprehensive income | $433,000 |
| Net presentation | Amount |
|---|---|
| Net income | $450,000 |
| Unrealized holding loss, net of reclassification adjustment (see AOCI note) | ($17,000) |
| Comprehensive income | $433,000 |
Both give the same comprehensive income and the same $17,000 of changes in accumulated other comprehensive income. The net version relies on the AOCI note to show the $12,000 reclassification.
Amounts reclassified by income statement line item
Under ASC 220-10-45-17 through 45-17B, companies identify the affected income statement lines for significant amounts that U.S. GAAP requires them to reclassify entirely into net income in the same reporting period. Companies can present this detail on the income statement or in the notes. For other significant reclassifications, they cross-reference the note that explains the effect of the reclassification.
| AOCI component | Amount reclassified | Affected line item in net income |
|---|---|---|
| Unrealized gains on AFS debt securities | $12,000 | Gain on sale of investments |
Changes in AOCI with several components
Real companies rarely have just one AOCI component. Their changes in AOCI note usually shows a column for each component plus a total column. Here is a hypothetical example for Northbay Corp., with income taxes ignored.
| Changes in AOCI | AFS debt securities | Foreign currency translation | Pension items | Total |
|---|---|---|---|---|
| Beginning balance | $10,000 | ($8,000) | ($25,000) | ($23,000) |
| OCI before reclassifications | $6,000 | ($3,000) | ($2,000) | $1,000 |
| Amounts reclassified from AOCI | ($4,000) | $0 | $1,500 | ($2,500) |
| Net current-period OCI | $2,000 | ($3,000) | ($500) | ($1,500) |
| Ending balance | $12,000 | ($11,000) | ($25,500) | ($24,500) |
Notice the signs. The $4,000 AFS reclassification is negative because a realized gain moves out of AOCI and into net income.
The $1,500 pension reclassification is positive. It is amortization of a net actuarial loss (a loss from changes in pension assumptions or returns) that is now included in net periodic pension cost. Moving a loss out of AOCI makes the balance less negative.
Foreign currency translation adjustments stay in AOCI until the foreign operation is sold or substantially liquidated, so there is no reclassification this year.
Northbay would also tell readers which net income lines were affected: the $4,000 went to gain on sale of investments, and the $1,500 went to the line for the other components of net periodic pension cost. Total AOCI fell by $1,500, which equals Northbay’s other comprehensive loss for the year.
Common mistakes
- Mixing up OCI and AOCI. OCI is this year’s change; AOCI is the cumulative balance.
- Adding the reclassified gain to AOCI. A gain reclassified to net income reduces AOCI. A loss reclassified to net income increases AOCI.
- Not reconciling the ending balance. Ending AOCI for AFS securities should equal the Fair Value Adjustment on securities still held (ignoring taxes and credit losses).
- Applying the reclassification adjustment in net income. Net income includes the realized gain or loss. The reclassification adjustment reduces OCI for a gain and increases OCI for a loss.
- Putting stock investment gains in OCI. Since ASU 2016-01, equity investments with a readily determinable fair value are measured at fair value through net income, so their unrealized gains and losses never enter AOCI.
- Forgetting noncontrolling interests. OCI that belongs to the outside owners of a subsidiary is allocated to the noncontrolling interest, not to the parent’s AOCI.
Interactive AOCI Practice Exercise
Accumulated Other Comprehensive Income (AOCI) Roll-Forward and Reclassification Adjustments
Use the Harlow Co. example above to check your understanding of the AOCI roll-forward. Practice reconciling beginning and ending AOCI and identifying how U.S. GAAP presents reclassification adjustments by component.
Practice questions with answers
Question 1: Ending AOCI
Fenwick Co.’s AOCI for AFS debt securities was $25,000 at the start of the year. OCI before reclassifications was $8,000, and $10,000 of gains was reclassified to net income. What is ending AOCI?
Answer:
$23,000
$25,000 + $8,000 − $10,000 = $23,000.
Question 2: Solve for the amount reclassified
Glenrock Inc. began the year with AOCI of $4,000 (unrealized gains on AFS debt securities). Holding gains arising during the year were $3,000, and ending AOCI was $2,000. How much was reclassified to net income?
Answer:
$5,000 of gains
$4,000 + $3,000 − reclassification = $2,000, so the reclassification is $5,000.
Question 3: OCI and comprehensive income
Hollis Corp. reports net income of $300,000, including a $9,000 realized gain on an AFS bond that was fully reported in OCI in earlier years. Its remaining AFS bonds had holding gains of $4,000 during the year. Compute OCI and comprehensive income.
Answer:
OCI ($5,000); comprehensive income $295,000
OCI = $4,000 − $9,000 = ($5,000). Comprehensive income = $300,000 − $5,000 = $295,000.
Want more practice like this? Work through CPA Exam Simulation: Investment Available for Sale and Comprehensive Income in the Farhat Lectures Intermediate Accounting course.
Key takeaways
- Changes in accumulated other comprehensive income follow one formula: ending AOCI = beginning AOCI + OCI before reclassifications − gains reclassified to net income (or + losses reclassified).
- Changes in AOCI are presented by component, on the face of the statements or in the notes (ASC 220-10-45-14A).
- A reclassification adjustment can appear gross on the statement of comprehensive income or net, with details in the AOCI note.
- Identify the affected income statement lines for significant amounts required to be reclassified entirely into net income in the same period. For other significant reclassifications, cross-reference the relevant note.
- In the Harlow example, ending AOCI for AFS debt securities equals the remaining unrealized gain on Bond B because the example excludes taxes and credit losses.
Frequently asked questions
What is the difference between OCI and AOCI?
OCI is a flow: the gains and losses for one period, reported in the statement of comprehensive income. AOCI is a balance: the cumulative total of past OCI, reported in stockholders’ equity on the balance sheet.
Does a reclassification out of AOCI change total comprehensive income?
No, not overall. When a gain that was already in OCI is realized, net income goes up by the gain and the reclassification adjustment lowers OCI by the same amount. Total comprehensive income is unchanged, so the gain is counted only once. In the Harlow example, comprehensive income is $433,000 either way.
Do private companies have to present changes in accumulated other comprehensive income?
Yes. ASC 220-10-45-18B exempts nonpublic entities from the line-item reclassification disclosures in ASC 220-10-45-17 through 45-17B for interim periods only. They must still present the changes in AOCI by component under ASC 220-10-45-14A.
Can the AOCI changes be shown net of tax?
Yes. The changes may be presented before tax or net of tax, as long as the income tax allocated to each component, including reclassification adjustments, is shown under ASC 220-10-45-12. For example, at a 25% tax rate, Harlow’s $12,000 reclassification would be $9,000 net of $3,000 of tax. The rest of this lesson ignores taxes.
Which standard introduced the amounts reclassified disclosure?
FASB Accounting Standards Update 2013-02, which amended ASC 220-10-45. It added the requirement to report changes in AOCI by component and significant amounts reclassified out of AOCI.
What items are included in accumulated other comprehensive income?
The most common are unrealized gains and losses on available-for-sale debt securities, foreign currency translation adjustments, pension and other postretirement items not yet included in net periodic benefit cost, gains and losses on cash flow hedges, and changes in a liability’s own credit risk when the fair value option is used.
Are unrealized gains on stock investments reported in AOCI?
Usually no. Since ASU 2016-01, equity investments with a readily determinable fair value are measured at fair value through net income, so their unrealized gains and losses skip OCI. Today, AOCI from investments mainly comes from available-for-sale debt securities.
Where does AOCI appear in the financial statements?
AOCI is a separate line in stockholders’ equity on the balance sheet. The statement of stockholders’ equity shows the year’s OCI in an AOCI column, and the changes in AOCI note shows the detail by component.
Sources
- FASB ASU 2013-02, Comprehensive Income (Topic 220): Reporting of Amounts Reclassified Out of AOCI (ASC 220-10-45-12, 45-14A, 45-17 through 45-18B)
- PwC Viewpoint: Financial statement presentation, 4.5 Accumulated other comprehensive income
- Journal of Accountancy: FASB changes format for reporting reclassifications out of accumulated OCI
- FASB Accounting Standards Codification, Topic 220: Comprehensive Income
About the author
Mansour Farhat, CPA, CIA, DBA, teaches accounting and CPA exam review at Farhat Lectures and on the Farhat Lectures YouTube channel.
Continue learning with Farhat Lectures
Strengthen your accounting understanding with clear explanations and guided practice.
Ready for the full topic? The Farhat Lectures Intermediate Accounting course walks through investments, comprehensive income, and stockholders’ equity step by step.
Explore the free sample course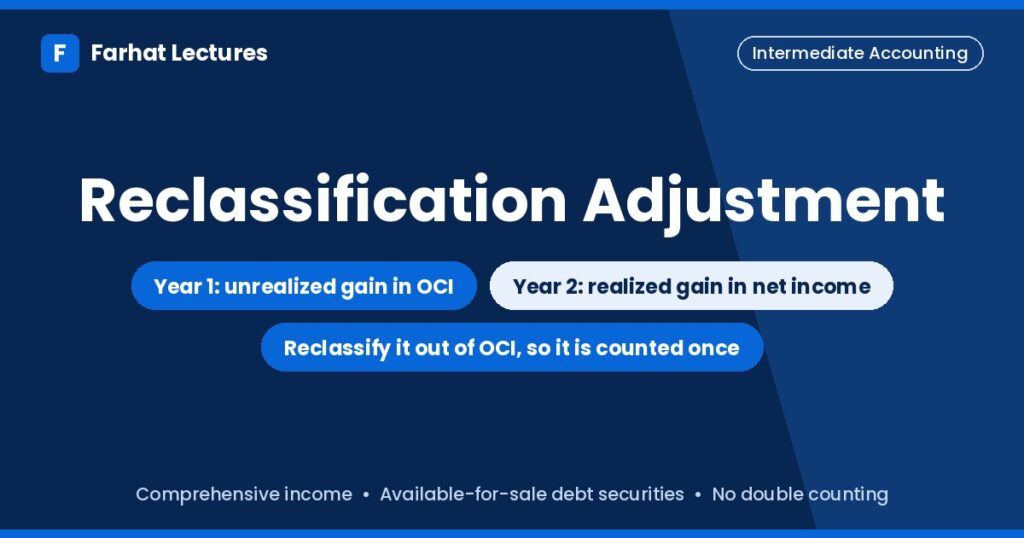
Responses