
Income from Discontinued Operations: Definition, Criteria, and Example

Introduction
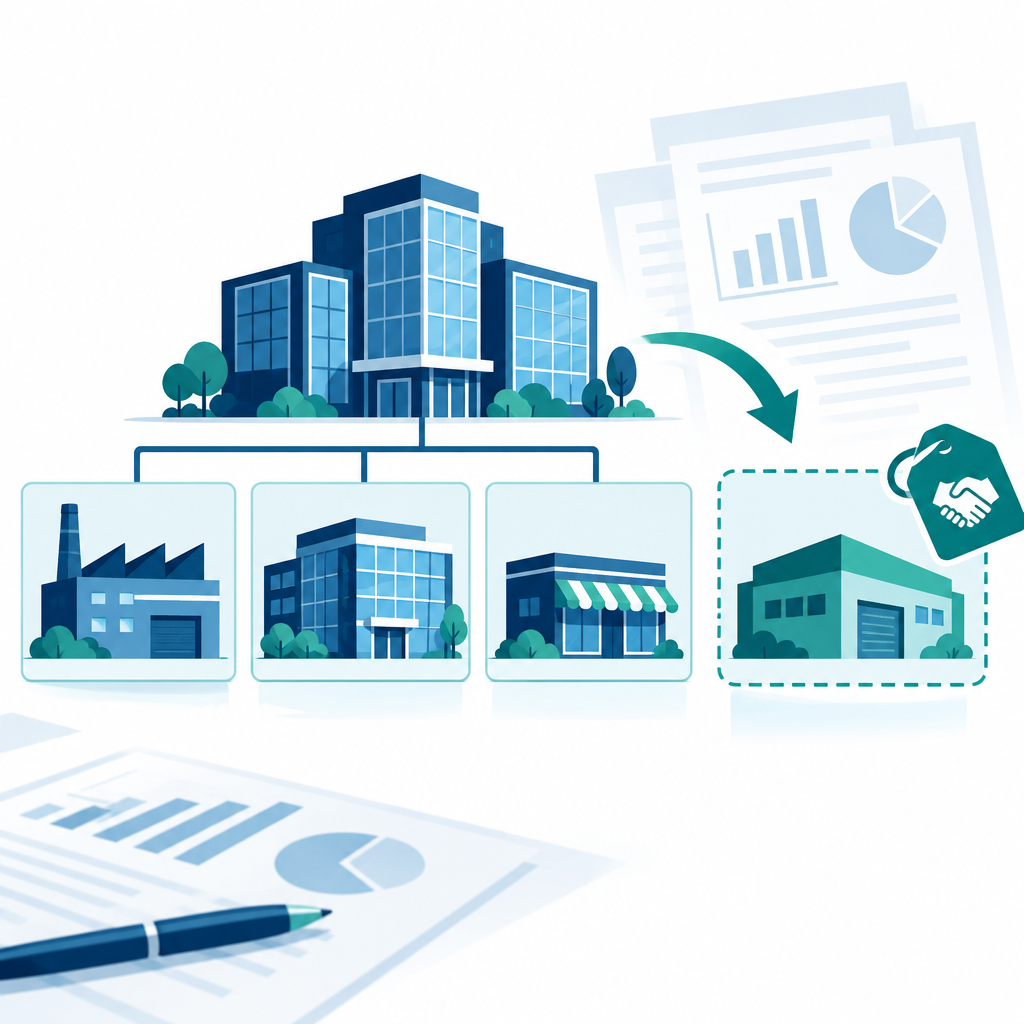
Income from discontinued operations is the after-tax operating result and disposal or measurement gain or loss of a qualifying business component. A sale or held-for-sale classification alone is insufficient: the component must meet the discontinued-operations criteria of the applicable accounting framework. Under FASB ASC 205-20 and IFRS 5, it is shown on the income statement, net of tax, below income from continuing operations, so readers can judge the results of the business that will continue.
If you are studying for the CPA exam, this topic shows up in FAR when you are asked to prepare a single-step or multi-step income statement from a trial balance. CMA Part 1 tests it under external financial reporting. The rules below are the ones examiners expect.
Definition and Criteria
Under US GAAP, the rules live in FASB Accounting Standards Codification (ASC) Subtopic 205-20, Discontinued Operations. Under the general model established by ASU 2014-08, a disposal is reported as a discontinued operation only if it represents a strategic shift that has, or will have, a major effect on the company’s operations and financial results. The FASB’s own examples are disposing of a major geographic area, a major line of business, a major equity method investment, or another major part of the entity. Selling a few underperforming stores or dropping one small product usually does not qualify.
Under IFRS, the rules are in IFRS 5, Non-current Assets Held for Sale and Discontinued Operations. IFRS 5 does not use the phrase strategic shift. Instead, it asks whether the component is a separate major line of business or geographical area of operations, is part of a single coordinated plan to dispose of one, or is a subsidiary acquired only to be resold.
Under the general US GAAP model (ASC 205-20-45-1B through 45-1E), the following conditions apply. A separate exception for an acquired business held for sale is described below:
- It is a component of an entity. A component is a piece of the business whose operations and cash flows can be clearly separated from the rest of the company, both operationally and for financial reporting. It can be a reportable segment, an operating segment, a reporting unit, a subsidiary, or an asset group. A group of related components can qualify together.
- It has been disposed of or is held for sale. The component was sold, was disposed of another way (for example abandoned or spun off to shareholders), or meets the held-for-sale criteria below.
- The disposal is a strategic shift. It has, or will have, a major effect on the company’s operations and financial results.
Held-for-sale criteria (ASC 205-20-45-1E and ASC 360-10-45-9). A component is held for sale when management has committed to a plan to sell it, it is available for immediate sale in its present condition, an active program to find a buyer has begun, the sale is probable and expected to close within one year, it is being actively marketed at a reasonable price, and actions indicate that significant changes to the plan or its withdrawal are unlikely. Limited exceptions can permit a sale period longer than one year.
Two points students often get wrong:
- Continuing involvement no longer disqualifies a disposal. Before 2015, a company could not report a discontinued operation if it kept significant involvement, such as a supply agreement, with the unit it sold. ASU 2014-08 removed that rule. If the remaining qualification criteria are met, continuing involvement does not by itself prevent discontinued-operations reporting; applicable disclosures are still required.
- A business acquired with the intent to resell it, which meets the held-for-sale criteria at the acquisition date, is reported as a discontinued operation even without a strategic shift (ASC 205-20-45-1D).
Authoritative references: FASB ASC 205-20 (Discontinued Operations), ASC 360-10 (held-for-sale measurement), ASC 740-20 (intraperiod tax allocation), and ASC 260-10 (earnings per share), available through the FASB Accounting Standards Codification; and IFRS 5: Non-current Assets Held for Sale and Discontinued Operations.
Reporting on Financial Statements
Under GAAP and IFRS, the result of discontinued operations is reported separately from continuing operations in the income statement. This allows investors and analysts to assess the performance of the business’s core activities without the effects of segments that have been or are planned to be disposed of.
What Is Included in Income from Discontinued Operations?
The amount reported includes:
- Net income or loss from the operations of the discontinued segment up until the date of disposal.
- Gain or loss on the measurement to fair value less costs to sell, or on the actual disposal of the assets or disposal group constituting the discontinued operation.
Under US GAAP, discontinued operations are presented net of tax below income from continuing operations. The disposal gain or loss may be presented separately in that section or disclosed in the notes. IFRS 5 requires a single net-of-tax amount on the face, with the required analysis on the face or in the notes.
Where Does It Appear on a Single-Step vs. Multiple-Step Income Statement?
- Single-Step Income Statement: This format also presents qualifying discontinued operations separately, net of tax, below income from continuing operations and above net income.
- Multiple-Step Income Statement: This more detailed format breaks down revenues, costs, and expenses more granularly. Income from discontinued operations is shown after income from continuing operations but before net income, providing clarity on its impact on the company’s overall financial health.
Video: Reporting Discontinued Operations
In this segment, Professor Farhat explains how the operating results of a discontinued component and the gain or loss on its disposal are presented below income from continuing operations, net of tax. Selected segment: 5:30–8:19.
Jump to the part you need in the full video: criteria at 3:10, reporting requirements at 5:30, tax considerations at 8:19, and the net-of-tax formula at 10:06.
Watch the full Farhat Lectures lesson on YouTube.
Why Is Income from Discontinued Operations Reported Separately?
For Investors and Analysts: This separation helps users of the financial statements assess the performance of the company’s continuing operations and make more informed decisions about the company’s future earnings potential and financial health.
For forecasting: Separate presentation helps users distinguish results from the disposed component from the earnings base of the remaining business. Continuing operations may still include unusual or nonrecurring items.
How Do You Account for Discontinued Operations?
The following steps apply the US GAAP model. The comparison table summarizes the principal IFRS distinctions.
Identification of Discontinued Operations
Apply the component and strategic-shift tests discussed above, or the acquired-business exception when applicable. Under IFRS, apply the separate qualification criteria in IFRS 5 rather than substituting the US GAAP strategic-shift test.
Measurement of Results
Include the qualifying component’s results through disposal, or through the reporting date if it remains unsold. This includes:
- Operating Results: Include the component’s operating results for the entire reporting period through disposal or the reporting date. Attribute revenues, expenses, any allocable interest, and income taxes under the applicable guidance; do not automatically allocate general corporate costs.
- Impairment Losses: If the carrying amount of the assets exceeds their fair value less costs to sell, an impairment loss must be recognized.
- Gain or Loss on Disposal: When the sale closes, the gain or loss is the net proceeds (sale price minus costs to sell) minus the carrying amount of the component’s assets and liabilities. Carrying amount simply means the book value on the balance sheet. Before sale, a gain on disposal is not recognized. A subsequent recovery of a previously recognized held-for-sale write-down may, however, be recognized within the limits below.
While a component is held for sale but not yet sold, three rules apply under ASC 360-10:
- Measure it at the lower of its carrying amount or its fair value less costs to sell. If fair value less costs to sell is lower, record a loss for the difference and report that loss in discontinued operations.
- Stop depreciation and amortization of long-lived assets within the scope of ASC 360 once they are classified as held for sale, even if they remain in use. Other assets continue to follow their applicable measurement guidance.
- If fair value less costs to sell subsequently rises, recognize a recovery only up to the cumulative loss previously recognized for the held-for-sale measurement under ASC 360. This limited recovery is distinct from a gain on disposal.
Also show the component’s assets and liabilities separately on the balance sheet, as assets held for sale and liabilities held for sale. Do not net them against each other (ASC 205-20-45-10). IFRS 5 paragraphs 15, 25, and 38 reach the same answers.
Continue studying with Farhat Lectures’ Intermediate Accounting course or explore the FAR CPA sample course.
Disclosures
In addition to the income statement presentation, detailed disclosures are required to provide users of financial statements with information about discontinued operations. These disclosures may include:
- A description of the discontinued operation and the facts and circumstances leading to its disposal.
- The financial effects of the disposal, including the revenues and expenses of the discontinued operations, pre-tax profit or loss, and the tax effect.
- If the discontinued operation has not been disposed of by the end of the reporting period, a description of the assets and liabilities held for sale.
Reclassification of Comparative Information
If a company discontinues an operation in the current period, the results of that operation for prior periods must be reclassified and presented as discontinued operations in the comparative statements. This reclassification ensures that the financial statements reflect a consistent approach to discontinued operations, allowing users to make like-for-like comparisons across periods.
Example
Imagine a company, XYZ Corp, that operates in three segments: electronics, automotive parts, and home appliances. The company decided to sell its home appliances division because it wants to focus on its core segments of electronics and automotive parts. Assume the division is a distinguishable component and its disposal represents a strategic shift with a major effect on operations and financial results, qualifying for discontinued-operations reporting. Assume a 20% tax rate applies to both its operating income and disposal gain, with no permanent differences.
Financial Performance for the Year
- Revenue from continuing operations: $500 million
- Income from continuing operations, after tax: $50 million
- Revenue from the home appliances division (discontinued operations) until the sale date: $80 million
- Expenses related to the home appliances division until the sale date: $60 million
- Gain on sale of the home appliances division: $30 million
Reporting
Step 1: Operating results of the discontinued division
- Revenue until the sale date: $80 million
- Expenses until the sale date: $60 million
- Income from operations before tax: $20 million
- Income tax at 20%: $4 million
- Income from operations, net of tax: $16 million
Step 2: Gain on the sale
- Gain on sale before tax: $30 million
- Income tax at 20%: $6 million
- Gain on sale, net of tax: $24 million
Step 3: Total income from discontinued operations, net of tax
$16 million + $24 million = $40 million
How it looks on the face of the income statement (in millions)
| Income from continuing operations | $50 |
| Discontinued operations: | |
| Income from operations of discontinued home appliances division, net of $4 income tax | $16 |
| Gain on disposal of home appliances division, net of $6 income tax | $24 |
| Income from discontinued operations, net of tax | $40 |
| Net income | $90 |
Three things to notice. First, the subtotal above the discontinued section is called income from continuing operations, not net income. Net income is only the bottom line. Second, the $80 million of revenue and $60 million of expenses do not appear on the face of the income statement. They go in the notes, where ASC 205-20-50-5B requires the major line items of the discontinued operation to be disclosed. Third, the gain on disposal can be shown as its own line, as above, or folded into the single $40 million line and disclosed in the notes (ASC 205-20-45-3B). For entities subject to ASC 260, the company must also show earnings per share for income from continuing operations and for net income on the face of the statement, and the per-share amount for discontinued operations on the face or in the notes (ASC 260-10-45-3).
Common CPA Exam Mistakes on Discontinued Operations
Watch for these common errors:
- Accruing next year’s expected losses. If the division is expected to lose $200,000 more before the sale closes next year, that loss is recorded next year when it happens, not this year. Only losses already incurred, plus any write-down to fair value less costs to sell, go in this year’s discontinued operations.
- Confusing a disposal gain with an impairment recovery. Recognize the gain on disposal when the sale occurs. Before sale, a qualifying recovery of a previous held-for-sale write-down is permitted only within the applicable cumulative-loss limit.
- Continuing to depreciate qualifying long-lived assets. Depreciation and amortization stop for assets within the held-for-sale measurement scope; this does not suspend measurement rules for every asset in the component.
- Reporting the whole thing before tax. Present the discontinued-operations result net of the applicable income tax expense or benefit. Income tax on continuing operations stays with continuing operations. This split is called intraperiod tax allocation (ASC 740-20-45-2).
- Moving the wrong items below the line. Unusual or infrequent items, restructuring charges, and losses on selling a few assets stay in income from continuing operations. Only a qualifying component moves to discontinued operations.
- Forgetting the prior year. When you present comparative statements, last year’s results for the same component are reclassified into discontinued operations too.
- Starting the clock at the decision date. The component’s operating results for the entire period presented go in discontinued operations, not just the results after the board approved the sale.
GAAP vs. IFRS at a glance
| Topic | US GAAP (ASC 205-20, ASC 360-10) | IFRS (IFRS 5) |
|---|---|---|
| Qualifying test | Strategic shift with a major effect on operations and financial results | Separate major line of business or geographical area, a single coordinated disposal plan, or a subsidiary acquired for resale |
| Held-for-sale measurement | Lower of carrying amount or fair value less costs to sell | Same |
| Depreciation of qualifying long-lived assets while held for sale | Stops | Stops |
| Income statement presentation | Net of tax, below income from continuing operations | Single net-of-tax amount on the face, with a breakdown on the face or in the notes |
| Prior periods | Reclassified | Re-presented |
| Balance sheet | Assets and liabilities held for sale shown separately, not offset | Same |
Practice Question
On October 1, Year 1, Rowan Co. committed to a plan to sell its furniture division, and the division met all of the held-for-sale criteria on that date. The division is a distinguishable component, and its disposal represents a strategic shift with a major effect on Rowan’s operations and financial results. The division’s carrying amount was $4,000,000 and its fair value less costs to sell was $3,600,000. The division lost $500,000 from operations during Year 1 (January 1 through December 31). Rowan expects the division to lose another $200,000 in Year 2 before the sale closes. Rowan’s tax rate is 25%; assume the full tax benefit on the operating loss and write-down is recognizable, and no further measurement changes occur before year end. What amount should Rowan report as loss from discontinued operations, net of tax, in its Year 1 income statement?
A. $375,000
B. $675,000
C. $825,000
D. $900,000
Answer: B. $675,000
Here is the math. The Year 1 operating loss of $500,000 is included in full, even the part before October 1, because the whole period’s results of the component are reclassified. The write-down to fair value less costs to sell is $4,000,000 minus $3,600,000, or $400,000, and it is also reported in discontinued operations. That gives a pre-tax loss of $900,000. The expected Year 2 loss of $200,000 is not accrued. Apply the tax benefit: $900,000 multiplied by (1 minus 0.25) equals $675,000.
Why the other answers are wrong: A ignores the write-down. C wrongly accrues the $200,000 expected future loss. D forgets to show the amount net of tax.
Frequently Asked Questions About Income from Discontinued Operations
What qualifies as a discontinued operation under US GAAP?
A component, or group of components, that has been sold, abandoned, spun off, or classified as held for sale, where the disposal is a strategic shift with a major effect on the company’s operations and financial results. The FASB’s examples are a major line of business, a major geographic area, and a major equity method investment (ASC 205-20-45-1B and 45-1C).
How do you calculate income from discontinued operations?
Take the component’s operating income or loss for the period, add the gain or loss on disposal (or the write-down to fair value less costs to sell if the sale has not closed), and subtract the income tax related to those amounts. In formula form: income from discontinued operations, net of tax = (operating income or loss + gain or loss on disposal or write-down) multiplied by (1 minus the tax rate). This simplified formula assumes the same tax rate applies to all amounts and any tax benefit is recognizable; otherwise use the tax expense or benefit determined under the applicable income tax guidance.
Where does income from discontinued operations appear on the income statement?
Below income from continuing operations and above net income, as a net-of-tax amount. The gain or loss on disposal is shown on its own line or disclosed in the notes. Prior periods presented are reclassified so every year is on the same basis.
Are there tax implications for discontinued operations?
Yes, in two ways. For reporting, the income tax on the discontinued operation is shown with it, not with the tax on continuing operations, under intraperiod tax allocation (ASC 740-20-45-2). For cash taxes, the sale itself can create a taxable gain or a deductible loss, which is why the tax rate in the examples is applied to both the operating results and the gain on sale.
Is a discontinued operation the same as an unusual or infrequent item?
No. Unusual or infrequent items, such as a large restructuring charge or a loss from a storm, stay inside income from continuing operations and are disclosed separately (ASC 220-20-45-1). Only a qualifying component disposal moves below income from continuing operations.
Can a company have more than one discontinued operation in a year?
Yes. Each disposal is tested on its own against the criteria. The income statement can combine them in the discontinued operations section, and the notes describe the facts and circumstances of each one.
Keep going
Discontinued operations connects to several other income statement topics you will see on the exam. Review these next: single-step vs. multiple-step income statement, intraperiod tax allocation, earnings per share, and impairment of long-lived assets and assets held for sale. Explore Farhat Lectures through the free FAR CPA sample course or go deeper in the Intermediate Accounting course.

Responses