
How Hard Is the CPA Exam? Why Preparation Matters

How hard is the CPA Exam? It is challenging because you must understand a broad range of material, apply it to unfamiliar situations, and work within a time limit. Preparation builds the knowledge, application skills, and pacing you need to meet that challenge.
If you can follow a lecture but struggle to answer questions on your own, that experience can feel discouraging. It also identifies your next step: practice connecting the explanation to the decisions a question requires.
The CPA Exam feels different when you are prepared
Think about something you can do comfortably today that once seemed difficult: driving a car, preparing a journal entry, or building your first spreadsheet. Practice changed how the task felt. You learned what to look for, what to do next, and how to correct mistakes.
Everything feels hard when you are not prepared. When you are prepared, the same work can feel easy. At Farhat Lectures, we help you prepare.
For the CPA Exam, preparation means understanding why an answer is correct and being able to apply that reasoning when the facts change. The exam still demands effort, but you can approach it with a method instead of guessing where to begin.
How Hard Is the CPA Exam? 2026 Pass Rates
Candidates must pass four sections: the three Core sections—AUD, FAR, and REG—and one Discipline chosen from BAR, ISC, or TCP. Each section allows four hours of testing, for 16 hours altogether. See the AICPA exam overview.
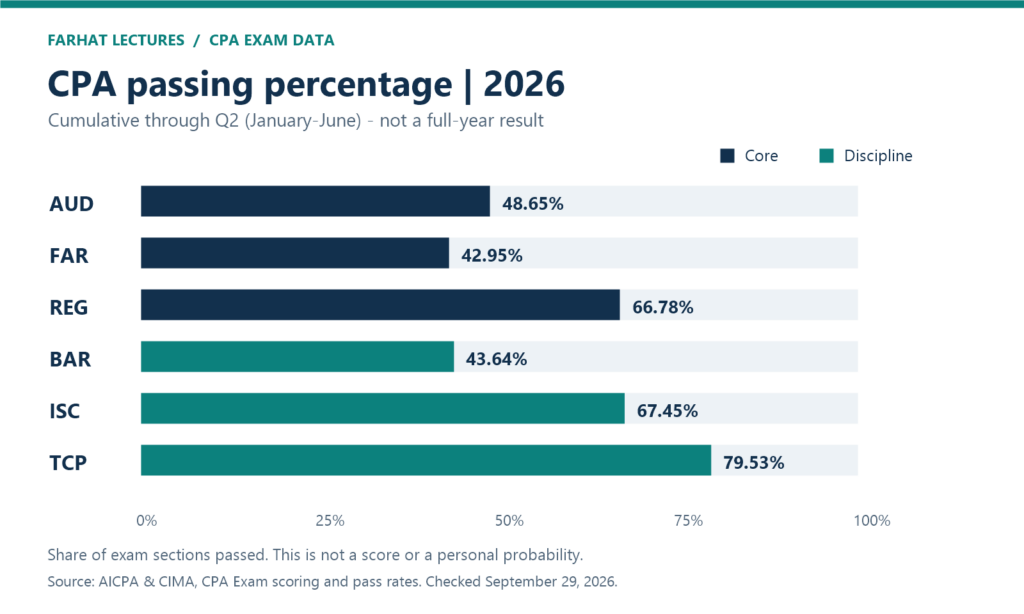
The following cumulative pass rates cover the first two quarters of 2026, the latest figures published by the AICPA as of September 29, 2026.
| CPA Exam section | Type | 2026 pass rate through Q2 |
|---|---|---|
| Auditing and Attestation (AUD) | Core | 48.65% |
| Financial Accounting and Reporting (FAR) | Core | 42.95% |
| Taxation and Regulation (REG) | Core | 66.78% |
| Business Analysis and Reporting (BAR) | Discipline | 43.64% |
| Information Systems and Controls (ISC) | Discipline | 67.45% |
| Tax Compliance and Planning (TCP) | Discipline | 79.53% |
Source: AICPA CPA Exam scoring and pass rates. For more detail, explore our CPA passing percentage guide.
FAR had the lowest cumulative pass rate during this period. These figures describe group results; they do not predict your individual outcome. Candidates bring different experience and preparation, and they select their own Discipline. The AICPA cautions against choosing a Discipline simply because it has a higher pass rate.
Use the numbers to understand the challenge, then evaluate your starting point. If you are deciding where to begin, read our guide to the hardest CPA Exam section and whether to take FAR first.
How Difficult Is the CPA Exam—and Why?
How difficult is the CPA Exam? The challenge comes from retaining a broad range of material, applying concepts to unfamiliar questions, and managing your time. Your preparation and starting knowledge influence how demanding those tasks feel.
You must retain earlier material while learning new topics
Finishing a chapter does not mean you can set it aside until exam week. Build cumulative practice into your schedule so you can discover what you have forgotten while there is time to revisit it.
You must decide how a rule applies
A question can provide familiar numbers but ask for an unfamiliar output. You might calculate an ending balance correctly and still choose the wrong answer because the question asked for the adjusting entry.
You must organize information efficiently
Task-based simulations can require you to work with documents, data, and communications in a realistic scenario. Practice identifying the requirement and finding the evidence needed to answer it. Learn how the AICPA describes simulations.
The following example illustrates how preparation helps you connect a rule to the decision a question requires.
An original CPA practice example: explain the adjustment
This is an original teaching example, not an actual CPA Exam question.
Assume Harbor Office Supply has:
- Accounts receivable of $240,000.
- An existing $1,600 credit balance in its allowance for credit losses.
- A completed credit-loss analysis establishing that the required ending allowance is 3% of accounts receivable.
What credit loss expense should the company record in its year-end adjusting entry?
A. $1,600
B. $5,600
C. $7,200
D. $8,800
Pause and solve it before reading the explanation.
Step 1: Identify what the question asks
The question asks for the expense in the adjusting entry. We first need the required ending allowance, but that calculation alone does not finish the problem.
Step 2: Calculate the required ending allowance
$240,000 × 3% = $7,200
After the adjustment, the allowance account needs a $7,200 credit balance. The 3% estimate is a given assumption in this example, not a universal percentage to use for receivables.
Step 3: Account for the balance already recorded
The account already contains a $1,600 credit balance. The additional credit required is:
$7,200 − $1,600 = $5,600
The correct answer is B.
| Account | Debit | Credit |
|---|---|---|
| Credit loss expense | $5,600 | |
| Allowance for credit losses | $5,600 |
Step 4: Change one detail to test your understanding
Suppose the existing allowance balance were a $1,600 debit instead. The adjustment would need to eliminate that debit and establish the required $7,200 credit balance:
$1,600 + $7,200 = $8,800
The target ending balance remains $7,200. The adjustment changes because the starting balance changes. In the original example, net accounts receivable after the adjustment equals $232,800: $240,000 less the $7,200 ending allowance.
This exercise connects reading the requirement, interpreting an account balance, calculating an adjustment, and understanding a financial statement amount. As you prepare, change one fact in a problem and explain how your answer changes. The more clearly you can explain those connections, the more familiar a new question can feel.
What score do you need to pass the CPA Exam?
You need a 75 on a scale of 0–99 for each section. That score does not mean you answered 75% of the questions correctly. The exam uses scaled scores and is not graded on a curve.
Multiple-choice questions and simulations each contribute 50% of the score in every section except ISC, where the weights are 60% and 40%, respectively. Read the AICPA scoring explanation.
Include both question formats in your preparation. A multiple-choice practice percentage alone cannot tell you how you will perform across the whole section.
How to prepare when the CPA Exam feels overwhelming
Start by identifying the reason you miss questions. Different problems call for different study decisions.
| What happens during practice | What to try next |
|---|---|
| You cannot explain the underlying rule. | Revisit the concept and work through a simple example. |
| You understand the explanation but cannot start a new problem. | Identify the required output and relevant facts before calculating. |
| You overlook dates, exceptions, or debit and credit balances. | Record the missed detail and use a deliberate reading check. |
| You answer correctly without a timer but struggle under time pressure. | Add timed sets and review where you spend your time. |
| You recognize answers from repeated questions. | Use fresh questions and explain your reasoning before checking the solution. |
Learn the concept, then attempt it independently
After a lesson, close your notes and explain the main idea in your own words. Solve an example without following the instructor’s steps. If you get stuck, identify the exact step you cannot explain. That gives your next review session a clear purpose.
Keep an error log that explains your decisions
“Review receivables” is a broad reminder. “I calculated the required allowance but forgot the existing credit balance” tells you exactly what to correct. For each meaningful mistake, record the missed concept or decision and how you will recognize it next time. Return to those entries during cumulative review.
Practice simulations throughout your preparation
Give yourself time to become comfortable with longer requirements and multiple exhibits. Identify the output you must produce, the documents that support it, and the calculations or judgments required. Finish by checking completeness and consistency.
Follow the blueprint for your testing date
The AICPA’s Exam Blueprints describe tested content, weightings, skill levels, and representative tasks. Use the version applicable to your exam date to check the scope of your preparation. Access the CPA Exam Blueprints.
How many hours should you study?
The number of hours you should study depends on your individual background and circumstances. Your accounting knowledge, how recently you studied the material, and how quickly you learn new concepts affect the review and practice you need. Work and family responsibilities also influence how consistently you can study and how long preparation takes.
If you need help planning, Farhat Lectures can help you develop a study plan that fits your needs and circumstances.
How Farhat Lectures helps you prepare
Farhat Lectures offers supplemental courses for candidates using major CPA review providers, including Becker, UWorld, Gleim, Surgent, and Miles. Find the course that matches your CPA section and review program.
Attempt a topic in your primary review course, identify the concept you cannot explain, and work through the corresponding Farhat lesson. Then return to fresh questions and check whether you can apply it independently. Farhat Lectures is an independent supplement and is not affiliated with or endorsed by those review providers.
If you missed the allowance example, focus on the relationship between an account’s existing balance, its required ending balance, and its adjusting entry. Then test that understanding with different numbers. This is how you turn “I watched the lesson” into “I can do the work.”
The monthly self-paced subscription is currently $29.99 per month, with access to all courses and learning resources. It renews automatically until canceled; other subscription options are available. View current plans, billing details, and included support.
Common questions about CPA Exam difficulty
Can I prepare while working full time?
Build a schedule around hours you can consistently protect. Begin with a manageable weekly commitment, include cumulative review, and adjust your exam timeline as you learn how quickly you can master the material.
What if I have been out of school for years?
Start with a diagnostic set of questions. Use the results to identify which foundations need attention. Rebuilding those foundations can make later lessons easier to follow.
How do I know whether my study method is helping?
Look for progress on unfamiliar questions: you can explain the rule, select relevant facts, complete the work independently, and handle a changed fact pattern. Track recurring errors as well as scores.
Can preparation make the CPA Exam easier?
Preparation can make unfamiliar tasks more manageable. You know where to begin, recognize relevant information, and have a process for checking your work. It does not remove every challenge or guarantee a passing score, but it gives you specific skills to bring to that challenge.
Start preparing with one topic today
Choose one topic you repeatedly miss. Study its explanation, solve an example without notes, and attempt a fresh question. Build from there.
When you are prepared, difficult work can begin to feel familiar. At Farhat Lectures, helping you build that preparation is what we do.
Make your next study session count.
Explore a free Farhat lesson and practice explaining the reasoning for yourself.
Responses