
Fair Value of Financial Instruments: Carrying Amount vs. Fair Value Disclosures

The fair value of financial instruments is the price a company would receive to sell a financial asset, or pay to transfer a financial liability, at the balance sheet date. Under ASC 825 and ASC 820, public business entities generally disclose fair value alongside carrying amount and identify the hierarchy level for in-scope financial instruments carried at amortized cost.
Carrying amount is simply the figure on the balance sheet. Examples of financial instruments carried at amortized cost include held-to-maturity bonds and bonds payable. Public business entities (PBEs) include SEC filers. Since ASU 2016-01, entities outside that definition are exempt from this ASC 825 fair value disclosure.
This matters because two companies can report the same carrying amount for very different economic positions. The note reveals potential gains and losses that are not yet in the financial statements. For the three-level fair value hierarchy itself, see fair value disclosures: Level 1, Level 2, and Level 3 explained.
Watch: Fair value disclosures for assets and liabilities (starts at 0:36, disclosing assets and liabilities by hierarchy level)
What counts as a financial instrument?
A financial instrument is cash, an ownership interest in another company, or a contract that gives one party the right to receive cash (or another financial instrument) and the other party the obligation to pay it. Common examples include:
- Financial assets: cash, receivables, notes and loans receivable, investments in debt and equity securities, and derivatives in an asset position.
- Financial liabilities: accounts payable, notes payable, bonds payable, and derivatives in a liability position.
Inventory, equipment, and goodwill are not financial instruments. Equipment and other long-lived assets show up at fair value in the notes mainly when they are impaired and written down, and goodwill impairment testing relies on the fair value of the reporting unit (the part of the business the goodwill is assigned to). Both are covered in recurring vs. nonrecurring fair value measurements. Inventory is different: writing inventory down to net realizable value (or to market, for LIFO inventory) is not a fair value measurement under ASC 820.
How is fair value measured?
ASC 820 defines fair value as an exit price: the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. It is a market-based measure, not the company’s own opinion of what an item is worth.
Companies estimate it using one or more valuation approaches:
- Market approach: uses prices from market transactions for identical or similar items.
- Income approach: converts expected future cash flows into a single present value.
- Cost approach: estimates what it would cost to replace an asset’s service capacity. It is rarely used for financial instruments.
Classify the entire fair value measurement at the lowest level of any input that is significant to it. The three levels are:
- Level 1: quoted prices in active markets for identical items.
- Level 2: other observable inputs, such as quoted prices for similar items or observable interest rates.
- Level 3: significant unobservable inputs that reflect assumptions market participants would use.
For a full walk-through of the levels, see fair value disclosures: Level 1, Level 2, and Level 3 explained.
Why does the FASB require fair value disclosures?
The Financial Accounting Standards Board (FASB) views fair value as relevant for decisions. Critics raise two concerns: some fair values are not reliable, and some can be manipulated to produce results that do not match the economics. Disclosure answers both concerns. It shows the fair value and reports the hierarchy level so readers can assess the observability of significant inputs.
Financial instruments get the most attention because many trade in active markets, so their fair values can often be measured reliably.
What gets disclosed for each type of instrument?
The disclosure depends on how the instrument is measured on the balance sheet. Two Codification topics work together: ASC 820 (Fair Value Measurement) and ASC 825 (Financial Instruments).
| How the instrument is measured | Examples | What the notes show |
|---|---|---|
| At fair value every period (recurring) | Trading securities, available-for-sale debt securities, derivatives | Fair value by Level 1, 2, or 3 (ASC 820), plus extra Level 3 detail |
| At amortized cost | Held-to-maturity bonds, loans receivable, bonds payable | Public business entities: fair value next to carrying amount, with the hierarchy level (ASC 825 and ASC 820) |
| Under the fair value option | Any eligible instrument the company elects to carry at fair value | Reasons for the election, plus ASC 820 disclosures, in one master schedule or a separate schedule |
Two updates matter here. ASU 2016-01 requires public business entities to measure these disclosed fair values at an exit price, and it removed the fair value disclosure for amortized-cost instruments for entities that are not public business entities (see the Journal of Accountancy summary). Public business entities must also give the hierarchy level for fair values they only disclose (ASC 820-10-50-2E).
Which instruments are exempt from the ASC 825 fair value disclosure?
Some financial instruments are left out of the ASC 825 fair value disclosure, even for public business entities. Common examples include:
- Trade receivables and payables due in one year or less
- Pension and other postretirement benefit obligations
- Lease contracts
- Investments accounted for under the equity method
- The company’s own equity instruments classified in stockholders’ equity
That is why you rarely see accounts receivable or accounts payable in the fair value table.
Concentrations of credit risk
Subject to ASC 825’s scope exceptions, public and private entities disclose significant concentrations of credit risk in their annual financial statements. Credit risk is the chance that the other party fails to pay. A substantial exposure can arise from a single counterparty or from a group whose members share a feature, such as the same industry or region.
For each significant concentration, the notes describe:
- The activity, region, or economic feature that identifies the concentration
- The maximum loss if the other parties fail to pay and any collateral turns out to be worthless
- The company’s policy on requiring collateral, and the collateral it holds
- Its policy on master netting arrangements (agreements that let it offset amounts owed in both directions)
Disclosure of market risk, the risk of loss from changes in market prices or interest rates, is encouraged but not required under US GAAP.
Worked example: carrying amount vs. fair value
Hypothetical example. Northbridge Corp. is a public company. Interest rates rose during the year. Its financial instrument note at December 31 shows the following.
| Instrument | Carrying amount | Fair value | Level |
|---|---|---|---|
| Publicly traded equity securities | $120,000 | $120,000 | Level 1 |
| Held-to-maturity corporate bonds | $500,000 | $468,000 | Level 2 |
| Note receivable from a supplier | $200,000 | $194,000 | Level 3 |
| Bonds payable (fixed rate) | $1,000,000 | $940,000 | Level 2 |
How to read it:
- Publicly traded equity securities are already carried at fair value, so both columns match.
- Held-to-maturity bonds are carried at amortized cost. Higher interest rates cut their fair value by $32,000. That potential loss is not recognized because held-to-maturity bonds stay at amortized cost (Northbridge has the intent and ability to hold them until they mature), but the note reveals it.
- The supplier note has no quoted market price. Northbridge estimates the cash flows and risks a market participant would use to price it. The measurement is Level 3 because those unobservable inputs are significant. Its fair value of $194,000 is $6,000 below its carrying amount, which fits a year when interest rates rose.
- Bonds payable are worth $60,000 less than their carrying amount. If Northbridge could buy them back at fair value, it would pay less than the amount it owes on its books.
The fair value option schedule
Under the fair value option, a company can elect to measure eligible financial assets and liabilities at fair value, with most changes reported in net income. A company using the option explains why it made the election. It may fold all of its fair value information into one master schedule, or present a separate schedule just for items under the fair value option (Deloitte Roadmap, Section 12.5). For how the election works for debt, see fair value option for liabilities.
Common mistakes
- Thinking the disclosure changes the balance sheet. Amortized-cost instruments stay at amortized cost; only the note shows fair value.
- Mixing up carrying amount and fair value. Carrying amount is the balance sheet figure. Fair value is the exit price at the balance sheet date: what the company would receive to sell the asset, or pay to transfer the liability, to a market participant.
- Assuming every entity must disclose fair value for amortized-cost items. Since ASU 2016-01, that requirement applies to public business entities.
- Skipping the hierarchy level for disclosed-only items. Public business entities report the level even when fair value is only disclosed.
- Treating a Level 3 fair value as precise. Level 3 relies on significant unobservable inputs, so pay attention to the assumptions and the uncertainty they introduce.
Practice questions with answers
Question 1: Held-to-maturity bonds
A public business entity holds held-to-maturity bonds with an amortized cost of $300,000 and a fair value of $288,000. The fair value decline is due entirely to an increase in market interest rates, and the allowance for credit losses is $0. What appears on the balance sheet, and what appears in the notes?
Answer:
Balance sheet: $300,000. Notes: $288,000 fair value with its level.
Held-to-maturity debt is carried at amortized cost (see how it compares with trading and available-for-sale securities). The $12,000 decline in fair value is disclosed, not recognized as a loss. (Expected credit losses are handled separately through an allowance.)
Question 2: A private company’s bank loan
A private company’s only financial liability is a bank loan carried at amortized cost. Must it disclose the loan’s fair value?
Answer:
No
ASU 2016-01 eliminated the fair value disclosure for amortized-cost instruments for entities that are not public business entities. The company still makes ASC 820 disclosures for anything it measures at fair value.
Question 3: Choosing the level
A public company estimates the fair value of its own bonds payable using quoted prices for similar bonds of other issuers. Which level is that disclosure?
Answer:
Level 2
The inputs are observable market prices, but for similar rather than identical instruments, so the measurement falls in Level 2.
Want more practice like this? Work through the Fair Value Option for Investments lesson in the Farhat Lectures Intermediate Accounting course.
Fair value disclosures for financial instruments
Work through four questions on the ASC 820 fair value hierarchy, how the ASC 825 disclosures compare carrying amount with fair value, and how the fair value option affects reporting.
Choose one answer per question.
Key takeaways
- For in-scope financial instruments carried at amortized cost, public business entities disclose fair value alongside carrying amount.
- Recurring fair value items are disclosed by Level 1, 2, or 3 under ASC 820.
- For those disclosures, fair value is measured at an exit price, and the notes identify the hierarchy level.
- Fair value option users explain the election and may combine everything into one master schedule.
- Level 3 items get extra detail; see the Level 3 reconciliation.
- Public and private entities disclose significant concentrations of credit risk annually, subject to ASC 825’s scope exceptions.
Frequently asked questions
What is the fair value of a financial instrument?
It is the exit price: the amount a company would receive to sell a financial asset, or pay to transfer a financial liability, in an orderly transaction between market participants at the measurement date. ASC 820 defines fair value, and ASC 825 sets the disclosure rules for financial instruments.
Does disclosing fair value change the balance sheet?
No. The disclosure is in the notes. An instrument carried at amortized cost stays at amortized cost on the balance sheet, and the note shows what it would be worth at fair value.
Do private companies have to disclose the fair value of financial instruments?
Not for instruments measured at amortized cost. ASU 2016-01 removed that requirement for entities that are not public business entities. Private companies still give the ASC 820 disclosures for items they measure at fair value.
Why do companies say the carrying amount of receivables approximates fair value?
Short-term items such as cash, trade receivables, and accounts payable turn over quickly, so their carrying amounts are usually close to fair value. Many companies state this instead of listing them in the table. Trade receivables and payables due in one year or less are also exempt from the ASC 825 fair value disclosure.
Is fair value for the disclosure an entry price or an exit price?
An exit price. Public business entities measure the disclosed fair value of amortized-cost instruments the same way ASC 820 defines fair value: the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date.
Do companies have to disclose concentrations of credit risk?
Yes. Subject to ASC 825’s scope exceptions, public and private entities disclose significant concentrations of credit risk from financial instruments in their annual financial statements. A concentration can arise from one counterparty or a group of counterparties. The note describes the concentration, the maximum possible loss, and the entity’s collateral policy.
Are fair value disclosures similar under IFRS?
Yes. IFRS 13 and ASC 820 use the same definition of fair value and the same three-level hierarchy, and their disclosure requirements are broadly similar, though some details differ. Under IFRS, the fair value disclosure for financial instruments comes from IFRS 7, which generally requires the fair value of each class of financial assets and liabilities unless the carrying amount is a reasonable approximation of fair value.
Sources
- Deloitte Roadmap: Fair Value Measurements and Disclosures, Section 11.2 (ASC 820 and ASC 825 disclosure requirements)
- Journal of Accountancy: FASB issues financial instruments standard (ASU 2016-01)
- Deloitte Roadmap: Fair Value Option disclosures, Section 12.5
- IFRS Foundation: IFRS 13 Fair Value Measurement
About the author
Mansour Farhat, CPA, CIA, DBA, teaches accounting and CPA exam review at Farhat Lectures and on the Farhat Lectures YouTube channel.
Continue learning with Farhat Lectures
Strengthen your accounting understanding with clear explanations and guided practice.
Explore the free sample course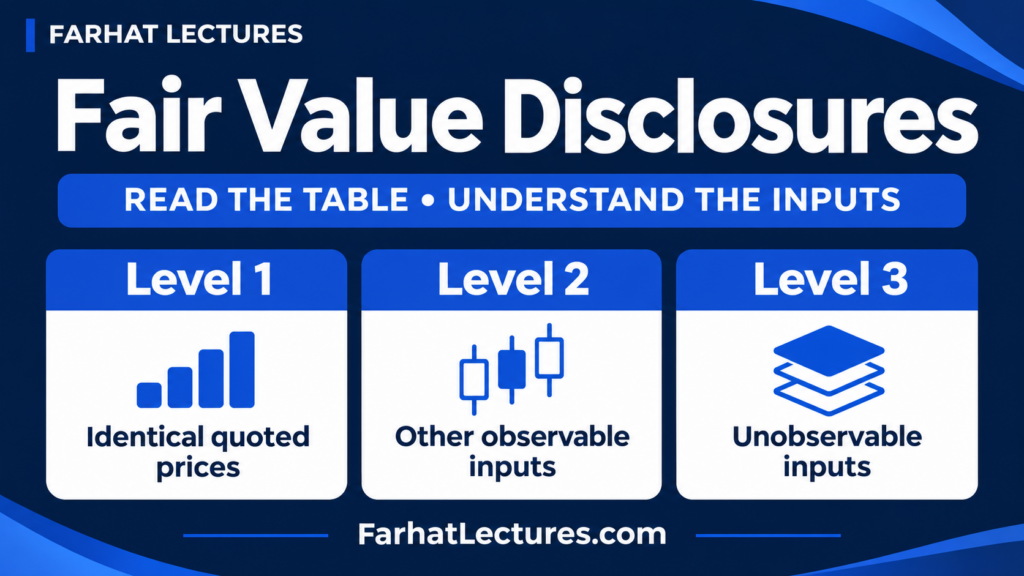

Responses