
Preferred Dividends in EPS: Cumulative vs. Noncumulative and Net Losses

Preferred dividends in EPS are subtracted from net income to find income available to common stockholders, the numerator of basic earnings per share (EPS). For cumulative preferred stock, subtract the current year’s dividend whether or not it is declared. For noncumulative preferred stock, subtract it only if declared. With a net loss, add the dividend to the loss.
This matters because EPS measures earnings per common share. Earnings that belong to preferred stockholders must come out first. CPA Exam FAR questions and intermediate accounting tests check this with undeclared dividends, dividends in arrears, net losses, and diluted EPS. New to EPS? Start with our earnings per share guide. For background on these features, see preferred stock features.
Watch: Earnings Per Share Computation CPA Exam Simulation (starts at 1:47, where the lesson deducts cumulative preferred dividends from net income)
Preferred dividends in EPS: where they go in the formula
Basic EPS = (Net income − Preferred dividends) ÷ Weighted average common shares outstanding
The numerator is called income available to common stockholders. The denominator is covered in weighted average shares outstanding. FASB ASC 260-10-45-11 requires the preferred dividend adjustment; the Deloitte EPS Roadmap on income available to common stockholders summarizes it.
To find the annual preferred dividend, multiply the dividend rate by the total par value of preferred shares outstanding (for example, 6% × $1,000,000 = $60,000), or multiply a per-share dividend by the number of preferred shares.
What if the preferred stock was issued during the year?
Subtract only the dividend that built up while the shares were outstanding.
Hypothetical example: Kestrel Inc. issues 6% cumulative preferred stock with a total par value of $500,000 on July 1, and dividends accrue from the issue date. The preferred dividend for the year is 6% × $500,000 × 6/12 = $15,000, not $30,000.
If Kestrel’s net income is $300,000 and weighted average common shares are 100,000, basic EPS is ($300,000 − $15,000) ÷ 100,000 = $2.85.
Cumulative vs. noncumulative: what do you subtract?
| Situation | Cumulative preferred | Noncumulative preferred |
|---|---|---|
| Dividend declared this year | Subtract this year’s dividend | Subtract the dividend declared |
| No dividend declared, net income | Subtract this year’s dividend anyway | Subtract nothing |
| No dividend declared, net loss | Add this year’s dividend to the loss | Add nothing |
| Arrears from prior years paid this year | Subtract only this year’s dividend | Not applicable (no arrears) |
| Dividend declared but paid next year | Subtract this year’s dividend | Subtract it in the year declared |
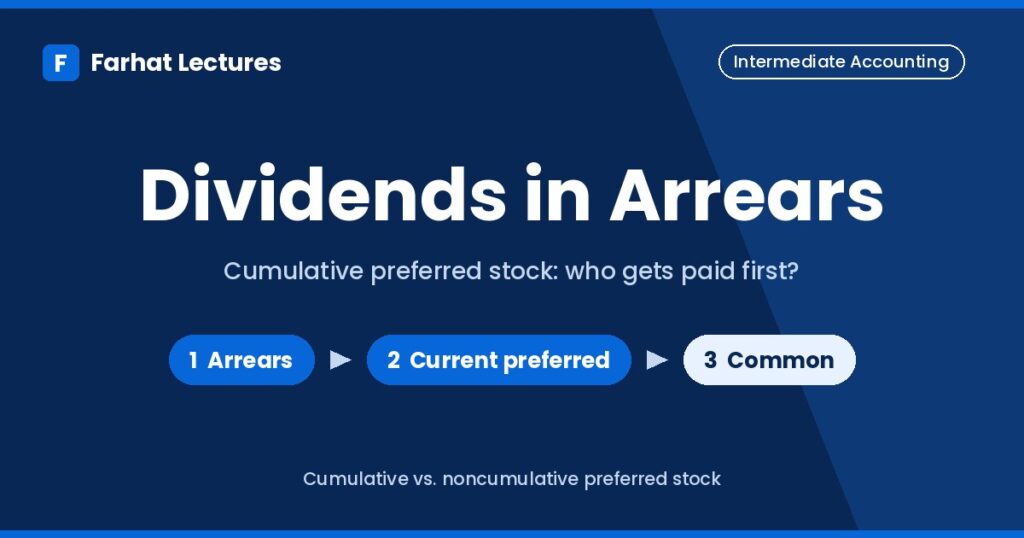
The arrears rule trips up many students. Missed cumulative dividends were already subtracted in the years they built up, so subtracting them again would double count. The dividends in arrears lesson shows the payment order when dividends resume: arrears first, then the current preferred dividend, then common stockholders.
Two less common variations are worth knowing. Some preferred stock is cumulative only if earned; in that case, subtract the dividend only to the extent it is earned for the year. And if the preferred stock is participating, it can share in extra dividends alongside common stockholders, so EPS uses the two-class method instead. You can see how participation works in participating preferred stock dividends.
Worked example: Ridgeway Corp., four cases
Hypothetical example. Ridgeway Corp. has 6% preferred stock with a total par value of $1,000,000, so the annual preferred dividend is $60,000. Weighted average common shares are 150,000.
| Case | Net income (loss) | Preferred adjustment | Available to common | Basic EPS |
|---|---|---|---|---|
| A. Cumulative, dividend declared | $510,000 | ($60,000) | $450,000 | $3.00 |
| B. Cumulative, no dividend declared | $510,000 | ($60,000) | $450,000 | $3.00 |
| C. Noncumulative, no dividend declared | $510,000 | $0 | $510,000 | $3.40 |
| D. Cumulative, net loss, no dividend declared | ($90,000) | ($60,000) | ($150,000) | ($1.00) |
Cases A and B give the same EPS: declaring the cumulative dividend does not change the numerator. Case C differs because a skipped noncumulative dividend is gone for good. Case D shows the dividend increasing the loss per share.
Continuing operations and net income
When a company reports discontinued operations, it subtracts preferred dividends from income from continuing operations and from net income. Suppose Ridgeway (Case A) had $555,000 of income from continuing operations and a $45,000 loss from discontinued operations.
| Line | Amount | Per share (150,000 shares) |
|---|---|---|
| Income from continuing operations less $60,000 preferred dividends | $495,000 | $3.30 |
| Loss from discontinued operations, net of tax | ($45,000) | ($0.30) |
| Net income available to common stockholders | $450,000 | $3.00 |
How these lines appear on the income statement is covered in simple vs. complex capital structure.
Basic EPS for income from continuing operations and for net income must appear on the face of the income statement. The per-share amount for discontinued operations can appear either on the face of the income statement or in the notes.
Preferred dividends in diluted EPS: when do you add them back?
Diluted EPS shows what EPS would be if securities that can turn into common stock were converted. For convertible preferred stock, you use the if-converted method (FASB ASC 260-10-45-40). That means you assume the preferred shares became common shares at the start of the year, or on the issue date if later.
Once converted, the preferred stock would no longer earn a preferred dividend. So you add back the preferred dividends you subtracted for basic EPS, and you add the common shares that conversion would create to the denominator. There is no tax adjustment, because dividends are not tax deductible for the corporation.
Hypothetical example: suppose Ridgeway’s preferred stock (Case A) could convert into 30,000 common shares, and Ridgeway has no other dilutive securities.
| Line | Amount |
|---|---|
| Income available to common stockholders (basic) | $450,000 |
| Add back convertible preferred dividends | $60,000 |
| Diluted EPS numerator | $510,000 |
| Weighted average common shares (basic) | 150,000 |
| Add shares from assumed conversion | 30,000 |
| Diluted EPS denominator | 180,000 |
| Diluted EPS ($510,000 ÷ 180,000) | $2.83 (rounded) |
When discontinued operations are reported, use income from continuing operations available to common stockholders as the control number for testing dilution. Ridgeway has no other potential common shares in this example, so compare the preferred dividend add-back per conversion share ($60,000 ÷ 30,000 = $2.00) with basic EPS from continuing operations ($495,000 ÷ 150,000 = $3.40). Because $2.00 is below $3.40, the conversion is dilutive. Include the conversion in the diluted calculation for net income, which gives $2.83 per share.
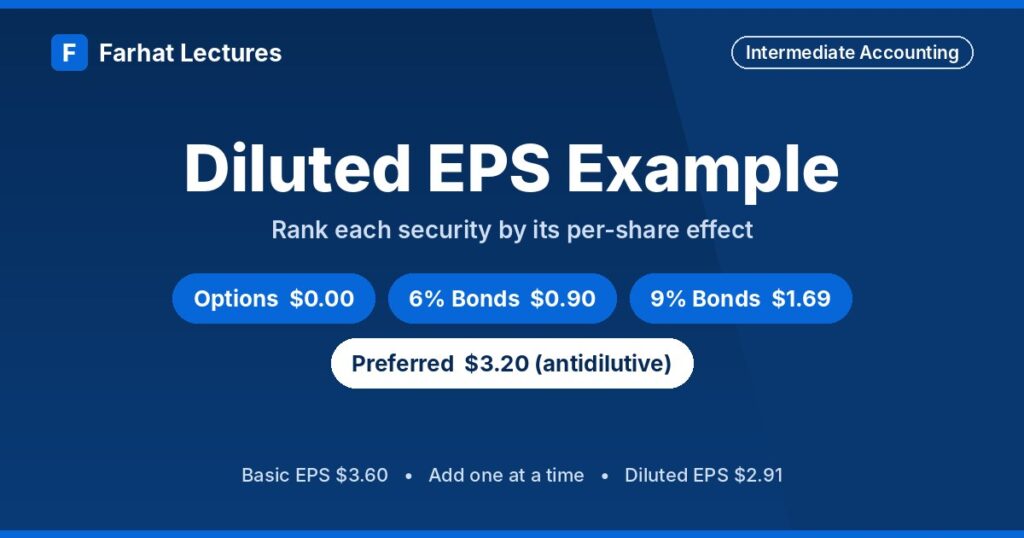
Only add back what you subtracted. If noncumulative convertible preferred stock had no dividend declared, nothing was subtracted for basic EPS, so nothing is added back. For a full walkthrough with bonds and options, see our diluted EPS example.
Common mistakes
- Skipping undeclared cumulative dividends. They are always subtracted for the current year.
- Subtracting arrears again. Only the current year’s cumulative dividend belongs in this year’s EPS.
- Subtracting undeclared noncumulative dividends. If none were declared, nothing is subtracted.
- Focusing on payment instead of declaration. Declaration drives the noncumulative adjustment.
- Understating the loss available to common stockholders. Subtract applicable preferred dividends from the signed net loss to make it more negative.
- Subtracting common dividends. Common dividends never reduce the EPS numerator.
- Forgetting the diluted EPS add-back. When convertible preferred stock is dilutive, add its dividends back to the diluted EPS numerator.
Practice questions with answers
Preferred Stock Dividends and Basic Earnings per Share (EPS) Practice
Basic earnings per share equals income available to common stockholders divided by weighted-average common shares outstanding. In this three-question exercise, identify the numerator and denominator and determine how omitting a required preferred dividend deduction affects basic EPS.
Question 1: Noncumulative dividend declared, paid next year
Cedar Point Inc. had net income of $300,000. Its 5% noncumulative preferred stock has a total par value of $400,000, and the board declared the $20,000 dividend in December, payable in January. Weighted average common shares are 70,000. Compute basic EPS.
Answer:
Basic EPS = $4.00
The dividend was declared this year, so subtract it: ($300,000 − $20,000) ÷ 70,000 = $4.00. The January payment date does not matter.
Question 2: Cumulative dividends with arrears paid
Granite Co. has 8% cumulative preferred stock with a total par value of $250,000, two years in arrears. This year it declared $60,000 of preferred dividends to clear the arrears and pay the current year. Net income is $445,000 and weighted average common shares are 100,000. Compute basic EPS.
Answer:
Basic EPS = $4.25
Subtract only this year’s dividend: 8% × $250,000 = $20,000. ($445,000 − $20,000) ÷ 100,000 = $4.25. The $40,000 of arrears was subtracted in the prior two years.
Question 3: Net loss with cumulative preferred
Summit Labs had a net loss of $130,000. Its cumulative preferred stock carries a $10,000 annual dividend that was not declared. Weighted average common shares are 80,000. Compute the loss per share.
Answer:
Loss per share = ($1.75)
Subtract the cumulative preferred dividend from the signed net loss (−$130,000 − $10,000 = −$140,000). Divide −$140,000 by 80,000 weighted average common shares to get −$1.75 per share.
Want more practice like this? Work through Basic Earnings Per Share (EPS) in the Farhat Lectures Intermediate Accounting course.
Key takeaways
- Basic EPS numerator = net income − preferred dividends (income available to common stockholders).
- Cumulative preferred: subtract the current year’s dividend every year, declared or not.
- Noncumulative preferred: subtract only dividends declared during the year.
- Never subtract arrears a second time.
- With a net loss, preferred dividends increase the loss per share.
- If preferred stock was issued during the year, subtract only the dividend for the months it was outstanding.
- For diluted EPS, add back dividends on convertible preferred stock when conversion is dilutive.
Frequently asked questions
Why subtract cumulative preferred dividends that were not declared?
Cumulative preferred stockholders keep the right to every missed dividend, and all of it must be paid before common stockholders can receive any dividends. So each year’s cumulative dividend is set aside for preferred stockholders, declared or not. FASB ASC 260-10-45-11 requires you to deduct it because that part of earnings is not available to common stockholders.
Do I subtract dividends in arrears when they are finally paid?
No. Each year’s cumulative dividend was already subtracted in its own year. In the year the arrears are paid, subtract only the current year’s dividend.
Does it matter whether the preferred dividend was paid?
No. For noncumulative preferred stock, what matters is whether the dividend was declared during the year. A dividend declared in December and paid in January is still subtracted in the year declared.
What happens to preferred dividends when there is a net loss?
Add them to the loss. For example, a $90,000 net loss and a $60,000 cumulative preferred dividend give a $150,000 loss available to common stockholders.
Are preferred dividends subtracted from income from continuing operations too?
Yes. When the income statement shows income from continuing operations, the preferred dividends are subtracted from that subtotal as well as from net income, so each per-share line reflects common stockholders’ share.
Do you add preferred dividends back for diluted EPS?
Only for convertible preferred stock that is dilutive. Under the if-converted method, add back the preferred dividends deducted in basic EPS and add the common shares from assumed conversion. When discontinued operations are reported, test dilution using EPS from continuing operations. If assumed conversion would increase EPS in the dilution test, exclude the preferred stock.
What if preferred stock was issued during the year?
Subtract only the dividend for the part of the year the shares were outstanding. For example, 6% preferred stock with a $500,000 total par value issued on July 1 creates a $15,000 deduction (6% × $500,000 × 6/12), not $30,000.
Do you adjust preferred dividends for taxes in EPS?
No. Under U.S. GAAP you subtract the full preferred dividend. Dividends are not tax deductible for the corporation, so there is no tax effect to remove.
Sources
- Deloitte Roadmap: Earnings per Share, Section 3.2 Income Available to Common Stockholders (ASC 260-10-45-11)
- FASB Accounting Standards Codification, Topic 260: Earnings Per Share
- Deloitte Roadmap: Earnings per Share, Section 9.1 Presentation
- Deloitte Roadmap: Earnings per Share, Section 4.4 If-Converted Method
About the author
Mansour Farhat, CPA, CIA, DBA, teaches accounting and CPA exam review at Farhat Lectures and on the Farhat Lectures YouTube channel.
Continue learning with Farhat Lectures
Strengthen your accounting understanding with clear explanations and guided practice.
Explore the free sample course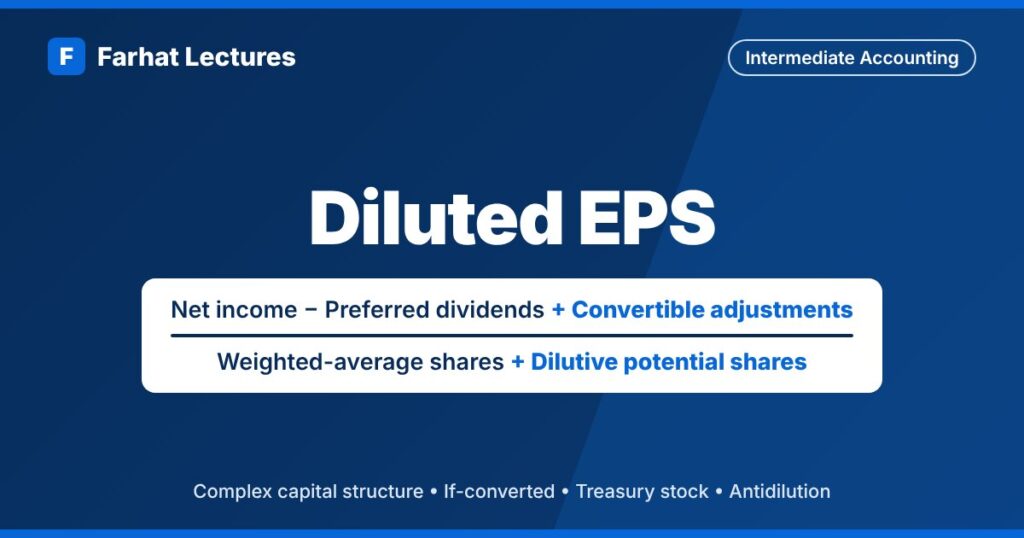
Responses