
Convertible Bonds vs. Bonds with Warrants: Detachable vs. Nondetachable Warrants

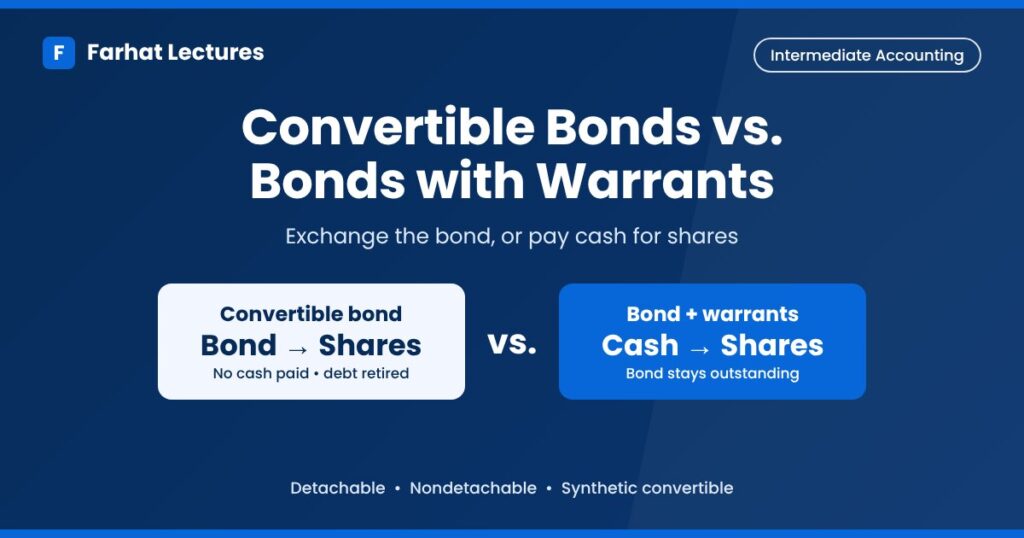
Convertible bonds vs bonds with warrants comes down to cash and debt. A convertible bond is swapped for shares: the holder pays no cash, and the debt disappears. When a holder exercises a detachable warrant for cash, the bond stays outstanding. Equity-classified detachable warrants receive part of the issue proceeds. If the warrant is nondetachable and exercise requires surrendering the bond, the package follows convertible debt accounting.
Both securities are “sweeteners” that let a company borrow at a lower interest rate by giving investors a stake in future stock price growth. Because they look alike, students often mix up their journal entries. Knowing which feature you are dealing with tells you whether to split the proceeds at issuance and what to record when the holder finally takes shares.
Watch: convertible bonds and detachable warrants
Professor Farhat works one example on bonds with detachable warrants and one on converting convertible bonds. Watch both, then compare them with the table below.
This video was published in 2020. The written examples on this page follow current U.S. GAAP, including ASU 2020-06.
How are convertible bonds and bonds with warrants alike?
A convertible bond lets the holder exchange the bond for a set number of common shares. A stock warrant lets the holder buy common shares at a fixed price for a set period. In both cases the investor gets an option on the company’s stock in addition to interest. That option is why investors accept a lower coupon rate (the stated interest rate printed on the bond).
Both also create more common shares if the option is used. That makes them dilutive securities: they can reduce each existing stockholder’s ownership percentage and lower earnings per share.
What is the difference between convertible bonds and bonds with warrants?
| Convertible bond | Bond with equity-classified detachable warrants | |
|---|---|---|
| What the holder gives up to get shares | The bond itself | Cash equal to the exercise price |
| Cash the company receives when shares are issued | None | Exercise price × shares issued |
| What happens to the bond | Retired when converted | Stays outstanding when the warrant is exercised for cash |
| Can the option be sold separately? | No, it is part of the bond | Yes, the warrants trade on their own |
| Recording at issuance | Generally all proceeds to Bonds Payable | Proceeds split between Bonds Payable and Paid-in Capital—Stock Warrants |
| Effect on the balance sheet when shares are issued | Liabilities go down and equity goes up by the same amount | On cash exercise, cash and equity go up and the bond liability stays |
How are detachable and nondetachable warrants recorded?
The table compares equity-classified detachable warrants with nondetachable warrants that require the holder to surrender the bond at exercise.
| Detachable warrants | Nondetachable warrants | |
|---|---|---|
| Can be sold apart from the bond? | Yes | No, only together with the bond |
| Treated like | Two separate securities | A convertible bond (a “synthetic convertible”) |
| Allocation of proceeds | Relative fair value (proportional) method, or the incremental method when only one fair value is known | Generally all proceeds go to the bonds under convertible debt accounting |
| Equity recorded at issuance | Paid-in Capital—Stock Warrants | None |
The rule for nondetachable warrants comes from ASC 470-20-25-3. If the warrants cannot be detached and the bond must be surrendered to exercise them, the two pieces together are substantially equivalent to convertible debt and follow convertible debt accounting.
A quick word on the label. The Codification never uses the phrase “synthetic convertible.” The guidance treats the package as substantially equivalent to convertible debt when the warrant is nondetachable and the holder must surrender the bond to exercise it. In finance, “synthetic convertible” is also used for a bond paired with separately traded warrants or options. On an exam, check separately whether the warrant can be transferred on its own and whether exercise requires surrendering the bond. Some detachable warrants also allow a bond to be surrendered as payment of the exercise price.
One more condition. The proportional and incremental methods apply when the detachable warrants are classified as equity, which is the standard textbook case. If the warrants must be classified as a liability, they are measured at fair value first and the bonds get whatever is left. That situation is beyond this lesson.
For detachable warrants, the allocation and the later exercise and expiration entries are worked step by step in bonds with detachable warrants: journal entries.
Example: the same bond issue recorded three ways
Ridgeway Corp. (hypothetical) raises money with $1,000,000 of bonds sold at 104, so it receives $1,040,000. Compare three versions of the deal.
1. Convertible bonds
The conversion feature is not recorded separately in this basic case, so the whole amount is debt. The extra $40,000 above face value is a premium.
| Account | Debit | Credit |
|---|---|---|
| Cash | 1,040,000 | |
| Bonds Payable | 1,000,000 | |
| Premium on Bonds Payable | 40,000 |
2. Bonds with nondetachable warrants
Assume the holder must surrender the bond to exercise the warrant and the same single-liability treatment applies. The entry is identical to the convertible bond entry above. No amount is credited to equity.
3. Bonds with detachable warrants
Now the package includes 10,000 equity-classified detachable warrants. At issuance, the bonds alone have a fair value of 97% of face value ($970,000), and the warrants have a fair value of $7 each ($70,000). The total fair value of $1,040,000 equals the proceeds, so each security gets its own fair value.
| Account | Debit | Credit |
|---|---|---|
| Cash | 1,040,000 | |
| Discount on Bonds Payable | 30,000 | |
| Bonds Payable | 1,000,000 | |
| Paid-in Capital—Stock Warrants | 70,000 |
Same cash, very different balance sheets. The convertible and synthetic convertible versions report a $40,000 premium and no equity. The detachable version reports a $30,000 discount and $70,000 of paid-in capital, so its future interest expense will be higher. To see how a premium or discount is spread over a bond’s life, work through calculating a bond premium and building the amortization schedule.
What happens when bonds are converted or warrants are exercised?
The difference shows up again when investors take their shares.
Conversion. Assume holders of $100,000 face value of Ridgeway’s convertible bonds convert them into 2,500 shares of $1 par common stock when the related bonds have a carrying value of $102,000 (the $100,000 face value plus $2,000 of premium not yet amortized). Under the book value method, the carrying value moves to equity and no gain or loss is recorded. No cash is received.
| Account | Debit | Credit |
|---|---|---|
| Bonds Payable | 100,000 | |
| Premium on Bonds Payable | 2,000 | |
| Common Stock (2,500 × $1) | 2,500 | |
| Paid-in Capital in Excess of Par—Common Stock | 99,500 |
Exercise. Under the detachable version, holders exercise all 10,000 warrants for cash, each buying one $1 par share for $25. Ridgeway receives cash and removes the warrant capital. The $1,000,000 of bonds is still owed.
| Account | Debit | Credit |
|---|---|---|
| Cash (10,000 × $25) | 250,000 | |
| Paid-in Capital—Stock Warrants | 70,000 | |
| Common Stock (10,000 × $1) | 10,000 | |
| Paid-in Capital in Excess of Par—Common Stock | 310,000 |
A one-line note on current rules: Accounting Standards Update 2020-06 simplified convertible debt accounting so that most convertible bonds are now recorded as a single liability, which is the treatment shown above. Two special cases still split the proceeds: a conversion feature that must be accounted for as a derivative, and a convertible bond issued at a substantial premium, where the premium is recorded as paid-in capital. Both are outside this lesson.
Key takeaways
- When a convertible bond is exchanged solely for shares under its original terms in the example above, no cash comes in. The issuer transfers the debt’s carrying value to equity and records no gain or loss.
- When a detachable warrant is exercised for cash, equity goes up and the bond stays on the books.
- Equity-classified detachable warrants get their own share of the issuance proceeds, credited to paid-in capital for the warrants.
- When a warrant is nondetachable and exercise requires surrendering the bond, the package follows convertible debt accounting. Most such issues are recorded as a single liability.
- Under ASU 2020-06, most convertible bonds are recorded as a single liability with no separate equity piece.
Common mistakes
- Allocating proceeds to a nondetachable warrant when exercise requires surrendering the bond. The package follows convertible debt accounting.
- Recording all proceeds as debt when the issue includes equity-classified detachable warrants. Allocate part of the proceeds to the warrants.
- Debiting Bonds Payable when detachable warrants are exercised for cash. The bond stays outstanding, and the entry records the cash received and the related equity changes.
- Debiting Cash when bonds are converted. Conversion is an exchange, not a sale for cash.
- Assuming a premium on the package means a premium on the bonds. With detachable warrants, the bonds can still end up at a discount.
Exam tip: Before you write an entry, check whether the warrant can be transferred separately and how the holder pays to exercise it. For a detachable warrant, confirm whether it is classified as equity or a liability before allocating the issuance proceeds.
Preparing for the FAR section? The sample CPA FAR course shows how debt and equity topics like this one are tested.
Interactive practice on convertible bonds and stock warrants
Convertible Bonds vs. Bonds With Warrants
Use this four-question CPA practice exercise to compare what happens to cash and debt when a holder converts a bond or exercises a detachable stock warrant. Then decide how the issuer records the proceeds for bonds with detachable or nondetachable warrants. Select one answer per question, check your work, and review the explanations.
Practice questions with answers
1. A company issues $600,000 of bonds with nondetachable warrants at 101. The holder must surrender the bonds to exercise the warrants. Assume the package is accounted for as a single liability. Record the issuance.
| Account | Debit | Credit |
|---|---|---|
| Cash | 606,000 | |
| Bonds Payable | 600,000 | |
| Premium on Bonds Payable | 6,000 |
Why: The warrants are nondetachable and exercise requires surrendering the bonds. Under the single-liability model, all proceeds are recorded as debt.
2. The same bonds are issued at 101 with 4,000 equity-classified detachable warrants. At issuance, the bonds alone have a fair value of 99% of face value, and each warrant is worth $3. Record the issuance.
The fair values are $594,000 for the bonds and $12,000 for the warrants, which add up to the $606,000 received.
| Account | Debit | Credit |
|---|---|---|
| Cash | 606,000 | |
| Discount on Bonds Payable | 6,000 | |
| Bonds Payable | 600,000 | |
| Paid-in Capital—Stock Warrants | 12,000 |
3. Investor A converts a $50,000 convertible bond into shares. Investor B, who holds a $50,000 bond with detachable warrants, exercises warrants for 500 shares at $40 each. After these events, how much does the company still owe each investor on the bonds, and how much cash did it receive?
Answer: The company owes Investor A nothing on that bond and received no cash. It still owes Investor B the $50,000 bond and received $20,000 in cash (500 × $40).
Frequently asked questions
What is a synthetic convertible?
In this lesson, the term describes a bond issued with nondetachable warrants that the holder can exercise only by surrendering the bond. The warrants cannot be transferred separately, and the package follows convertible debt accounting. In finance, “synthetic convertible” can also mean a bond paired with separate warrants or options, so check the terms of the instruments.
Do nondetachable warrants get a separate equity allocation?
When exercise requires surrendering the bond and the warrants are nondetachable, U.S. GAAP treats the package as substantially equivalent to convertible debt. Under the single-liability model illustrated here, all proceeds are recorded as debt.
Why would a company issue bonds with warrants instead of convertible bonds?
When holders exercise detachable warrants for cash, the company receives cash and the bonds remain outstanding. When holders exchange convertible bonds solely for shares, the company receives no cash and removes the debt.
Are both convertible bonds and warrants dilutive?
Both are potentially dilutive. For convertible bonds, the if-converted method assumes conversion, adds back after-tax interest, and adds the resulting common shares. For warrants, the treasury stock method generally assumes exercise proceeds are used to repurchase shares at the average market price. Include a security only if it reduces the applicable EPS measure. If discontinued operations are reported, use EPS from continuing operations to test for dilution.
Do you still split the proceeds of a convertible bond under current GAAP?
Usually not. Since ASU 2020-06, most convertible bonds are recorded as a single liability, with no separate equity amount for the conversion feature. Two exceptions remain: a conversion feature that must be accounted for as a derivative, and a convertible bond issued at a substantial premium, where the premium is recorded as paid-in capital.
What if the fair values of the bonds and warrants don’t add up to the cash received?
Use the proportional method. Say Ridgeway receives $1,040,000, the bonds alone are worth $1,050,000, and the warrants are worth $70,000, for a total of $1,120,000. The warrants get $70,000 ÷ $1,120,000 × $1,040,000 = $65,000, and the bonds get the remaining $975,000, which means a $25,000 discount on the $1,000,000 bonds. If only the warrants’ fair value is known, use the incremental method: give the warrants their fair value and the bonds whatever is left.
What happens if detachable warrants expire unexercised?
The amount in the stock warrants account moves to a paid-in capital account for expired warrants. In the Ridgeway example, debit the stock warrants account for $70,000 and credit Paid-in Capital from Expired Warrants for $70,000. No gain is recorded, and the bonds are not affected.
For a broader introduction to warrants, including why companies issue them, see the stock warrants overview. Convertible preferred stock works on the same idea as a convertible bond and is covered in preferred stock features. For a full walkthrough of conversions inside the course, see the convertible securities lesson.
About the author
Mansour Farhat, CPA, CIA, DBA, is the instructor behind Farhat Lectures, where he teaches accounting courses and CPA exam review. Learn more about Mansour.
Continue learning with Farhat Lectures
Strengthen your accounting understanding with clear explanations and guided practice. Start free, then move into the full course when you are ready.
Explore the free sample course
Responses