
Level 3 Reconciliation: How to Read the Rollforward and Unobservable Inputs

A Level 3 reconciliation (or Level 3 rollforward) is an ASC 820 fair value disclosure. It starts with the beginning balance of items measured at fair value every period using significant unobservable inputs, shows each change (gains and losses, purchases, sales, issues, settlements, and transfers in or out of Level 3), and ends with the ending balance.
This matters because Level 3 fair values rely on management’s own assumptions. The reconciliation, together with the table of unobservable inputs, lets readers judge how much those estimates drove the results. If you need a refresher on the three levels, start with fair value disclosures: Level 1, Level 2, and Level 3 explained.
Watch: The Level 3 reconciliation and unobservable inputs (starts at 2:53, the Level 3 reconciliation)
What goes in a Level 3 reconciliation?
ASC 820-10-50-2(c) requires public companies to reconcile recurring Level 3 measurements and show each type of change separately (PwC Viewpoint, FSP 20.3).
Under ASC 820-10-50-2G, nonpublic entities instead report purchases and issues separately, along with the amounts and reasons for transfers into and out of Level 3. They disclose each direction of transfer separately.
| Line | What it means |
|---|---|
| Beginning balance | Level 3 fair value at the start of the period |
| Total gains or losses in earnings | Realized and unrealized gains or losses reported in net income, plus the income statement line items where they appear |
| Total gains or losses in other comprehensive income (OCI) | For example, fair value changes on available-for-sale debt securities, plus the OCI line items where they appear |
| Purchases, sales, issues, and settlements | Each shown separately |
| Transfers into Level 3 | Items whose significant inputs became unobservable, with the reasons for each transfer |
| Transfers out of Level 3 | Items whose significant inputs became observable, with the reasons for each transfer |
| Ending balance | Level 3 fair value at the end of the period |
Here is the whole schedule in one line:
Beginning balance + gains (or minus losses) in earnings and OCI + purchases and issues – sales and settlements + transfers into Level 3 – transfers out of Level 3 = Ending balance
Liabilities use the same schedule, but read the signs carefully. A fair value gain on a liability lowers its balance, and a loss raises it. Contingent consideration from a business combination is a common Level 3 liability.
Below the schedule, public companies also report the change in unrealized gains or losses for Level 3 items still held at period-end, separately for amounts in earnings and amounts in OCI (ASC 820-10-50-2(d)). Nonpublic entities do not provide either amount.
Worked example: Cobalt Capital Inc.
Hypothetical example. Cobalt Capital Inc., a public company, holds two classes of Level 3 assets ($ in thousands): equity investments in private companies (fair value changes in earnings) and asset-backed debt securities classified as available-for-sale (fair value changes in OCI).
| ($ in thousands) | Private equity investments | Asset-backed securities | Total |
|---|---|---|---|
| Beginning balance | $48,000 | $22,000 | $70,000 |
| Gains (losses) in earnings | 6,000 | — | 6,000 |
| Gains (losses) in OCI | — | (1,500) | (1,500) |
| Purchases | 10,000 | 5,000 | 15,000 |
| Sales | (9,000) | — | (9,000) |
| Settlements | — | (3,000) | (3,000) |
| Transfers into Level 3 | — | 2,500 | 2,500 |
| Transfers out of Level 3 | (4,000) | — | (4,000) |
| Ending balance | $51,000 | $25,000 | $76,000 |
| ($ in thousands) | Private equity investments | Asset-backed securities |
|---|---|---|
| Change in unrealized gains (losses) in earnings, assets still held | $4,500 | — |
| Change in unrealized gains (losses) in OCI, assets still held | — | ($1,500) |
Check the math: $70,000 + $6,000 − $1,500 + $15,000 − $9,000 − $3,000 + $2,500 − $4,000 = $76,000.
How to read the reconciliation
- Gains in earnings ($6,000) vs. still-held gains ($4,500). Of the $6,000, $4,500 relates to investments Cobalt still owns, so it is unrealized and rests on Level 3 estimates. In this example, the other $1,500 came from private equity investments Cobalt sold during the year, so it is now realized. (To keep things simple, assume the investment that moved to Level 1 had no gain while it sat in Level 3.)
- Transfer out ($4,000). One private company completed an initial public offering. Cobalt could then access an active market with an unadjusted quoted price for those same shares, so the investment moved to Level 1.
- Transfer in ($2,500). Trading in one asset-backed security dried up, so Cobalt now relies on its own assumptions. It moved into Level 3.
- Where the $6,000 increase came from. Net gains added $4,500 ($6,000 in earnings minus $1,500 in OCI). Purchases minus sales and settlements added $3,000 ($15,000 minus $9,000 minus $3,000). Net transfers took away $1,500 ($2,500 in minus $4,000 out). So gains, not new buying, drove most of the growth, and $4,500 of those earnings gains are unrealized estimates on investments Cobalt still holds.
Quantitative information about unobservable inputs
For each class of Level 3 measurement, companies disclose the valuation technique and the significant unobservable inputs with numbers. Public companies disclose the range and weighted average of significant unobservable inputs and explain how they calculated the weighted average (ASC 820-10-50-2(bbb)). For certain inputs, they may use a median or another statistic when it better represents the distribution of inputs. Nonpublic entities still describe the technique and give numbers for their significant inputs; they just do not have to show the range and weighted average. In the table below, EBITDA means earnings before interest, taxes, depreciation, and amortization.
| Class | Fair value ($000s) | Valuation technique | Unobservable input | Range (weighted average) |
|---|---|---|---|---|
| Private equity investments | $51,000 | Discounted cash flow | Discount rate | 14%–22% (17%) |
| Long-term growth rate | 2%–4% (3%) | |||
| Market comparables | EBITDA multiple | 7.0x–10.5x (8.4x) | ||
| Asset-backed securities | $25,000 | Discounted cash flow | Prepayment rate | 4%–8% (6%) |
| Default rate | 2%–6% (3.5%) |
In this example, Cobalt weights each input by the relative fair value of the holdings to which that input applies.
Measurement uncertainty
Public companies also give a narrative description of how sensitive recurring Level 3 measurements are to changes in the unobservable inputs, including how the inputs relate to each other. ASU 2018-13 clarified that this narrative describes uncertainty as of the reporting date. For Cobalt, the note might say that a higher discount rate or a lower EBITDA multiple would lower the fair value of its private equity investments, and that higher default rates usually come with lower prepayment rates.
Who reports what after ASU 2018-13
ASU 2018-13 removed some fair value disclosures and added others (Deloitte Heads Up summary).
| Disclosure | Public companies | Nonpublic entities |
|---|---|---|
| Full Level 3 reconciliation | Required | Not required. Disclose purchases, issues, transfers in, and transfers out separately, and give the reasons for the transfers. |
| Change in unrealized gains or losses in earnings and in OCI, Level 3 items still held | Required | Not required |
| Range and weighted average of significant unobservable inputs | Required. An alternative to the weighted average is permitted for certain inputs. | Not required |
| Transfers between Level 1 and Level 2 | Removed under US GAAP (still required under IFRS 13) | Removed under US GAAP |
| Policy for when transfers between levels are deemed to occur | Removed | Removed |
| Description of valuation processes for Level 3 measurements | Removed | Removed |
Your textbook may still list transfers between Levels 1 and 2 as a required disclosure. That reflects older US GAAP and current IFRS 13, paragraph 93(c) (IFRS 13).
Level 3 reconciliation on the CPA exam
Area III.E of the 2026 FAR blueprint covers fair value measurements. Use the Level 3 rollforward to practice applying the fair value hierarchy and interpreting valuation changes and transfers.
For practice, try the following.
- Compute an ending Level 3 balance from a list of changes.
- Decide whether an event is a transfer in, a transfer out, or not part of the schedule at all.
- Pick out which disclosures a nonpublic entity can skip.
Exam tip: before you add an item to the schedule, ask whether it is a recurring Level 3 measurement. Leave out nonrecurring measurements, such as a fair value measurement made only because of an impairment. The schedule also excludes Level 1 and Level 2 measurements and items carried at cost.
Common mistakes
- Putting nonrecurring items in the reconciliation. A measurement made only because of an impairment is nonrecurring. See recurring vs. nonrecurring fair value measurements.
- Treating total gains as unrealized gains. Total gains include realized gains on items sold; the still-held line isolates the unrealized part.
- Ignoring transfers. Transfers change the Level 3 balance without any gain, purchase, or sale.
- Netting purchases against sales. Purchases, sales, issues, and settlements are shown separately.
- Assuming Level 3 values are wrong. They are not wrong, just based on more judgment, which is why the extra disclosures exist.
Practice questions with answers
Level 3 Fair Value Rollforward Practice
Use the Cobalt Capital example to review the U.S. GAAP Level 3 fair value rollforward. Choose one answer per question about the recurring measurements it covers, the order of the balances, and the changes disclosed during the period.
Question 1: Compute the ending balance
A company’s recurring Level 3 assets had a beginning balance of $30,000. During the year it recognized $2,400 of gains in earnings, purchased $7,000, received $5,000 in settlements, and transferred $3,400 out of Level 3. What is the ending balance?
Answer:
$31,000
$30,000 + $2,400 + $7,000 − $5,000 − $3,400 = $31,000.
Question 2: An investee goes public
Cobalt holds a private equity investment it values with a discounted cash flow model. During the year, the investee lists its shares, and Cobalt can access an active market with an unadjusted quoted price for those same shares. Where does this appear in the Level 3 reconciliation?
Answer:
As a transfer out of Level 3
The unadjusted quoted price for identical shares in an active market Cobalt can access is a Level 1 input. Cobalt reports the change as a transfer out of Level 3.
Question 3: Private company relief
A private company holds recurring Level 3 investments. What does it disclose in place of the full reconciliation?
Answer:
Separate amounts for purchases, issues, transfers into Level 3, and transfers out of Level 3, plus the reasons for those transfers
ASU 2018-13 replaced the full rollforward for nonpublic entities with these narrower disclosures.
Want more practice like this? Work through the Disclosure for Investments lesson in the Farhat Lectures Intermediate Accounting course, and compare the instrument-level note in fair value of financial instruments.
Key takeaways
- The Level 3 reconciliation rolls recurring Level 3 balances from beginning to end.
- It separates gains in earnings and OCI, purchases, sales, issues, settlements, and transfers in and out.
- Companies must also disclose the reasons for every transfer into or out of Level 3.
- Unrealized gains on Level 3 items still held are disclosed separately.
- Public companies disclose the range and typically the weighted average of significant unobservable inputs, as well as a narrative on measurement uncertainty.
- Under US GAAP, transfers between Level 1 and Level 2 no longer have to be disclosed; IFRS 13 still requires them.
Frequently asked questions
Is a Level 3 reconciliation the same as a Level 3 rollforward?
Yes. Both terms describe the schedule that starts with the beginning balance of recurring Level 3 fair value measurements, shows each change, and ends with the ending balance.
Why does Level 3 need a reconciliation when Levels 1 and 2 do not?
Level 3 values depend on the company’s own assumptions, so they are the most subjective and the most exposed to estimation error or management bias. The reconciliation shows exactly how the balance changed and how much came from gains and losses.
Do impairment-triggered fair value measurements go in the Level 3 reconciliation?
A fair value measurement made only because of an impairment is nonrecurring and falls outside the Level 3 rollforward. An asset measured at Level 3 fair value each reporting period remains within scope.
Do private companies prepare the full reconciliation?
A nonpublic entity instead discloses separate amounts for purchases, issues, transfers into Level 3, and transfers out of Level 3, plus the reasons for those transfers.
Must companies still disclose transfers between Level 1 and Level 2?
Not under US GAAP; ASU 2018-13 removed that requirement. IFRS 13 still requires it, so you will see it in IFRS financial statements.
What is the formula for a Level 3 reconciliation?
Beginning balance, plus gains (or minus losses) in earnings and OCI, plus purchases and issues, minus sales and settlements, plus transfers into Level 3, minus transfers out of Level 3, equals the ending balance.
How do Level 3 liabilities appear in the reconciliation?
They follow the same schedule, but watch the signs. A fair value gain on a liability reduces its balance, and a loss increases it. Contingent consideration from a business combination is a common Level 3 liability.
How does the Level 3 reconciliation relate to the CPA exam?
Area III.E of the 2026 FAR blueprint covers fair value measurements. The Level 3 rollforward gives you practice computing ending balances, classifying transfers, and identifying which disclosures apply to nonpublic entities.
Sources
- PwC Viewpoint: Financial statement presentation, FSP 20.3 Fair value disclosures (ASC 820-10-50-2)
- Deloitte Heads Up: FASB issues standard to amend fair value measurement disclosures (ASU 2018-13)
- IFRS Foundation: IFRS 13 Fair Value Measurement (paragraph 93)
- FASB Accounting Standards Codification, Topic 820: Fair Value Measurement
About the author
Mansour Farhat, CPA, CIA, DBA, teaches accounting and CPA exam review at Farhat Lectures and on the Farhat Lectures YouTube channel. The Cobalt Capital example and the practice questions in this lesson were written for Farhat Lectures students. Learn more about Mansour on the About page.
Continue learning with Farhat Lectures
Strengthen your accounting understanding with clear explanations and guided practice.
Explore the free sample course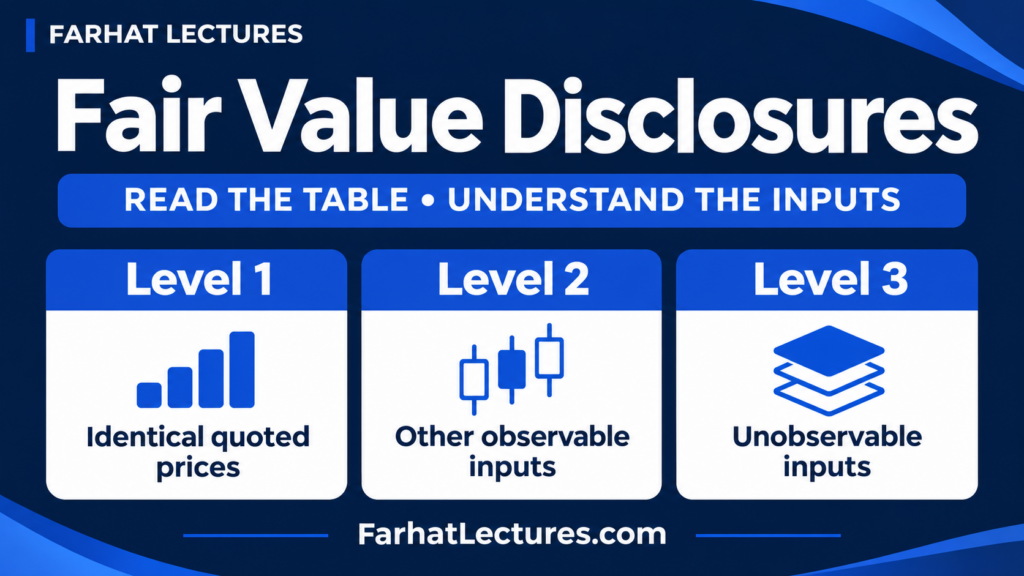

Responses